
Key points
UK allowances have been cut hard, so the order you use the tax wrappers in matters more in 2026/27.
✓ Growth, dividends and interest inside an ISA are free of income tax and capital gains tax.
✓ Pensions give income tax relief going in at your highest rate, and a quarter can usually come out tax-free.
✓ Premium Bond prizes are free of income tax and capital gains tax.
✓ Outside a wrapper you have a £3,000 capital gains exempt amount and a £500 dividend allowance.
✓ Moving abroad changes how the wrappers work, and your new country may not recognise them.
Growing your wealth is one thing. Keeping more of it is another. The UK's tax-free allowances have been cut hard in recent years, and from 2026 the tax rates on investment income are rising too.
The good news is that the UK still offers some of the most generous tax wrappers anywhere. ISAs, pensions, Premium Bonds and simple planning between spouses can shelter most of what a typical investor earns, legally and without complexity.
This guide covers the 2026/27 limits, what changes from April 2027, how to use each wrapper in the right order, and what happens to them if you move abroad.
Why does tax efficiency matter more in 2026/27?
Have you noticed your tax bill creeping up even when your returns were flat? That is not your imagination. The capital gains annual exempt amount has fallen from £12,300 in 2022/23 to £3,000, and the dividend allowance from £2,000 to £500.
Rates are moving as well. From 6 April 2026 the dividend ordinary and upper rates rose by 2 percentage points, to 10.75% and 35.75%. From 6 April 2027, tax on savings interest rises to 22%, 42% and 47%, and property income gets its own rates at the same levels.

Image 1: your 2026/27 allowances and what changes next
Allowance | 2026/27 figure | What changes next |
|---|---|---|
ISA | £20,000 a year across all ISAs, with tax-free growth and income | 6 April 2027: cash ISAs capped at £12,000 if under 65 |
Pension | £60,000 annual allowance, tapering to £10,000, with 25% tax-free cash | 6 April 2027: unused pensions count for inheritance tax |
Capital gains | £3,000 exempt amount, then 18% basic rate and 24% higher rate | Down from £12,300 in 2022/23 |
Dividends | £500 allowance, then 10.75% / 35.75% / 39.35% | 6 April 2026: ordinary and upper rates up 2 points |
Savings interest | £1,000 / £500 personal savings allowance, £0 for additional rate | 6 April 2027: rates rise to 22% / 42% / 47% |
Premium Bonds | £50,000 maximum holding, with prizes free of income tax and CGT | Prize rate is an average and can change |
👉 GOV.UK: new tax rates for property, savings and dividend income
👉 The law: Finance Act 2026, section 4 (higher dividend tax rates)
That makes wrappers and planning essential rather than optional. Money inside an ISA or a pension is not touched by any of these rate rises.
ISAs: your flexible tax-free pot
Growth, dividends and interest inside an ISA are free of income tax and capital gains tax, nothing goes on your tax return, and you can usually take the money out whenever you like.
For 2026/27 you can pay in up to £20,000 in total across your ISAs:
➜ Cash ISAs: for emergency funds and short-term savings.
➜ Stocks and shares ISAs: for long-term investment growth.
➜ Innovative finance ISAs: for peer-to-peer lending, with higher risk to your capital.
➜ Lifetime ISAs: up to £4,000 a year within the £20,000, opened between 18 and 39, with a 25% government bonus for a first home or for retirement from 60. Other withdrawals carry a 25% charge.
What changes in April 2027? From 6 April 2027, anyone under 65 can only pay £12,000 a year into cash ISAs. The £20,000 overall limit stays, so the remaining £8,000 has to go into a stocks and shares or other ISA, and transfers from stocks and shares ISAs into cash will be blocked. Savers aged 65 and over keep the full £20,000 cash option.
If you are under 65 and prefer cash, 2026/27 is the last year you can put the full £20,000 into a cash ISA.
👉 The law: The Individual Savings Account Regulations 1998
👉 GOV.UK: draft regulations for the £12,000 cash ISA limit
Pensions: relief going in, tax-free growth inside
You get income tax relief on the way in at your highest rate, the investments grow free of income tax and capital gains tax, and a quarter can usually come out tax-free.
➜ Basic rate taxpayers: £100 into your pension costs you £80. Your provider claims the other £20 from HMRC.
➜ Higher rate taxpayers: the same £100 costs £60. You claim the extra £20 through Self Assessment or your tax code.
➜ Additional rate taxpayers: £100 costs £55, with the extra £25 claimed the same way.
For 2026/27 the annual allowance is £60,000, or 100% of your UK earnings if that is lower. Unused allowance from the previous three tax years can usually be carried forward, as long as you were a member of a registered pension scheme in those years.
The tax-free lump sum is normally 25% of what you take, capped at £268,275 across all your pensions unless you hold a protection. The rest is taxed as income when you draw it.
Watch the taper. If your threshold income is over £200,000 and your adjusted income is over £260,000, your annual allowance falls by £1 for every £2 over, down to £10,000. Once you have flexibly accessed a pension, a £10,000 money purchase annual allowance applies instead. Paying in more than your limit triggers an annual allowance charge.
A change is coming. From 6 April 2027, most unused pension funds will count towards your estate for inheritance tax.
👉 GOV.UK: tax on your private pension contributions
👉 The law: Finance Act 2004, section 188 (relief for contributions)
Premium Bonds: tax-free prizes on cash
NS&I Premium Bonds pay no interest. Instead, each £1 bond goes into a monthly prize draw, and every prize is free of income tax and capital gains tax.
You can hold up to £50,000. The prize fund rate is an average and changes from time to time, so your own return can be lower. They tend to suit:
➜ Higher and additional rate taxpayers: who have used their personal savings allowance and their ISA allowance.
➜ Cautious savers: the capital is backed by HM Treasury.
Managing capital gains and dividends outside a wrapper
What about investments you hold outside an ISA or pension? This is where the 2026/27 position bites. You have a £3,000 capital gains exempt amount, a £500 dividend allowance and, for interest, a personal savings allowance of £1,000 for basic rate taxpayers, £500 for higher rate and nothing for additional rate.
Above those allowances, the rates are:
➜ Capital gains: 18% within your basic rate band, 24% above it.
➜ Dividends: 10.75% basic rate, 35.75% higher rate, 39.35% additional rate.
➜ Savings interest: 20%, 40% and 45% for 2026/27, rising to 22%, 42% and 47% from April 2027.
Four steps make a real difference:
➜ Use each year's exempt amount: spreading disposals across tax years uses a fresh £3,000 each time. If you are close to 5 April, waiting a few days gives you a second allowance.
➜ Claim your losses: a loss can be set against gains in the same year or carried forward, but only if you claim it within four years of the end of the tax year it arose.
➜ Bed and ISA: sell a holding and buy it back inside your ISA. You use your exempt amount on the sale, and all future growth is sheltered.
➜ Shelter income first: dividends and interest are taxed every year, so income-producing holdings usually gain most from sitting inside a wrapper.
👉 The law: Income Tax Act 2007, section 13A (dividend nil rate)
👉 GOV.UK: Capital Gains Tax allowances
👉 The law: Taxation of Chargeable Gains Act 1992, section 1K (annual exempt amount)
Spousal transfers: use both sets of allowances
Transfers between spouses and civil partners who live together are treated as no gain, no loss. That means you can move assets to whoever pays the lower rate before they are sold.
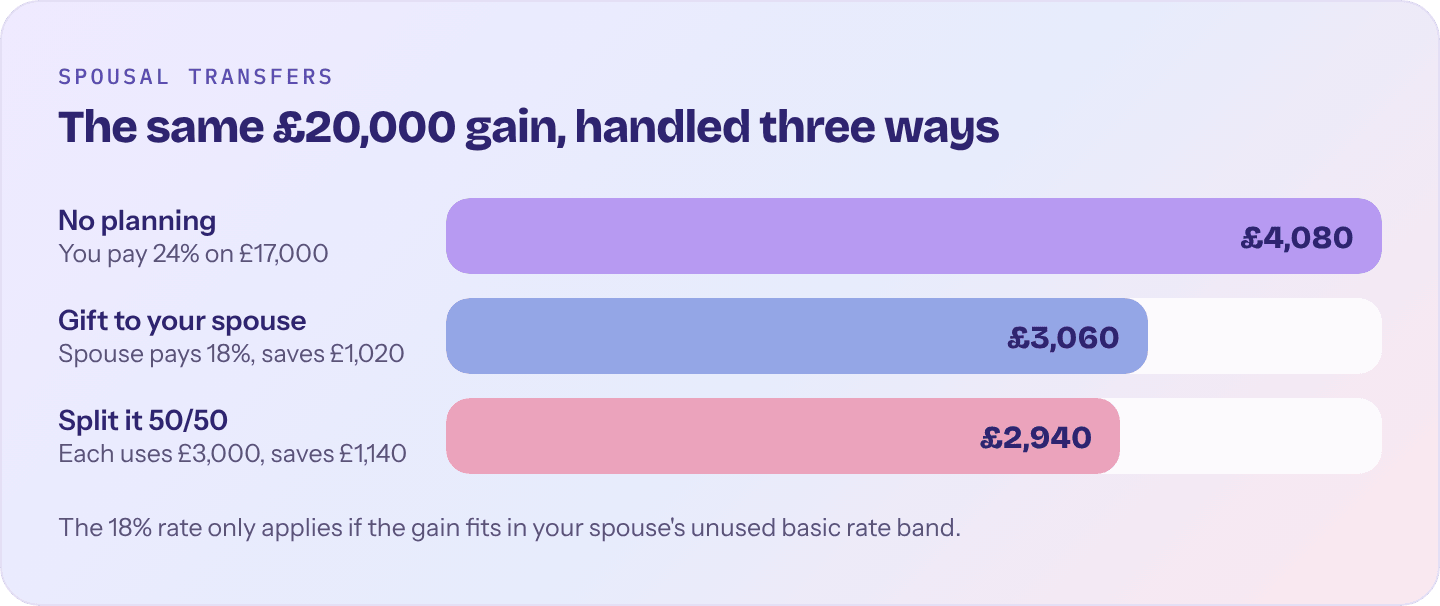
Image 2: the same gain, handled three ways
Take a £20,000 gain where you are a higher rate taxpayer and your spouse is a basic rate taxpayer:
➜ No planning: you sell and pay 24% on £17,000 after your exempt amount, which is £4,080.
➜ Gift the holding outright: your spouse sells and pays 18% on £17,000, which is £3,060. A saving of £1,020.
➜ Split it 50/50: you each have a £10,000 gain and each use a £3,000 exempt amount. You pay 24% on £7,000 and your spouse 18% on £7,000, which is £2,940 in total. A saving of £1,140.
The 18% rate only applies to the extent the gain fits in your spouse's unused basic rate band, so check there is room. The transfer must also be a genuine, outright gift. If you keep control of the asset or its income, HMRC can ignore the transfer.
The same idea works for income. Moving dividend-paying shares or savings to a lower-earning spouse uses their allowances and lower rates. For jointly owned assets, married couples are taxed 50/50 by default unless they send HMRC a Form 17 declaration reflecting unequal ownership.
👉 GOV.UK: Capital Gains Tax on gifts to your spouse or civil partner
👉 The law: Taxation of Chargeable Gains Act 1992, section 58 (spouses and civil partners)
What happens to your wrappers if you move abroad?
Most of this still works for you, but the rules change once you are non-resident, and your new country may not recognise UK wrappers at all.
➜ ISAs: you keep your ISA and it stays tax-free in the UK. You can pay in during any tax year you are UK resident, but not while you are non-resident. See 📖 can I keep my ISA if I move abroad?
➜ Pensions: UK relief on your own contributions depends on being a "relevant UK individual". Without UK earnings, a non-resident generally gets relief on up to £3,600 gross a year, and only for five tax years after leaving.
➜ UK dividends and interest: non-residents can often limit their UK tax on these to nil under the 📖 disregarded income rules.
➜ Local tax: Spain, France, Portugal and the US, among others, can tax income and gains inside an ISA. US citizens should read our guide to the 📖 UK-US double tax treaty first.
Moving the other way? New arrivals can open an ISA once they are UK resident, and anyone who has not been UK resident for ten years may be able to shelter foreign income and gains under the 📖 4-year FIG regime.
👉 GOV.UK: ISAs if you move abroad
👉 HMRC manual: who gets pension tax relief (PTM044100)
👉 The law: Finance Act 2004, section 189 (relevant UK individuals)
Building a strategy that fits
Every situation is different, but for most UK taxpayers the order looks like this:
Take any employer pension match: it is the best return you will get anywhere.
Use your ISA allowance: £20,000 of flexible, tax-free saving, and your last chance for a full £20,000 in cash if you are under 65.
Top up your pension: especially if you are a higher or additional rate taxpayer, or within reach of the £100,000 personal allowance taper.
Use your exempt amounts deliberately: a yearly Bed and ISA moves holdings into shelter while using allowances you would otherwise waste.
Coordinate with your spouse: make sure both sets of allowances are used and assets sit with the lower-rate partner.
Review every April: with rates changing in 2026, 2027 and 2029, last year's plan may not be this year's best.
Frequently asked questions
What is the ISA allowance for 2026/27?
£20,000 across all your ISAs, of which up to £4,000 can go into a Lifetime ISA. From 6 April 2027, anyone under 65 can put no more than £12,000 of the £20,000 into cash ISAs.
How much can I pay into a pension in 2026/27?
The annual allowance is £60,000, or 100% of your UK earnings if lower. It tapers down to £10,000 for adjusted income over £260,000, and you can usually carry forward unused allowance from the previous three tax years.
What is the capital gains tax allowance for 2026/27?
The annual exempt amount is £3,000. Gains above it are taxed at 18% within your basic rate band and 24% above it. Transfers to a spouse or civil partner you live with are no gain, no loss.
Have dividend tax rates gone up?
Yes. From 6 April 2026 the ordinary rate is 10.75% and the upper rate 35.75%. The additional rate stays at 39.35%, and the dividend allowance remains £500. Dividends inside an ISA or pension are unaffected.
Can I keep my ISA if I move abroad?
Yes. It stays free of UK tax, but you cannot pay in while you are non-UK resident. Your new country may tax the income and gains inside it, so check the local rules before you move.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: The Individual Savings Account Regulations 1998 and Finance Act 2004, section 188, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us plan your international tax position
We plan your residence, timing, reliefs and treaty position, then handle the claims and returns that put it into effect. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ Residence status planned under the Statutory Residence Test
➜ Asset and gain timing around the residence line
➜ Treaty and double tax planning, including foreign tax credits
➜ Claims and returns filed, including treaty claims and the SA109
Typical fee
£1,000 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico