
Key points
If you were UK resident, foreign income has to be reported in the UK even if you paid tax on it abroad.
✓ Information about offshore income now reaches HMRC automatically, from several directions, so waiting it out is a poor strategy.
✓ HMRC can go back 12 years for non-deliberate offshore errors and 20 years for deliberate behaviour or failure to notify.
✓ Years up to 2015/16 not corrected by 30 September 2018 can carry Failure to Correct penalties of 100% to 200%.
✓ If HMRC writes to you about overseas income, check every year it covers before you reply.
✓ Non-residents can use the facility to correct years when they were UK resident.
If you are UK resident, HMRC taxes your worldwide income and gains: interest on an overseas bank account, rent from a property abroad, dividends on foreign shares, gains on crypto held on an overseas exchange. If some of that has never been declared, the Worldwide Disclosure Facility is how you put it right.
Paying tax in another country does not remove the need to report it in the UK. And since the remittance basis ended on 6 April 2025, leaving foreign income offshore no longer keeps it out of UK tax unless you make a valid claim, such as for the 📖 4-year FIG regime.
This guide explains who needs the facility, how HMRC finds offshore income, how far back a disclosure goes, the five-step process, and how offshore penalties are worked out.
Who needs the Worldwide Disclosure Facility?
It is for anyone disclosing a UK tax liability that relates wholly or partly to an offshore matter. HMRC defines that as unpaid tax on:
➜ Foreign income: income from a source outside the UK, such as overseas interest, rent, pensions or dividends.
➜ Foreign assets: gains on assets held outside the UK, such as a property abroad or shares held with a foreign broker.
➜ Overseas activities: activities carried on wholly or mainly outside the UK.
➜ Money moved abroad: funds connected to unpaid UK tax that have been transferred to, or are held in, another country.
You can use it as an individual, for your company or a trust, or on behalf of someone who has died. You can still use it if you are no longer UK resident, as long as the liability relates to years you were within the UK tax net. If you also have undeclared UK income, it goes in the same disclosure.
Where you have paid foreign tax on the income, you can usually claim foreign tax credit relief, so disclosure does not mean paying twice. See 📖 how double tax treaties work.
👉 HMRC guidance: make a disclosure using the Worldwide Disclosure Facility
How does HMRC find out about offshore income?
Why is waiting it out a poor strategy? Because the information now reaches HMRC automatically, from several directions:
➜ The Common Reporting Standard: over 100 countries exchange financial account data each year. Banks, brokers and insurers report account balances, interest, dividends, sale proceeds and the holder's tax residence.
➜ US accounts: FATCA gives HMRC similar data from US financial institutions.
➜ Crypto: under the Cryptoasset Reporting Framework, UK platforms have collected user and transaction data since 1 January 2026, with first reports to HMRC due by 31 May 2027. Other signed-up countries will exchange similar data.
➜ Letters from HMRC: HMRC writes to people it holds overseas data about, sometimes asking them to sign a certificate of tax position.
If you receive one of those letters and find you do owe tax, HMRC expects you to use this facility. Do not sign a certificate saying your affairs are in order unless you are sure they are.
👉 HMRC guidance: reporting cryptoasset user and transaction data (CARF)
How far back does HMRC go for offshore income?
Offshore matters have longer time limits than UK ones. HMRC can assess:

Image 1: offshore errors stay open longer
➜ Non-deliberate errors: up to 12 years. This applies from 2015/16 whether or not you took reasonable care, and to 2013/14 and 2014/15 if you were careless. A careless error in 2014/15 stays open until 5 April 2027.
➜ Deliberate behaviour: up to 20 years.
➜ Never telling HMRC: up to 20 years where you failed to notify HMRC that you had taxable income at all.
There is one limited exception. The 12-year limit does not apply if HMRC received overseas information, for example under the Common Reporting Standard, in time to have assessed the tax within the normal 4 or 6 years.
The facility currently covers tax years up to 2024/25. Income for 2025/26 goes on your 2025/26 tax return, due by 31 January 2027, and any outstanding return HMRC has issued from 2022/23 onwards must be filed rather than disclosed.
👉 HMRC manual: 12-year time limit for offshore matters (CH53510)
👉 The law: Taxes Management Act 1970, section 36A (offshore time limits)
Does the 2018 Requirement to Correct still matter?
Why do older years carry heavier penalties? Because anyone with offshore non-compliance for 2015/16 or earlier had to correct it by 30 September 2018. If you did not, and did not have a reasonable excuse, the Failure to Correct penalty applies to those years:
➜ Standard penalty: 200% of the tax, whatever your behaviour and wherever the income arose.
➜ Minimum penalty: 100% for a voluntary disclosure, or 150% if HMRC contacted you first.
➜ Possible extras: an asset moves penalty of 50% of the main penalty if assets were moved to avoid detection, and an asset-based penalty of up to 10% of the asset's value where more than £25,000 of tax is at stake in a year.
For 2016/17 onwards, the normal offshore penalty rules apply instead, as described below.
👉 HMRC guidance: Requirement to Correct tax due on offshore assets
👉 The law: Finance (No. 2) Act 2017, Schedule 18 (requirement to correct)
The five-step disclosure process
It is time-bound, so it pays to have records to hand before you start.
Notify HMRC. Tell HMRC through the Digital Disclosure Service that you intend to disclose. HMRC sends a disclosure reference number and a payment reference number. Each person needs their own disclosure, so a married couple with a joint account make two.
Calculate. You have 90 days from HMRC's acknowledgement to work out the tax, interest and penalty for each year. Complex cases can ask for another 90 days, making 180 in total. Interest runs daily from when each amount was due, at the Bank of England base rate plus 4%.
Prepare the disclosure. Self-assess your behaviour for each year, describe the income and gains, and give the maximum value of your overseas assets at any point in the last five years. You will also be asked about anyone who helped you hold assets offshore.
Pay. Full payment is due on the day you submit. If you cannot pay in full, contact the Offshore Disclosure Facility helpdesk before you submit to agree an arrangement.
HMRC's response. HMRC aims to acknowledge the disclosure within 15 days and write with its intended course of action within 90 days of that, although it warns of delays. It may ask for evidence before accepting.
How are offshore penalties worked out?
Offshore penalties depend on three things: your behaviour, whether HMRC prompted you, and the category of the territory where the income or gain arose.
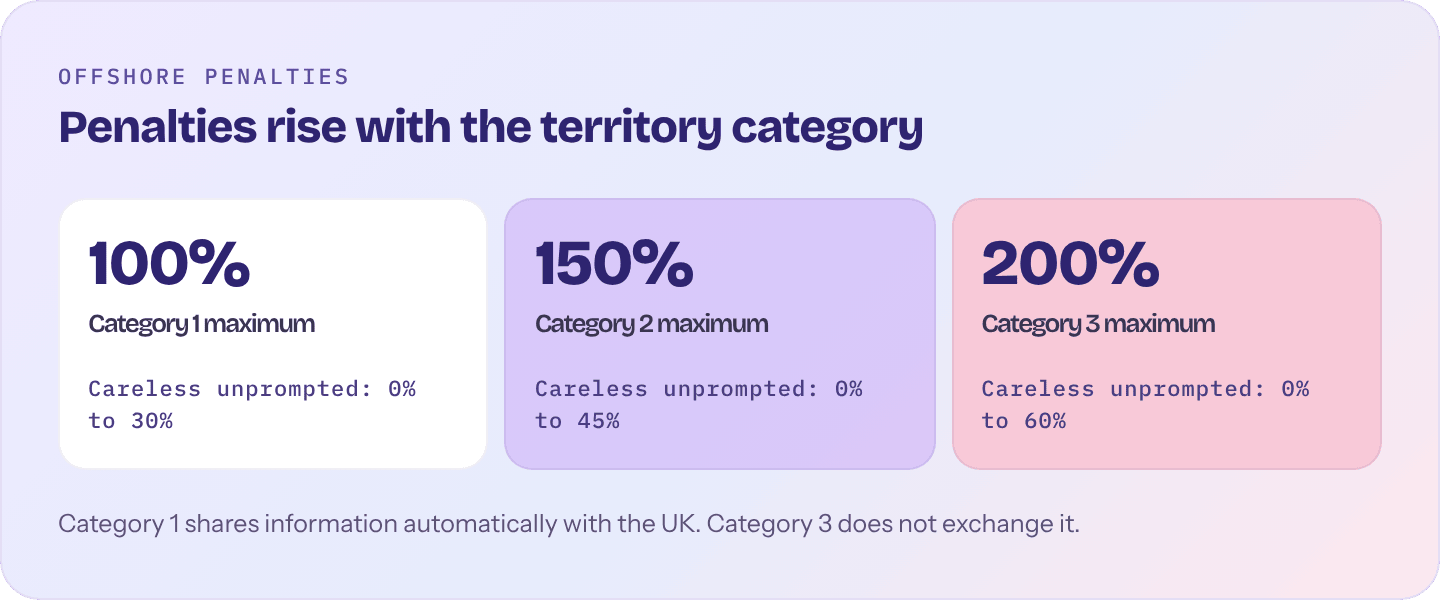
Image 2: territory categories and penalty ranges
➜ Category 1: territories that share information automatically with the UK, including most of the EU. Maximum penalty 100% of the tax.
➜ Category 2: any territory not listed in category 1 or 3. Maximum penalty 150%.
➜ Category 3: territories that do not exchange information with the UK. Maximum penalty 200%.
For an unprompted disclosure of a careless error, the range is 0% to 30% in category 1, 0% to 45% in category 2 and 0% to 60% in category 3. Deliberate behaviour carries much higher minimums, and HMRC's list of territories should always be checked for the year concerned.
Where you land in the range depends on the quality of your disclosure: telling, helping and giving access, plus the extra information HMRC asks for about enablers and asset holders. If you took more than three years to come forward, HMRC usually will not reduce the penalty below the minimum of the range plus 10 percentage points.
👉 HMRC factsheet CC/FS17: penalties for offshore non-compliance
👉 The law: Finance Act 2007, Schedule 24, paragraph 4A (offshore penalty categories)
👉 HMRC list: territory categorisation for offshore penalties
👉 The law: The Penalties, Offshore Income etc. (Designation of Territories) Order 2011
Worked example: A forgotten overseas account
Lena moved to the UK in 2017 and kept her Australian savings account. It has paid about £3,000 of interest a year since 2018/19, and she never declared it.
She is a higher-rate taxpayer, so UK tax is 40% on the interest above her £500 personal savings allowance: £1,000 a year.
Australia withheld 10%, or £300 a year, which she claims as foreign tax credit relief. That leaves £700 of UK tax a year.
Her careless disclosure covers 2018/19 to 2024/25: seven years, £4,900 of tax. Australia is a category 1 territory, so the range is 0% to 30%, restricted to at least 10% because she took more than three years. Her penalty is about £490, plus interest.
Why disclose before HMRC contacts you?
An unprompted disclosure gives you:
➜ Lower minimum penalties: the floor is lower in every territory category when HMRC has not prompted you.
➜ No publication: HMRC will not publish your details if your disclosure is complete and accurate and you co-operate.
➜ A civil route: HMRC reserves criminal investigation for serious cases, and a full voluntary disclosure weighs heavily against it.
➜ Certainty: once HMRC accepts, the years covered are settled.
If you would rather have a specialist prepare the disclosure with you, see our Worldwide Disclosure Facility service.
Going forward, report foreign income on the SA106 foreign pages of your return. If you have recently arrived in the UK, check whether a 📖 FIG regime claim is available before assuming foreign income is taxable. Former remittance basis users should also look at the 📖 Temporary Repatriation Facility, which is a separate relief rather than a disclosure route.
Frequently asked questions
What is the Worldwide Disclosure Facility?
It is HMRC's route for disclosing unpaid UK tax that relates wholly or partly to offshore income, gains or assets. You notify HMRC, then have 90 days to calculate and disclose the tax, interest and penalties and pay what you owe.
How far back will HMRC go for undeclared foreign income?
Up to 12 years for non-deliberate offshore errors, and up to 20 years where the behaviour was deliberate or you never notified HMRC. Years up to 2015/16 not corrected by 30 September 2018 can also carry Failure to Correct penalties of 100% to 200%.
I paid tax abroad. Do I still need to tell HMRC?
Yes, if you were UK resident. Foreign tax does not remove the UK reporting obligation. You can usually claim credit for the foreign tax against the UK tax on the same income, so the UK only collects any difference.
What should I do if HMRC writes to me about overseas income?
Check your affairs for every year the letter could cover before replying. If you owe tax, HMRC expects a disclosure through the Worldwide Disclosure Facility. Do not sign a certificate of tax position unless you are sure it is accurate.
Can I use the Worldwide Disclosure Facility if I have left the UK?
Yes. HMRC confirms non-residents can use the facility if they meet the eligibility criteria, for example to correct offshore income from years when they were UK resident.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Finance Act 2007, Schedule 24 and Taxes Management Act 1970, section 36A, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us handle your offshore disclosure
We identify the accounts and years in scope, apply foreign tax credits and treaty relief, and register, file and settle with HMRC. Every disclosure is prepared and signed off by Emma McDermott, ATT.
➜ Accounts and years identified
➜ Foreign tax credits and treaty relief applied
➜ Registered, filed and settled with HMRC
➜ Payment plans may be available for larger cases
Typical fee
£5,000 to £15,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico