
Key points
If you live abroad, you usually need a UK tax return when you still have UK income such as rent, or when you moved during the year and need to claim split-year treatment.
✓ Non-residents with UK rental income must file, even if the letting agent pays the rent gross.
✓ Non-residents whose only UK income is bank interest or dividends usually do not need a return unless HMRC asks.
✓ HMRC's free online service cannot file the SA109 residence pages, so non-residents and split year claimants file on paper or use commercial software.
✓ For 2025/26, the paper deadline of 31 October 2026 has passed, so returns now go online by 31 January 2027.
✓ If HMRC sends you a notice to file, you must file by the deadline, even if you owe nothing.
Living abroad does not take you out of the UK tax system. If you still have UK income, such as rent from a UK flat, or you moved into or out of the UK during the year, you will usually need to file a UK tax return, and filing it from abroad works differently.
This guide covers the 2025/26 tax year (6 April 2025 to 5 April 2026). The return is due online by 31 January 2027, and the paper deadline of 31 October 2026 has already passed. If you need to file for the first time and missed the 5 October 2026 registration date, register now.
HMRC will not always know your circumstances have changed. Working out whether you need to file is your responsibility, not theirs.
Global Tax Consulting, founded by Emma McDermott ATT, prepares UK tax returns for people living abroad, with fees from £750 fixed before work starts. See our UK tax returns for non-residents.
What is a Self Assessment tax return?
A tax return reports income and gains that have not already been taxed correctly at source, claims any reliefs you are entitled to, and calculates the balance you owe or the refund you are due.
The main return is the SA100. You add supplementary pages for the income you have, such as SA103 for self-employment, SA105 for UK property, SA106 for foreign income, SA108 for capital gains and SA109 for residence. The last one matters for anyone who has moved into or out of the UK.
One rule overrides everything else in this guide. If HMRC sends you a notice to file, you must file by the deadline on the notice, even if you owe nothing. If you think you should not be in the system, ask HMRC to withdraw the notice rather than ignoring it.
👉 HMRC guidance: Self Assessment tax returns
👉 The law: Taxes Management Act 1970, section 8 (personal return)
Do you need to file a UK tax return if you live abroad?
So many internationally mobile people end up in Self Assessment because residence changes almost always need a return to claim the right treatment, and HMRC's PAYE system cannot do it for you.

Image 1: the common filing triggers
If you are UK resident
➜ Foreign income or gains. Since 6 April 2025 the remittance basis has gone, so UK residents are taxed on foreign income and gains as they arise. That income goes on the return, with credit for foreign tax.
➜ The FIG regime. New arrivals who were non-resident for 10 consecutive years can claim four years of relief on foreign income and gains, but only through the return. See our guide to the 📖 4-year FIG regime.
➜ The Temporary Repatriation Facility. Former remittance basis users designate old offshore income and gains on the return. See our guide to the 📖 Temporary Repatriation Facility.
➜ Arriving part-way through the year. Split-year treatment has to be claimed on the SA109 residence pages.
➜ Returning within five years. Coming back after a short period abroad can bring gains and some income from the non-resident years into charge. See our guide to the 📖 temporary non-residence rules.
If you are non-resident
➜ UK rental income. You must file even if your letting agent pays you gross under the non-resident landlord scheme. Gross payment only defers the tax to the return. See our guide to the 📖 non-resident landlord scheme.
➜ Leaving part-way through the year. Most leavers are owed a refund of PAYE, and split-year treatment is claimed on the SA109. See our guide to 📖 split-year treatment.
➜ UK workdays. Salary for work physically done in the UK stays taxable here. See 📖 working remotely abroad for a UK company.
➜ Selling UK property. Non-residents must report every disposal of UK land or property within 60 days, even where no tax is due, and include it on the return if they file one. See our guide to 📖 non-resident capital gains tax.
If your only UK income as a non-resident is bank interest or dividends, that income is usually disregarded income, which caps your UK tax on it, and you will not normally need a return for it alone unless HMRC asks. See our guide to 📖 disregarded income and our overview of 📖 what the UK taxes once you have left.
👉 HMRC guidance: Tax on your UK income if you live abroad
👉 The law: Income Tax Act 2007, section 811 (limit on liability of non-residents)
What to include on a UK tax return from abroad
Every return starts with the SA100. A return filed from abroad usually also needs some of these supplementary pages:
Page | When you need it |
|---|---|
SA109 Residence and FIG regime | You are non-resident, you moved during the year, you claim the personal allowance as a non-resident, or you claim the FIG regime |
SA105 UK property | You have UK rental income, including rent paid gross under the non-resident landlord scheme |
SA102 Employment | You had a UK job for part of the year, or worked days in the UK after you left |
SA106 Foreign | You had foreign income while UK resident, or you are claiming foreign tax credit relief |
SA108 Capital gains | You sold UK property or other assets, even if you also filed a 60-day UK property return |
The SA109 is the page that changes how you file. HMRC’s free online service does not support it, so a return with the SA109 has to go on paper by 31 October or online through commercial software by 31 January. For 2025/26 the paper deadline has passed, so the online route is the one left.
The SA109 is also where non-residents claim the UK personal allowance if they qualify, for example as a British citizen, and where you record a split-year claim.
👉 HMRC form: SA109 Residence and foreign income and gains (FIG) regime pages
Claiming split-year treatment from abroad
In the year you leave or arrive, you are UK resident for the whole tax year unless one of the split-year cases applies. If one does, the year is split into a UK part and an overseas part, and most foreign income in the overseas part falls outside UK tax.
Split-year treatment applies if you meet one of the cases, but you still have to show it on the SA109, with the date you left or arrived and the case that applies. Miss a condition and the whole year stays UK resident. See our guide to 📖 split-year treatment.
👉 The law: Finance Act 2013, Schedule 45, Part 3 (split year treatment)
Worked example: Daniel moves to Lisbon
Daniel moved to Lisbon in August 2025 to start a new job, and kept renting out his flat in Leeds. Until he left, he was employed in the UK under PAYE.
Detail | What it means for Daniel |
|---|---|
Tax year | 2025/26 (6 April 2025 to 5 April 2026) |
Pages needed | SA100, SA102 for his UK job, SA105 for the Leeds rent and SA109 for split-year treatment |
Split-year treatment | Shown on the SA109, if he meets every condition of a case, such as starting full-time work overseas |
How to file | Online through commercial software or an adviser, because HMRC’s free service cannot take the SA109 |
Deadline | 31 January 2027, which is also when any tax is due |
Daniel cannot use HMRC’s free online return, and the paper deadline for 2025/26 passed on 31 October 2026. The £100 late filing penalty applies after 31 January 2027 even if he is owed a refund.
👉 HMRC guidance: RDR3 Statutory Residence Test, including split year treatment
Who must file a UK tax return?
For 2025/26, you need a return if any of the following applied in the tax year:
➜ Self-employment: you were a sole trader with gross income over £1,000, before expenses.
➜ Partnerships: you were a partner in a business partnership.
➜ Capital Gains Tax: you had CGT to pay, and did not report it through HMRC's real-time CGT service.
➜ High Income Child Benefit Charge: you owe the charge and do not pay it through your tax code.
➜ Off-payroll work: you are an off-payroll worker repaying a student or postgraduate loan.
You will also usually need a return if you had untaxed income that cannot be collected another way. In practice that means:
➜ Rental income: from UK or overseas property, after the £1,000 property allowance.
➜ Untaxed income of £2,500 or more: such as tips, commission or casual work paid gross.
➜ Dividends over £10,000: smaller amounts above your allowances can usually go through your tax code instead.
➜ Pension annual allowance charge: if contributions exceeded your allowance, the charge is reported on a return.
➜ Employment expenses over £2,500: claims above this level go through Self Assessment rather than a simple claim.
👉 HMRC guidance: Who must send a tax return
👉 The law: Taxes Management Act 1970, section 7 (notice of liability to tax)
When you do not need to file
Several recent changes mean fewer people need a return than before:
➜ High earners taxed only through PAYE. The old rule that PAYE earners over £100,000, and later £150,000, had to file was removed from 2024/25. If all your income is taxed through PAYE and nothing else on this page applies, you do not need a return.
➜ High Income Child Benefit Charge. Since autumn 2025, employed people whose only reason for filing is the charge can leave Self Assessment and pay it through their tax code instead.
➜ Small amounts of untaxed income. Below £2,500, HMRC can usually collect the tax through your tax code. Tell HMRC between the end of the tax year and 5 October.
➜ Gains, if you are UK resident. The real-time CGT service lets you report and pay without registering for Self Assessment.
If you are already registered and no longer need to file, tell HMRC. Until you do, they will keep issuing notices, and late filing penalties follow each one.
👉 HMRC guidance: If you no longer need to send a tax return
👉 The law: Taxes Management Act 1970, section 8B (withdrawal of notice to file)
How to register for Self Assessment
You register with HMRC by 5 October after the end of the tax year in which you first needed to file.
For example, if you started letting a flat in May 2025, that income falls in the 2025/26 tax year, so you must register by 5 October 2026. HMRC then issues your Unique Taxpayer Reference (UTR), a ten-digit number that stays with you for life. The activation letter goes by post, so leave time if you are overseas.
Register late and you may face a failure to notify penalty if the tax is not paid by 31 January. It is based on the tax left unpaid, so registering on time matters most when there is tax to pay.
👉 HMRC guidance: Register for Self Assessment
👉 The law: Finance Act 2008, Schedule 41 (failure to notify penalties)
Non-residents without a UK address or National Insurance number often struggle with online registration. Our guide to 📖 HMRC forms for expats covers the paper route.
Self Assessment deadlines for 2025/26
The UK tax year runs from 6 April to 5 April. For the 2025/26 year, the key dates are:
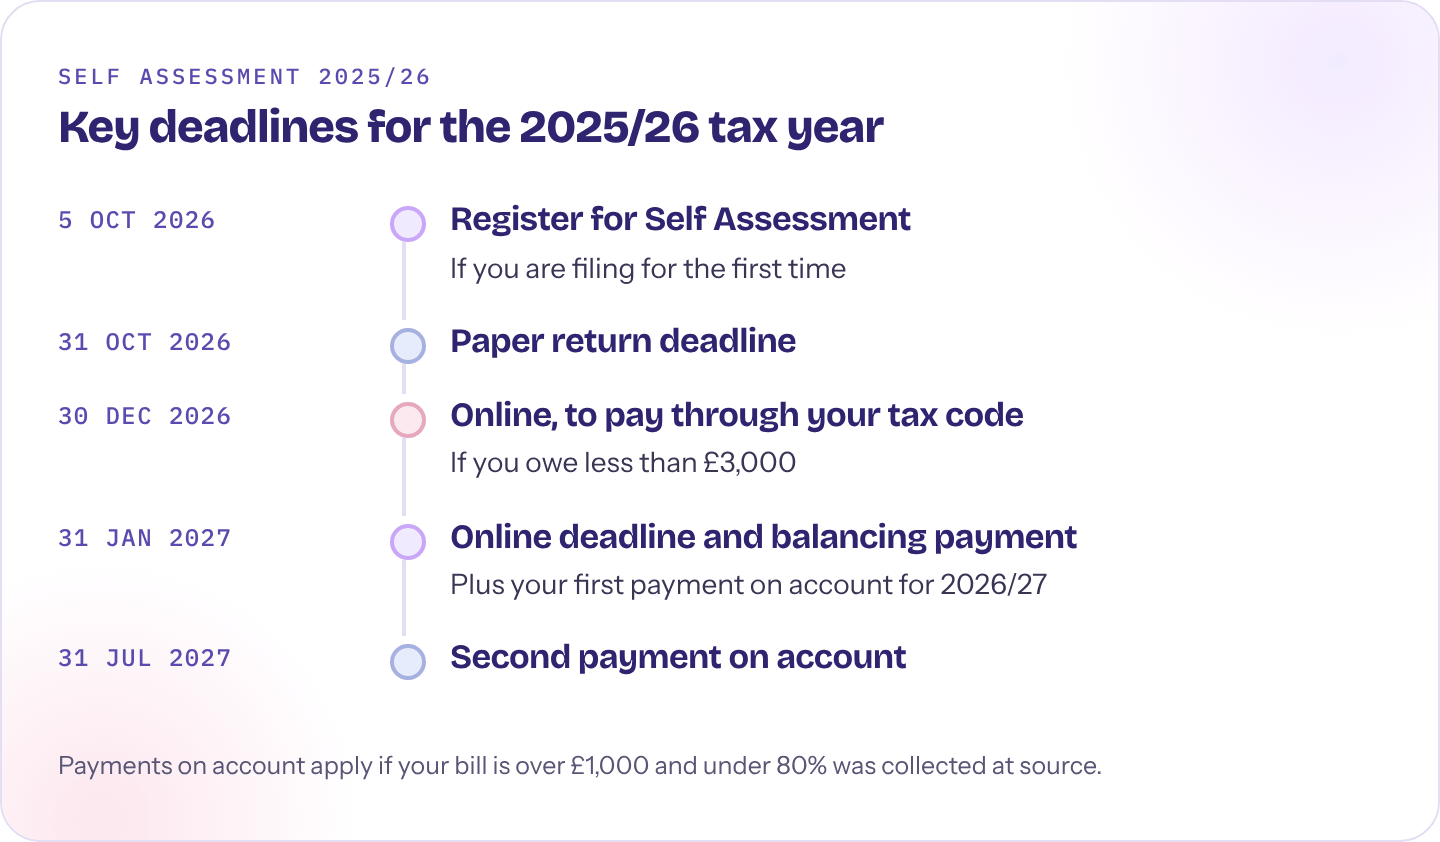
Image 2: 2025/26 deadlines and what lateness costs
➜ 5 October 2026: register for Self Assessment if you are filing for the first time.
➜ 31 October 2026: file a paper return.
➜ 30 December 2026: file online by this date if you owe less than £3,000 and want it collected through your tax code.
➜ 31 January 2027: file online, and pay the balance for 2025/26 plus your first payment on account for 2026/27.
➜ 31 July 2027: pay your second payment on account.
Worked example: The first-year bill
Payments on account catch out most new filers. If your bill is over £1,000 and less than 80% of your tax was collected at source, HMRC asks for two advance payments towards next year, each half of this year's bill. Sam starts letting a flat in 2025/26 and owes £4,000 on the rental profit.
Detail | Figure |
|---|---|
Tax on the 2025/26 rental profit | £4,000 |
First payment on account for 2026/27 | £2,000 |
Second payment on account, due 31 July 2027 | £2,000 |
Due on 31 January 2027 | £6,000 |
That is £6,000 due in January rather than the £4,000 Sam expected. If income is falling, you can apply to reduce payments on account, but interest applies if you reduce them too far.
👉 HMRC guidance: Understand your Self Assessment tax bill
👉 The law: Taxes Management Act 1970, section 59A (payments on account)
What happens if you file or pay late?
Late filing penalties are automatic and apply even if you owe no tax at all:
➜ 1 day late: a £100 penalty.
➜ 3 months late: £10 a day for up to 90 days, a maximum of £900.
➜ 6 months late: 5% of the tax due or £300, whichever is greater.
➜ 12 months late: another 5% or £300, whichever is greater.
Paying late is charged separately: 5% of the unpaid tax at 30 days, 6 months and 12 months. Interest runs on top from the day after the due date, at the Bank of England base rate plus 4%.
If you had a reasonable excuse, such as serious illness, you can appeal. It is far easier to file on time and agree a payment plan if you cannot pay in full.
👉 HMRC guidance: Self Assessment penalties
👉 The law: Finance Act 2009, Schedule 55 (late filing penalties)
Making Tax Digital: what changed from April 2026
From 6 April 2026, sole traders and landlords must keep digital records and send HMRC quarterly updates if their qualifying income is over the threshold. Qualifying income is gross self-employment and property income before expenses:
➜ From April 2026: qualifying income over £50,000 on your 2024/25 return.
➜ From April 2027: over £30,000 on your 2025/26 return.
➜ From April 2028: over £20,000.
You still finalise the year after it ends, and other income such as salary, dividends and gains goes into that year-end submission. For jointly owned property, only your share of the rent counts towards the threshold.
Non-residents get breathing space. If you filed the SA109 residence pages for 2024/25 and expect to file them for 2026/27, you are automatically exempt until April 2027 at the earliest. Anyone without a National Insurance number is exempt too.
👉 HMRC guidance: Exemptions from Making Tax Digital for Income Tax
How to file your tax return
If your affairs are straightforward, HMRC's free online service works well. You sign in through your personal tax account or Government Gateway.
There is one significant gap. HMRC's online service cannot file the SA109 residence pages, which every non-resident and every split-year claimant needs. You can either file the whole return on paper, with the earlier 31 October deadline, or buy commercial software that supports SA109 and file online by 31 January. You cannot mix the two. The third option is to have an adviser file it for you, which is what our UK tax return service for expats is for.
👉 HMRC guidance: File your Self Assessment tax return online
👉 HMRC list: Self Assessment commercial software suppliers
Keep your records. HMRC expects you to keep them for at least 22 months after the end of the tax year, or 5 years after the 31 January deadline if you are self-employed or a landlord. For cross-border returns, that includes travel records supporting your residence position.
Getting your return filed from abroad
Our UK tax returns for non-residents service prepares and files the full return for you, SA109 included, wherever you live. Fees range from £750 to £5,000 depending on how many income and gain sources you have, and are fixed before we start. Every return is reviewed and signed off by Emma McDermott ATT.
Frequently asked questions
Do I need to file a UK tax return if I live abroad?
Often, yes. It depends on your UK income, not on where you live. You usually need to file if you have UK rental income, UK self-employment income or a UK pension that is not fully taxed, if you are reclaiming overpaid UK tax, or if you are claiming split-year treatment or non-resident status. Non-residents file the SA109 residence pages, which HMRC's own free online service does not support.
Do I need to file a tax return if I am only employed?
Usually not. If all your income is taxed through PAYE, you do not need a return, whatever you earn. You will still need one if you have other untaxed income, gains to report, or HMRC sends you a notice to file.
What is the deadline to register for Self Assessment for 2025/26?
5 October 2026. You need to register by then if you are filing for the first time, or if you did not need to file for 2024/25. HMRC will then send you a Unique Taxpayer Reference.
Do I have to file if I do not owe any tax?
Yes, if HMRC has sent you a notice to file. The £100 late filing penalty applies even when no tax is due. If you no longer need to be in Self Assessment, ask HMRC to withdraw the notice instead.
Can I file the SA109 residence pages online with HMRC?
No. HMRC's free online service does not support SA109. Non-residents and split-year claimants either file a paper return by 31 October or use commercial software to file online by 31 January.
What is the deadline for a UK tax return if I live abroad?
The same dates apply wherever you live: 31 October for a paper return and 31 January for an online return, after the end of the tax year. For 2025/26 that is 31 January 2027 online. Because HMRC’s free online service cannot take the SA109, most people filing from abroad use commercial software or an adviser.
Do I need to file a UK tax return in the year I leave the UK?
Often, yes. If you left part-way through the year and want split-year treatment, it has to be shown on the SA109 with your leaving date and the case that applies. If you have no other reason to file and HMRC has not asked you to, form P85 may be enough to reclaim PAYE overpaid on your salary.
Last reviewed on 11 November 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Taxes Management Act 1970, section 8 and Taxes Management Act 1970, section 7, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us prepare and file your UK return
We prepare and file your Self Assessment return, including the SA109 residence pages, and make the claims and reliefs you are entitled to. Every return is prepared and signed off by Emma McDermott, ATT.
➜ Return prepared and filed, including the SA109 residence pages
➜ Rental, employment and investment income, plus foreign income and credits
➜ Treaty claims and reliefs made, including foreign tax credits and split-year claims
➜ PAYE refunds claimed for duties abroad, this year and up to four earlier years
Typical fee
£750 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 245 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico