
When you decide to leave the UK, your focus is likely on the logistics. Finding a home, arranging visas, perhaps learning a language. The tax implications of your departure matter just as much. A common misconception is that once you physically leave and become non-resident, your relationship with HMRC ends immediately.
In reality the UK operates a source-based system for non-residents. Your foreign income and gains fall outside the UK net, but HMRC keeps the right to tax income that originates in the UK. Understanding what counts as UK-sourced income is the foundation of effective exit planning.
This article sets out how each income stream is treated once you are non-resident, and how to manage the compliance that goes with it.
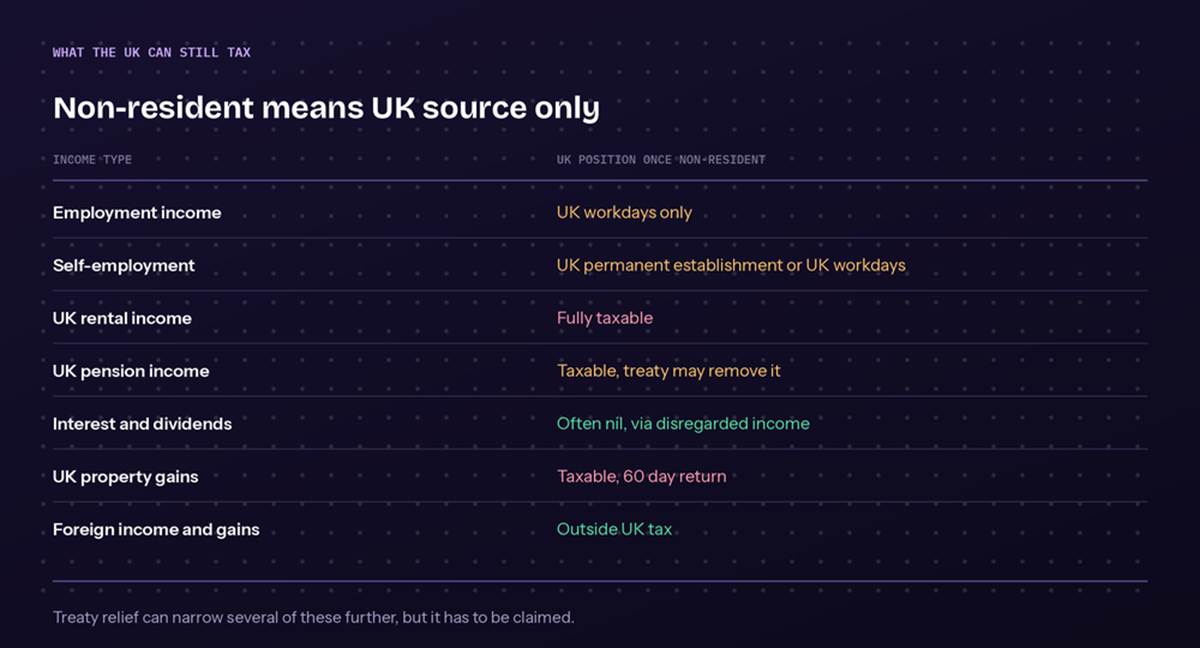
Image 1 — what stays within UK scope
Employment income
If you continue working after moving abroad, the source of employment income is decided by where you are physically located when you perform the work. It is not decided by where the employer is based or where the salary is paid.
As a non-resident you are liable to UK tax only on the portion relating to duties physically performed in the UK.
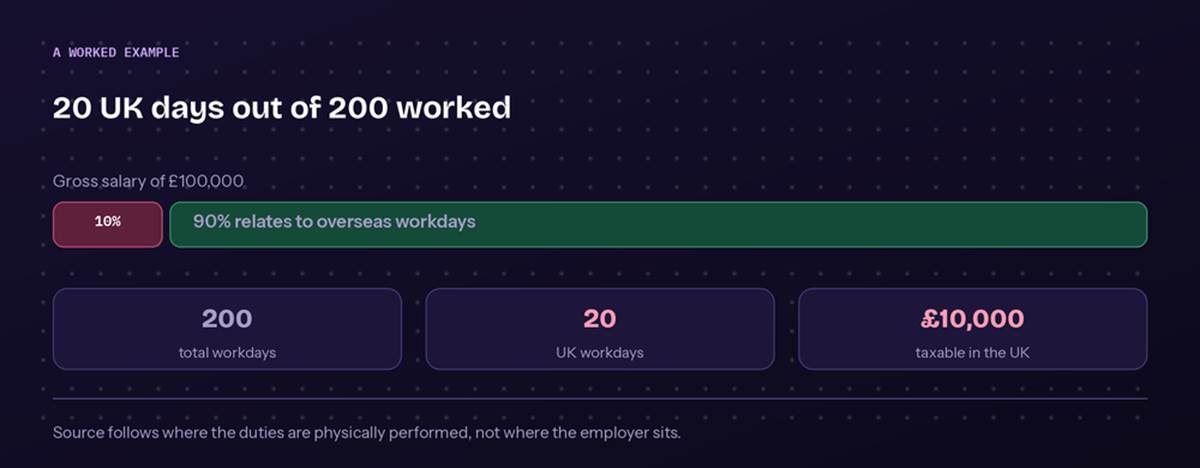
Image 2 — how the apportionment works
On a gross salary of £100,000, with 200 total workdays in the year of which 20 are in the UK, HMRC is entitled to tax 10% of the earnings, being £10,000.
If you are employed by an overseas company and resident for tax purposes overseas, you may be able to go further and remove the UK’s right to tax even that UK portion, through the relevant double taxation agreement.
Self-employment and business profits
For the self-employed, the source test shifts toward the concept of a permanent establishment, alongside the location of physical work. The UK will seek to tax your business profits only where they are generated through a permanent establishment in the UK, or through work physically performed on UK soil.
● With a UK permanent establishment. Where you have a physical business presence in the UK, you are liable on the profits associated with it.
● As a digital business. If you run the business wholly online, you are liable on the portion of profits relating to work physically performed in the UK. As with employment income, a treaty may remove even that.
● With no UK presence at all. If there is no permanent establishment and you work wholly overseas, there is no UK exposure.
UK rental income
One of the most common forms of UK-sourced income for expats is rent from a former family home or an investment property. Rental income remains fully taxable in the UK whatever your residence status.
As a non-resident landlord the starting point is that your letting agent, or your tenant where there is no agent and the rent exceeds £100 a week, withholds basic rate tax from the payments. You can apply to HMRC to receive the rent gross instead by registering under the Non-Resident Landlord Scheme.
Pension income
The starting point for UK pension income is that it is taxable in the UK.
However, depending on the type of pension and the country you retire to, it may be possible to remove the UK’s right to tax it entirely. Many treaties give the sole taxing right over private pensions to the country of residence, which leaves the UK unable to tax the income at all.
Note that government service pensions usually work the other way, remaining taxable only in the country that pays them.
Investment income: interest and dividends
For interest and dividends, the rules offer non-residents a useful degree of flexibility. The starting point is that these are UK-sourced and taxable, but many expats can reduce or remove the liability.
● Disregarded income. For many non-residents, UK tax on investment income is limited to the tax deducted at source. Where nothing was deducted, the liability is effectively nil, which means you can receive substantial UK investment income without a UK charge.
● Treaty relief. Alternatively, a treaty may limit the UK’s taxing right to a set percentage, often 5%, 10% or 15%, or remove it altogether.
⚠️ WARNING The disregarded income basis is not free. Where it produces the lower bill, you give up your UK personal allowance for that tax year, which means any other UK income, such as rental profit, is taxed from the first pound. Where you have both, the calculation needs running both ways before you rely on it.
UK property gains
Selling UK property as a non-resident also remains within UK scope. A capital gains tax return must be filed, and any tax paid, within 60 days of completion. That applies even where the disposal produces no gain, or a loss.
Rebasing to April 2015 often removes a substantial part of the gain for properties owned before that date, but the return is still required.
Retaining the personal allowance
A key part of exit planning is working out whether you keep the UK personal allowance. Contrary to common belief, you do not lose it automatically by moving abroad.
If you are a UK or EEA national you continue to qualify while non-resident. If you are neither, you may still qualify under a double taxation agreement.
🌎 UKs network of double taxation agreements
The five year trap: temporary non-residence
As part of your planning you need to be aware of the temporary non-residence rules, which apply if you return to the UK within five years.
They exist to stop people leaving the UK for a short period to realise income or gains free of tax. Where triggered, income and gains that escaped tax while you were abroad come back into charge in the year you return. In effect the charge is deferred rather than avoided.
If you are planning to be overseas for up to five years, plan carefully to avoid an unexpected bill on repatriation.
HMRC guidance on temporary non-resident rules
Compliance and reporting
Exit planning only works if the compliance follows. To achieve a clean break and manage your ongoing UK position, consider the following.
● Form P85. If you are leaving and will no longer file a self assessment return, for example because you have no rental income, submit form P85. It notifies HMRC of your departure and lets you reclaim tax overpaid on employment income in the year you leave. You can file P85 form
● Treaty relief form. To restrict UK tax on pension or investment income under a treaty, you usually submit a specific form, certified by the tax authority in your new country of residence. You can file treaty relief form
● Self assessment. A return is required if you receive UK rental income. You may also need to file to claim the disregarded income basis, or to reclaim tax withheld at source on other UK income. You can register for self-assessment
● Non-resident landlord registration. To register as an overseas landlord and apply for your rental income to be paid gross. You can register as a non-resident landlord
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated