
If you live abroad, leave the UK, move to the UK, or work internationally, the correct HMRC form depends on your residence status, income sources and personal circumstances.
Using the wrong form can delay a repayment, leave rental income incorrectly taxed, or result in an incomplete self assessment return. Using the right one helps you report your position clearly and claim the reliefs you are entitled to.
This guide summarises the most important HMRC forms for expats, non-residents, digital nomads and other internationally mobile individuals. It explains when each is used and links to the official GOV.UK page.
HMRC forms and guidance are updated regularly. Always use the version for the relevant tax year, and check whether your circumstances warrant professional advice before you file.
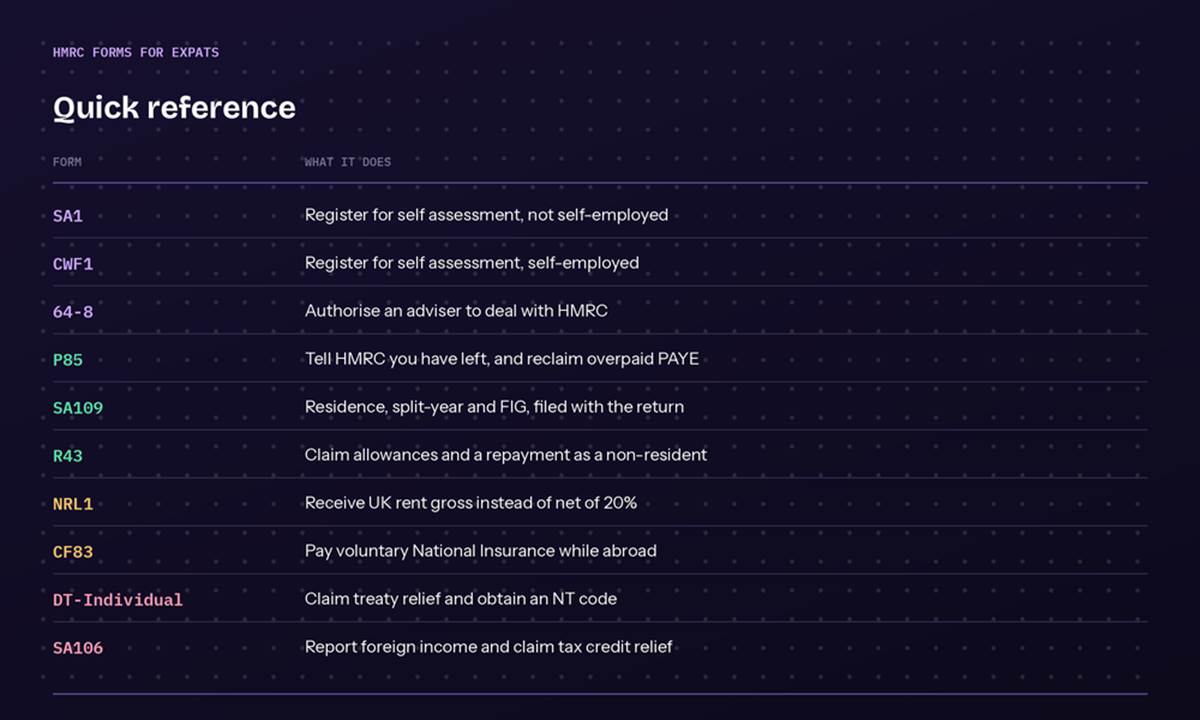
Image 1 — quick reference
Registration and authorisation
SA1: register for self assessment if you are not self-employed
SA1 registers you for self assessment where you are not self-employed. You may need it if:
● You are an employee with foreign income that must be reported.
● You are UK resident with overseas dividends, interest, pensions, rental income or gains.
● You are non-resident with UK income that cannot be dealt with entirely through PAYE.
● You need to claim a relief or make a disclosure through a tax return.
You normally use SA1 when you do not already have a Unique Taxpayer Reference. After registering, HMRC issues your UTR and explains how to file.
📄 HMRC SA1 registration for non-self-employed
CWF1: register for self assessment if you are self-employed
If you are registering because you have started self-employment, CWF1 is the correct form rather than SA1. It registers you both for self assessment and for Class 2 National Insurance.
📄 HMRC CWF1 registration for self-employed
64-8: authorise an agent
Form 64-8 authorises a professional adviser to deal with HMRC on your behalf. You may use it if you want an adviser to:
● Discuss your self assessment position with HMRC.
● Submit tax returns for you.
● Handle correspondence about PAYE, repayments or liabilities.
● View relevant HMRC information, such as your UTR and previous returns.
You must complete, sign and date it before sending it to HMRC. Note that 64-8 is no longer accepted for limited authorisation requests, so if you only want an adviser to discuss a specific issue or help with one form, HMRC requires a separate written authority.
Leaving the UK and becoming non-resident
P85: get your income tax right if you are leaving
P85 is used when you leave the UK to live or work abroad and want HMRC to update your position. You may use it if:
● You are leaving permanently or for a substantial period.
● You have been employed under PAYE.
● You are not normally required to file a self assessment return for the departure year.
● You may have overpaid UK income tax and want a repayment.
If you are already required to file self assessment, you will generally report your residence position through the SA109 pages instead. Depending on your circumstances you may need both.
SA109: residence, split-year treatment and the FIG regime
SA109 is the supplementary page used with the SA100 return to report your residence position. You may need it if you:
● Leave or arrive in the UK during a tax year.
● Need to claim split-year treatment.
● Are UK resident, non-resident or dual resident.
● Need to report certain residence and domicile information.
● Want to claim relief under the foreign income and gains regime.
● Need to claim personal allowances as a non-UK resident.
Your position under the Statutory Residence Test is central to completing SA109 correctly. Days spent in the UK, available accommodation, work patterns, family connections and other ties may all be relevant.
⚠️ WARNING HMRC’s own free online filing service cannot submit the SA109. If you need the residence pages, and almost every expat does, you will need commercial software or an adviser. This is the single most common reason people find they cannot file their own return after moving abroad.
UK property income and disposals
NRL1: individual non-resident landlords
NRL1 is used by an individual living outside the UK who receives UK rental income. It applies for approval to receive rent without basic rate tax being deducted by your letting agent or tenant, which helps with cash flow where you intend to report the income through self assessment.
It is relevant if you own a UK property and live abroad, your agent or tenant is deducting tax under the scheme, and you want HMRC approval to receive rent gross.
Approval does not remove your obligation to report the rental income. You will still need a return including the SA105 property pages.
The 60 day property disposal return
If you are non-resident and dispose of UK land or property, you must report the disposal and pay any tax within 60 days of completion. This is a standalone online return, separate from self assessment, and it is required even where no tax is due or the disposal produces a loss.
⚠️ WARNING This one is not a form with a memorable number, which is part of why it gets missed. The 60 days runs from completion, not exchange, and the penalty regime applies whether or not there is tax to pay.
📄 Register for capital gains tax account
National Insurance while abroad
CF83: voluntary National Insurance contributions
CF83 applies to pay voluntary UK National Insurance for periods when you live or work abroad. You may consider it if you want to fill gaps in your record, protect your entitlement to the UK state pension, or establish which class of contribution is available to you.
Treaty relief and double taxation
DT-Individual: double taxation treaty relief
DT-Individual is used by individuals living in a country with a double taxation treaty with the UK. You may use it to apply for relief at source from UK income tax, claim a repayment, or claim treaty relief on certain UK-source income.
In practice this is the form that produces an NT code, which tells your pension provider to stop deducting UK tax. Some countries have their own tailored version, so search for a country-specific form before using the general one.
Treaty relief is not automatic. You must consider the specific treaty, the type of income, your residence under that treaty, and whether the other country also taxes the income.
Certificate of residence
Where you are UK resident and need to prove it to an overseas tax authority, you can ask HMRC for a certificate of residence. Moving the other way, the tax authority in your new country usually needs to certify your residence before HMRC will accept a treaty claim.
HS304: non-residents’ relief under double taxation agreements
HS304 is a self assessment helpsheet rather than a standalone claim form. It explains how non-residents may claim relief under a treaty when reporting UK income, and is useful if you receive UK pension, investment or employment income while resident overseas.
🌎
Foreign income and gains
SA106: foreign pages
SA106 is the supplementary section for foreign income and gains within a self assessment return. You may need it if you have overseas bank interest, foreign dividends, overseas rental income, foreign pensions, foreign employment income, other reportable foreign income, or foreign tax for which you want to claim credit relief.
If you are UK resident, foreign income may be taxable in the UK even if you leave it overseas. Your residence status, the type of income, the timing and any available reliefs must all be considered.
That is why the question of whether you need to file cannot be answered by looking at where your bank account is. If you are UK resident with reportable foreign income, you may need to file.
You may also need SA106 when making certain claims under the FIG regime. The interaction between SA106, SA109, foreign tax credit relief and treaty provisions can be technical.
Putting things right
The Worldwide Disclosure Facility
The Worldwide Disclosure Facility is HMRC’s digital route for disclosing previously undeclared offshore income, gains or assets. You may consider it if you have historic irregularities involving overseas bank accounts, foreign rental income, offshore investments, foreign pensions or trusts, or any income that should have been reported.
A disclosure may involve unpaid tax, interest and penalties. Establish the facts and calculate the liabilities before submitting anything.
🌎 Worldwide Disclosure Facility guidance
The Let Property Campaign
Where the undisclosed income is UK rental income rather than offshore income, the Let Property Campaign is the relevant route. It works on similar principles but is designed specifically for landlords.
🏠 Let Property Campaign guidance
Which forms do you actually need?
You will not need every form listed here. The right combination depends on your residence position, income sources, property ownership, National Insurance history, and whether you are already registered for self assessment.
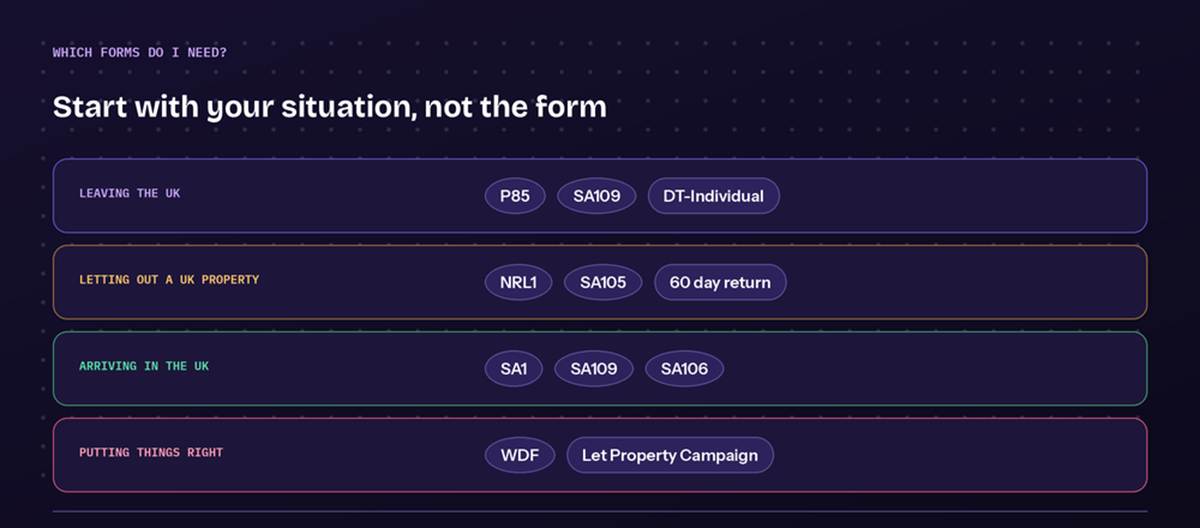
Image 2 — by situation rather than by form
Before completing anything, take these steps:
● Establish your UK residence position under the Statutory Residence Test.
● List your UK and overseas income, gains, properties, pensions and investments.
● Check whether you already have a UTR and whether you are registered for self assessment.
● Identify whether you need a repayment, a treaty claim, gross rental approval, or a disclosure.
● Use the current form for the relevant tax year.
● Keep copies of the form, supporting documents, calculations and submission evidence.
If your circumstances involve multiple countries, split-year treatment, the FIG regime, UK rental property or historic offshore income, a professional review reduces the risk of an incomplete or inconsistent submission.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated