
If you are living abroad while keeping property interests in the UK, you are classified as a non-resident landlord. Rental yield from a UK asset is an attractive part of a global portfolio, but it brings a set of obligations defined by HMRC.
Working within the Non-Resident Landlord Scheme is not an administrative preference. It is a statutory requirement. This guide sets out your responsibilities for the 2026/27 tax year.
Defining the non-resident landlord
The first step is working out whether you fall within the scheme at all. HMRC defines a non-resident landlord as any person who has UK rental income and whose usual place of abode is outside the UK.
For the purposes of the scheme, HMRC generally treats your usual place of abode as outside the UK if you are absent from the country for six months or more.
If you are non-resident under the Statutory Residence Test you will certainly be treated as a non-resident landlord. However, it is important to keep the two apart. The non-resident landlord definition is considerably broader than the residence test, so it is possible to be within the scheme while still being UK resident for wider tax purposes.
📄 HMRC guidance on non-resident landlord scheme.
The default position: tax withheld at source
A common misconception among expat landlords is that tax is only due when the annual return is filed. The default position under the scheme is withholding at source, which means the responsibility for collecting tax sits with whoever pays the rent, so either your letting agent or your tenant.
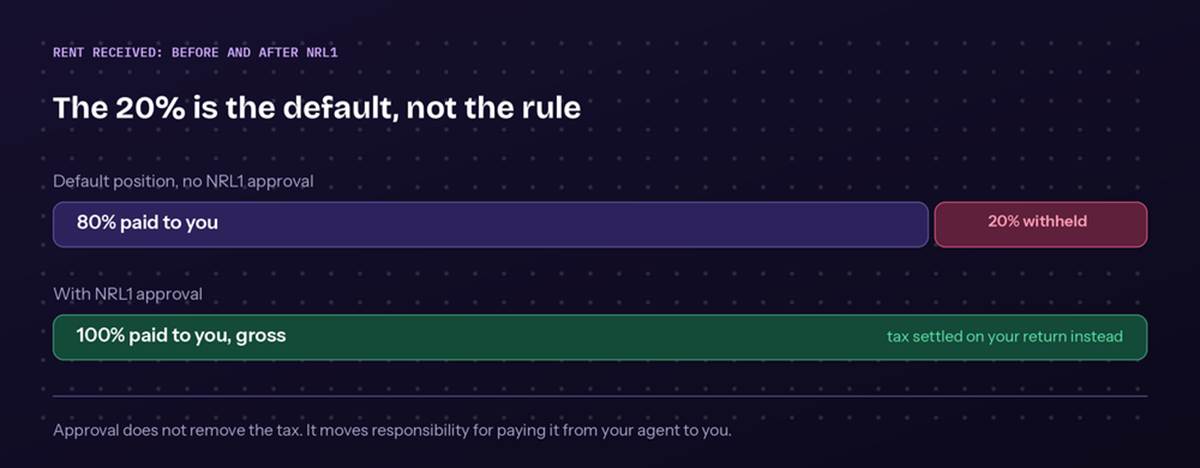
Image 1 — the default position against gross payment
Unless HMRC has given specific authorisation to the contrary, the following applies.
● Letting agents. If you use a professional letting agent, they are legally required to withhold 20%, the basic rate, from your rental income. The tax is calculated after deducting certain allowable expenses the agent has paid on your behalf.
● Tenants. If you do not use an agent and your tenant pays more than £100 a week in rent, the tenant becomes responsible for withholding the 20% and paying it to HMRC quarterly.
If you want to receive your rental income in full, you need to change this arrangement proactively. That is done by applying for gross payment status, which shifts responsibility for paying the tax from the agent or tenant onto you.
How to apply for gross payment: the NRL1 form
To receive your rent gross, without the 20% deduction, you file form NRL1 with HMRC. This is a formal application to be approved to receive rent without deduction under the scheme.
Once approved, HMRC issues a notice to your letting agent or tenant authorising them to stop withholding tax.
Approval is not instantaneous and processing can take a number of weeks. We recommend submitting the NRL1 as soon as you move abroad, or as soon as you begin letting a UK property while living overseas, rather than waiting until the first rent is withheld.
Mandatory reporting: your annual tax return
As a non-resident landlord you must file a UK self assessment tax return each year. That requirement applies whether the property has made a profit or a loss.
The return comprises the main SA100, the SA105 property pages, and the SA109 residence pages that every non-resident needs. Note that HMRC’s own free online service cannot file the SA109, so you will need commercial software or an adviser.
If you are a UK or EEA national you are entitled to claim the UK personal allowance, which remains at £12,570 for 2026/27. Claiming it through the return can offset a significant portion of your rental profits, or potentially all of them, before tax applies.
Calculating taxable profit and allowable expenses
To keep your UK liability down, keep meticulous records of allowable expenses. HMRC lets you deduct costs incurred wholly and exclusively for the purpose of renting out the property.
Common allowable expenses include:
● Letting agent fees and management commissions.
● Property insurance, covering buildings, contents and rent guarantee.
● Maintenance and repairs. Improvements, such as an extension, are not deductible against income tax, although they may reduce a future capital gain.
● Utility bills and council tax, where you pay them rather than the tenant.
● Professional fees, such as legal costs for renewing a lease or accountancy fees for preparing the return.
Mortgage interest works differently
Finance costs, including mortgage interest, are not an allowable expense and have not been since the restriction was fully phased in from April 2020. Instead they give a basic rate tax reducer of 20%, applied to your tax bill after the rental profit has been calculated.
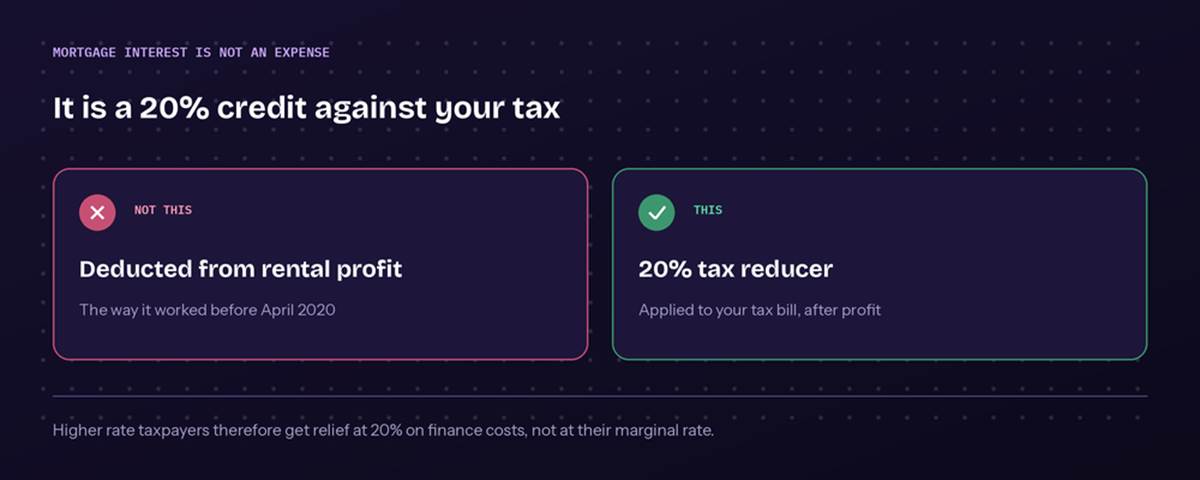
Image 2 — how finance costs are relieved
The practical effect is that your taxable rental profit is higher than the cash you actually keep, and higher rate taxpayers get relief on interest at 20% rather than at their marginal rate.
Capital gains tax: the 60 day window
If you sell, the compliance requirements become much more time sensitive. Non-residents disposing of UK property are within the non-resident capital gains tax rules, which since April 2019 cover all UK land and property rather than residential alone.
You must file a non-resident capital gains tax return and pay any tax due within 60 days of the completion date. This is a standalone requirement that exists independently of your annual self assessment return.
⚠️ WARNING The 60 days runs from completion, not from exchange of contracts. The two can be weeks or months apart, and assuming the clock starts at exchange is a common way to lose time you cannot get back. The return is also required even where there is no tax to pay.
The Let Property Campaign
It is not uncommon for people to move abroad and simply not notify HMRC of their rental income. Perhaps you assumed that because the property was making a loss, or because the income fell below the personal allowance, there was nothing to report.
HMRC takes a different view. If you have undisclosed rental income from earlier years you need to report it, and the most efficient route is the Let Property Campaign. This voluntary disclosure facility lets you bring your affairs up to date on lower penalty terms than if HMRC finds the omission first.
Your 2026/27 checklist
● Confirm your status. Use the Statutory Residence Test to confirm your residence position, and check the usual place of abode test for the scheme itself.
● Register early. Submit the NRL1 as soon as possible, so that the 20% withholding does not start in the first place.
● Keep digital records. Rental income, tenancy agreements and receipts for allowable expenses, kept as you go rather than reconstructed later.
● Monitor deadlines. The return is due by 31 January following the end of the tax year, with payment on the same date.
● Claim your allowances. Check your eligibility for the personal allowance to protect the first £12,570 of profit.
● Plan for disposal. If you are selling, the 60 day reporting and payment window runs from completion.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated