
Are you planning to leave the UK for a period of no more than five years? If so, this article is for you.
Becoming non-resident can offer substantial tax advantages, but you need to be aware of the temporary non-residence rules. These are anti-avoidance measures designed to stop people leaving the UK briefly to realise income or gains free of tax before returning shortly afterwards.
In short, if you leave the UK but return within five years, HMRC may treat your absence as temporary. Where that happens, the tax advantages you thought you had secured while abroad are effectively undone on your return.
Who do the rules apply to?
The first step is working out whether you are within scope at all.
To be caught you must have been solely resident in the UK for at least four out of the seven tax years immediately preceding the tax year of your departure. For example, if you move abroad in the 2026/27 tax year, HMRC looks back at your residence status from 2019/20 to 2025/26. If you were resident in four of those years, the provisions follow you while you are abroad.
Solely resident means you were either resident only in the UK, or dual resident but ultimately treated as UK resident under the relevant treaty tie-breaker.
HMRC guidance on sole residence.
What income and gains are caught?
The scope is broad, and it targets the kinds of wealth most easily realised during a short absence.
● Pension income. Specifically, pension withdrawals that were exempt under a double taxation agreement.
● Dividends from close companies. Including both UK and foreign resident companies.
● Remittance basis income. For anyone who previously used the remittance basis, income excluded from tax that is remitted to the UK while you are abroad.
● Gains on shares or crypto. Any gains on assets, such as stocks, shares or cryptocurrency, that you acquired before leaving the UK.
● Pre-April 2015 property gains. Where you sell UK property as a non-resident and use rebasing to exempt the portion of the gain relating to the period before April 2015.
It is a common misconception that being non-resident gives you a complete tax holiday. It does not.
What is not caught
It is worth being clear about the other side of this. Gains on assets you acquire after you become non-resident are generally outside the rules, because the legislation is aimed at value that had already built up while you were in the UK.
That distinction matters for planning. An asset bought while abroad and sold while abroad does not come back into charge on your return in the way a pre-departure holding does.
The five year rule
To stay outside the rules, your period of non-residence must exceed five years. The legislation bites where you return within five years or less, so in practical terms you need at least five years and one day.
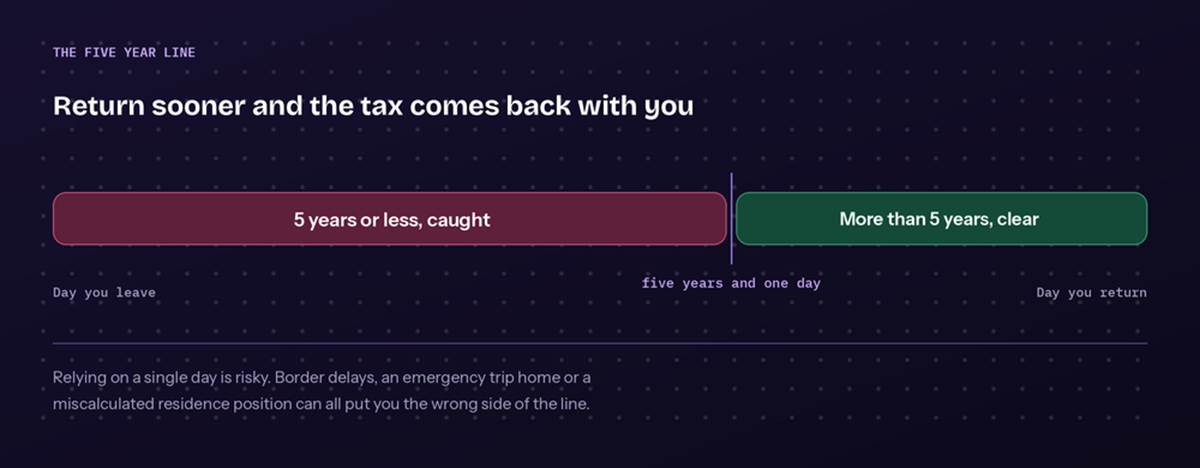
Image 1 — which side of the line you land on
⚠️ WARNING Relying on a single day is a high risk strategy. Border delays, an emergency trip home, or a miscalculation of your residence position under the Statutory Residence Test can each put you the wrong side of the threshold, and the consequence is that several years of income and gains come back into charge at once.
We therefore recommend building in a safety buffer. Where your circumstances allow, stay non-resident for at least five years and a couple of months. That extra time means a dispute about your exact departure or return date does not put the whole position at risk.
How the rules are triggered: a worked example
If you trigger the rules by returning too early, HMRC does not tax you while you are abroad. Instead it uses a deeming mechanism, treating the income you received or the gains you realised while abroad as arising in the tax year you come back.
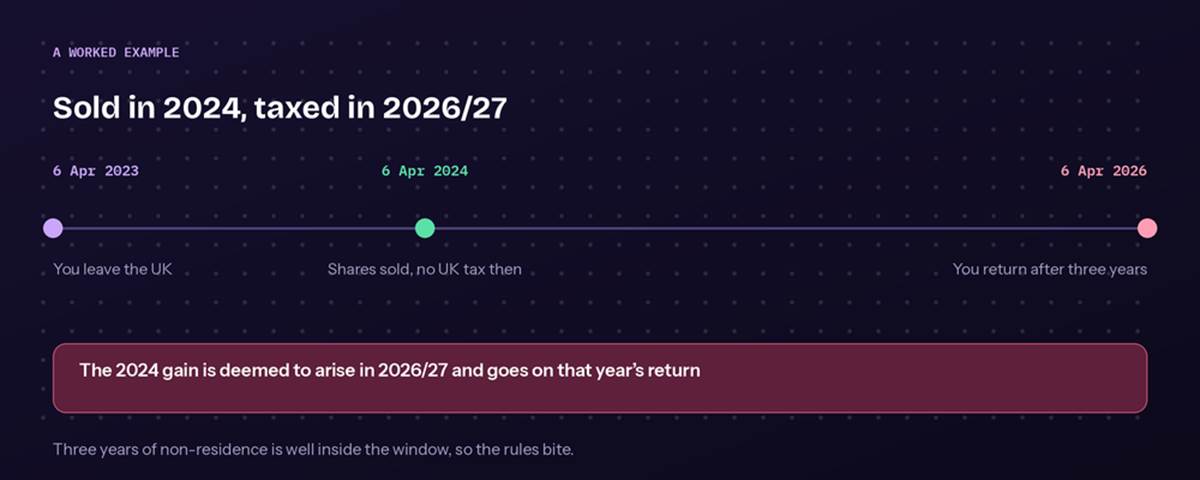
Image 2 — the deeming mechanism in practice
● Departure. You leave the UK on 6 April 2023 and become non-resident.
● Asset sale. On 6 April 2024, while living in a tax neutral jurisdiction such as the UAE, you sell a portfolio of shares held for a decade. At that point the gain is not taxable in the UK, because you are non-resident.
● Return. You come back to the UK on 6 April 2026.
Because the period of non-residence was only three years, well within the five year window, the rules are triggered. HMRC treats the 2024 share gains as realised in the 2026/27 tax year. You declare them on that year’s UK tax return and pay the capital gains tax then.
Mitigating double taxation
A concern for anyone moving somewhere that is not a tax haven is being taxed twice on the same gain.
If you paid tax in the country you were resident in at the time the income was received or the gain was realised, HMRC will allow a foreign tax credit for that overseas tax, reducing your UK liability.
That prevents you paying more than the higher of the two rates overall. It does not, however, change the fact that you will owe HMRC the difference where the UK rate is higher than the rate you paid abroad.
Careful planning
The temporary non-residence rules are complex but they are not insurmountable. With planning, income and gains can remain free of UK tax not just in real time but permanently. The key is maintaining non-resident status for the full period the legislation requires.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated