
Key points
Dual residence is common in the year you move, and the treaty tie-breaker decides who taxes what.
✓ The tests run in a fixed order: permanent home, centre of vital interests, habitual abode, then nationality.
✓ Treaty non-residence limits what the UK can tax, but you are still UK resident for the FIG regime, inheritance tax and split-year purposes.
✓ It is not automatic. Claim it in the dual residence section of the SA109, using helpsheet HS302.
✓ HMRC's online service cannot file the SA109, so you need commercial software or a paper return.
✓ A certificate of residence from the other country is the best evidence for the claim.
If you split your life between the UK and another country, you can end up tax resident in both at the same time. It happens most often in the year you move, or when you keep homes in two places. Both countries may then claim the right to tax your worldwide income.
Double tax treaties exist to settle that. Their tie-breaker rules decide which country you are resident in for treaty purposes, and that decides who taxes what. But a treaty does not change your UK residence under the Statutory Residence Test, and that gap catches people out.
This guide explains how dual residence arises, how the tie-breaker tests work, what treaty non-residence does and does not change, and how to claim it.
For advice on your own cross-border position, see our international tax advice for individuals.
How can you be resident in two countries?
Each country applies its own domestic rules. The UK uses the 📖 Statutory Residence Test, which looks at days, ties and work. Other countries use their own tests, often 183 days, a permanent home or where your family lives.
Because the tests are different, you can meet both. A common example is the year you move: you are UK resident under the SRT for the whole tax year, and resident in your new country from the day you arrive.
How double tax treaties settle it
What happens when both countries claim you? If the UK has a double tax treaty with the other country, Article 4 of the treaty contains tie-breaker tests. They decide which country you are resident in for the purposes of that treaty.
The other country becomes the source country. It can still tax income that arises there, but generally not your income from elsewhere. Without a treaty, you rely on each country's unilateral relief for foreign tax, which is often less generous.
The UK has one of the largest treaty networks in the world. See our guide to 📖 how UK double tax treaties give relief.
👉 GOV.UK: UK tax treaties by country
The four tie-breaker tests
Most UK treaties follow the OECD Model Tax Convention, which sets out four tests in a fixed order. If a test points to one country, you stop there. If it points to both or neither, you move to the next.
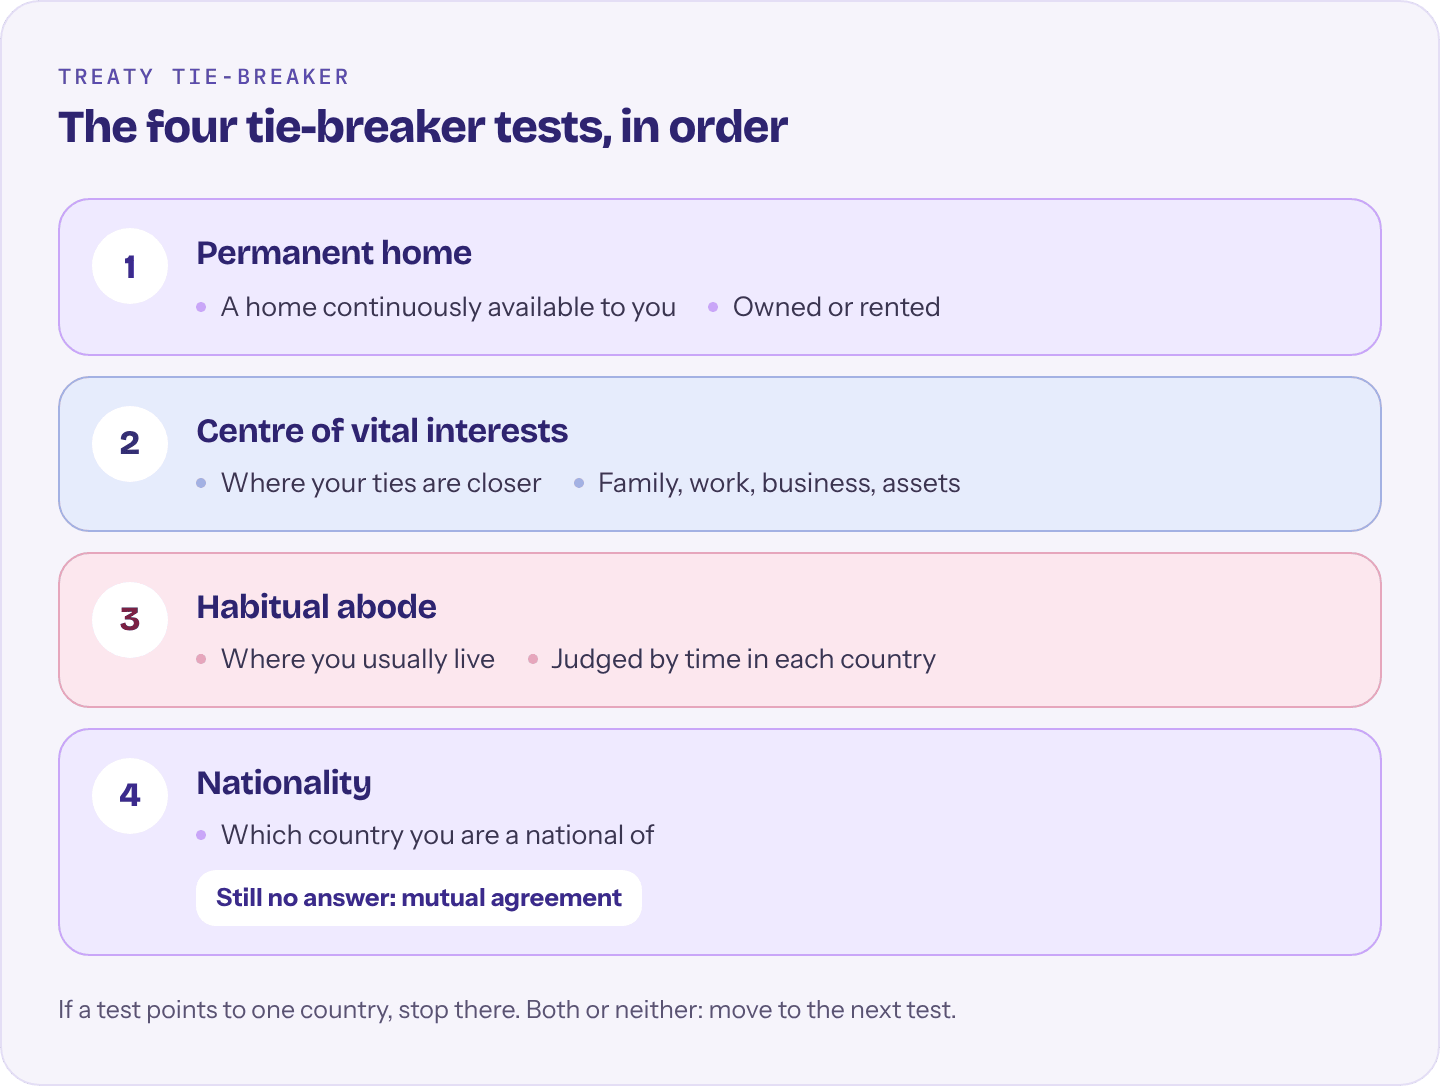
Image 1: the four tests, in order
Test, in order | The question |
|---|---|
1. Permanent home | Where do you have a home continuously available to you, owned or rented? |
2. Centre of vital interests | Where are your personal and economic ties closer: family, work, business, assets? |
3. Habitual abode | Where do you usually live, judged by how much time you spend in each country? |
4. Nationality | Which country are you a national of? |
If a test points to one country, that country is your treaty residence and you stop there. If it points to both or neither, move on to the next test. If there is still no answer after nationality, the two tax authorities settle it between them under the mutual agreement procedure.
1. Permanent home
Where do you have a permanent home available to you? You do not need to own it, but it must be available continuously, not just for short stays. If you have a permanent home in only one country, you are treaty resident there.
2. Centre of vital interests
If you have a permanent home in both countries, or neither, the test is where your personal and economic relations are closer. That covers your family, your work or business, your assets and your social life.
3. Habitual abode
If your centre of vital interests cannot be determined, the next test is where you habitually live. It looks at how often and for how long you stay in each country, usually over more than one year.
4. Nationality
If you have a habitual abode in both countries, or neither, you are resident in the country you are a national of. If you are a national of both or neither, the two tax authorities decide between them under the mutual agreement procedure.
Treaties vary, so always check the wording of the specific treaty. The US treaty is a notable example: it keeps the US right to tax its citizens wherever they live. See our guide to the 📖 UK-US double tax treaty.
What treaty non-residence changes, and what it does not
The treaty limits what the UK can tax, but it does not make you non-resident under the SRT. For UK purposes, you are still a UK resident who is treaty resident elsewhere.

Image 2: what the treaty changes, and what it does not
What the treaty usually changes:
➜ Foreign income: the UK generally cannot tax income arising outside the UK.
➜ Most foreign gains: gains on non-UK assets usually fall to the country you are treaty resident in.
➜ Overseas workdays: pay for work done outside the UK is generally taxed where you live and work.
What it usually does not change:
➜ UK rent and UK property: the UK keeps the right to tax income from UK land and gains on UK property. See 📖 non-resident capital gains tax.
➜ UK workdays: pay for work physically done in the UK is usually still taxable here.
➜ The FIG regime: a year of treaty non-residence still counts as a UK-resident year for the 10-year test. See our guide to the 📖 4-year FIG regime.
➜ Inheritance tax: long-term residence is based on SRT years. Only the UK's few estate tax treaties can override it.
➜ Split-year treatment: it is decided under the SRT, not the treaty. See 📖 split-year treatment.
👉 HMRC manual: treaty non-residence and the FIG regime (RFIG44000)
👉 The law: Income Tax (Trading and Other Income) Act 2005, section 845B (qualifying new residents)
How to claim treaty non-residence
Does the treaty apply automatically? No. You must claim it on your Self Assessment return, using the dual residence boxes on the SA109 residence pages. HMRC's helpsheet HS302 explains how.
HMRC's free online service cannot file the SA109, so you will need commercial software or a paper return. See 📖 do I need to file a UK tax return.
👉 HMRC helpsheet: HS302 Dual residents
Keep evidence that supports each test: tenancy agreements and property records, where your family lives, employment contracts, and travel records. A certificate of residence from your new country's tax authority helps too. If you would like your residence position confirmed before you make the claim, our Statutory Residence Test service is the place to start.
👉 HMRC guidance: certificates of residence
Dual residence in practice
Example 1: James in Spain
➜ James splits his time between London and Madrid, and is resident in both countries under their domestic rules.
➜ He has sold his UK flat. His only permanent home is his apartment in Madrid.
➜ The first test settles it. James is treaty resident in Spain, so the UK cannot tax his non-UK income, but it still taxes his UK workdays and any UK rent.
See our guide to 📖 moving to Spain from the UK.
Example 2: Heather in Portugal
➜ Heather moves to Lisbon for work and rents a flat there. Her husband and children stay in the family home in the UK.
➜ She has a permanent home in both countries, so the first test does not settle it.
➜ Her family ties are in the UK, so her centre of vital interests is the UK. She is treaty resident in the UK, which keeps the right to tax her worldwide income.
Heather's case is the one people find hardest to accept. Moving yourself is not always enough. Where the family home and the family stay behind, the centre of vital interests usually stays with them. See our guide to 📖 moving to Portugal from the UK.
Common mistakes with dual residence
➜ Assuming the treaty makes you non-resident. It limits UK taxing rights, but you are still UK resident under the SRT for FIG, inheritance tax and split-year purposes.
➜ Not claiming it. Treaty relief is not automatic. Without the SA109 claim, HMRC taxes you as a normal UK resident.
➜ Relying on day counts alone. The first tests look at homes and ties, not days. A permanent home left available in the UK can decide the case.
➜ Using the OECD order without checking. Some treaties change the tests or add conditions, so read the treaty that applies to you.
Frequently asked questions
Can you be tax resident in two countries at once?
Yes. Each country applies its own residence rules, and you can meet both. It is most common in the year you move, or when you keep homes in both countries.
Which country wins if I am dual resident?
If there is a double tax treaty, its tie-breaker tests decide: permanent home, then centre of vital interests, then habitual abode, then nationality. The first test that points to one country settles it.
Does treaty non-residence make me non-resident in the UK?
No. You are still UK resident under the Statutory Residence Test. The treaty only limits what the UK can tax. Treaty non-resident years still count as UK-resident years for the FIG regime and inheritance tax.
How do I claim treaty non-residence?
On your Self Assessment return, using the dual residence section of the SA109 residence pages. HMRC's helpsheet HS302 explains the claim. You will need commercial software or a paper return, because HMRC's online service cannot file SA109.
What is a certificate of residence?
A letter from a tax authority confirming you are resident there for treaty purposes. It is the best evidence to support a treaty claim, and it is often needed to reduce foreign withholding tax.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Taxation (International and Other Provisions) Act 2010, section 2 and Finance Act 2013, Schedule 45, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us plan your international tax position
We plan your residence, timing, reliefs and treaty position, then handle the claims and returns that put it into effect. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ Residence status planned under the Statutory Residence Test
➜ Asset and gain timing around the residence line
➜ Treaty and double tax planning, including foreign tax credits
➜ Claims and returns filed, including treaty claims and the SA109
Typical fee
£1,000 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico