
Key points
Selling UK property from abroad means a separate 60-day return, a choice of calculation methods and an extra test for Private Residence Relief.
✓ Non-residents must report every disposal of UK property or land within 60 days of completion, even with no gain, a loss or no tax due.
✓ For 2026/27, gains are taxed at 18% within your unused basic rate band and 24% above it, after the £3,000 annual exempt amount.
✓ If you owned the property on 5 April 2015, there are three ways to work out the gain: rebasing, time apportionment or the whole gain.
✓ For tax years you were non-resident, Private Residence Relief needs at least 90 midnights in the property by you, your spouse or civil partner.
✓ The final 9 months always qualify if the property was your main home at some point.
✓ Under most treaties the UK keeps the right to tax UK land, and your country of residence gives credit for the UK tax.
Selling a UK property while you live abroad comes with its own set of rules. There is a separate 60-day return, a choice of three ways to work out the gain, and a residence relief with an extra condition most people have never heard of.
If you are not UK resident, you must report every disposal of UK property or land to HMRC within 60 days of completion. That applies even when there is no tax to pay, or you have made a loss, or you already file Self Assessment.
This guide covers what is in scope, the 60-day deadline, 2026/27 rates, the three calculation methods with a worked example, Private Residence Relief and the 90-day rule, and double tax.
Do non-residents pay Capital Gains Tax on UK property
Yes. Non-residents pay UK Capital Gains Tax on gains from selling UK property or land. For residential property the rates are 18% and 24%, after the £3,000 annual exempt amount. You must report the sale to HMRC and pay any tax within 60 days of completion, even if no tax is due. If you owned the property before 6 April 2015, you can usually work out the gain from its value on that date.
👉 HMRC guidance: Tell HMRC about capital gains tax on UK property if you are not UK resident
👉 The law: Taxation of Chargeable Gains Act 1992, section 1A (territorial scope)
The 60-day return
You must report the disposal and pay any tax within 60 days of completion. It is a separate return from Self Assessment, filed through HMRC's online capital gains tax on UK property account.

Image 1: the 60-day clock starts at completion
Stage | What happens |
|---|---|
Offer accepted | Start: valuation at 5 April 2015, cost records, open the HMRC account |
Exchange | Contracts become binding. The clock has not started yet |
Completion (day 0) | Ownership passes. The 60 days start here |
Day 60 | Return filed and tax paid |
➜ It is always required: non-residents must report even if there is no gain, a loss, or no tax to pay.
➜ The clock starts at completion: not at exchange of contracts. The two dates can be weeks apart.
➜ Payment runs to the same deadline: HMRC gives you a payment reference starting with X once you have filed.
➜ It comes with penalties: late filing and late payment lead to penalties and interest.
➜ Set up the account early: creating the account and any agent access takes time, so start before completion.
If you also file Self Assessment for the year, you report the disposal again on the capital gains pages and the tax already paid is credited.
👉 HMRC service: Report and pay capital gains tax on UK property
👉 The law: Finance Act 2019, Schedule 2, paragraph 3 (60-day return deadline)
Rates and allowance for 2026/27
Individuals pay capital gains tax at:
➜ 18% on gains that fall within your unused basic rate band.
➜ 24% on gains above it.
The annual exempt amount is £3,000, and non-residents get it in the same way as UK residents. Your rate depends on your taxable UK income for the year, so with little or no UK income, more of the gain falls into the 18% band.
How to work out the gain: three methods
Do you pay tax on the whole gain? No. Non-residents are only taxed on residential property growth from April 2015. If you owned the property on 5 April 2015, there are three ways to calculate the gain:
➜ Rebasing, the default: the gain is the sale price less the market value on 5 April 2015 and costs. Only improvements made after that date count.
➜ Time apportionment: work out the gain over the whole period of ownership, then tax only the share of it that relates to the period after 5 April 2015.
➜ Whole gain: the gain over the whole period, without rebasing. Usually only worth electing to crystallise a loss.
For non-residential property and indirect disposals, the rebasing date is 5 April 2019 and time apportionment is not available.
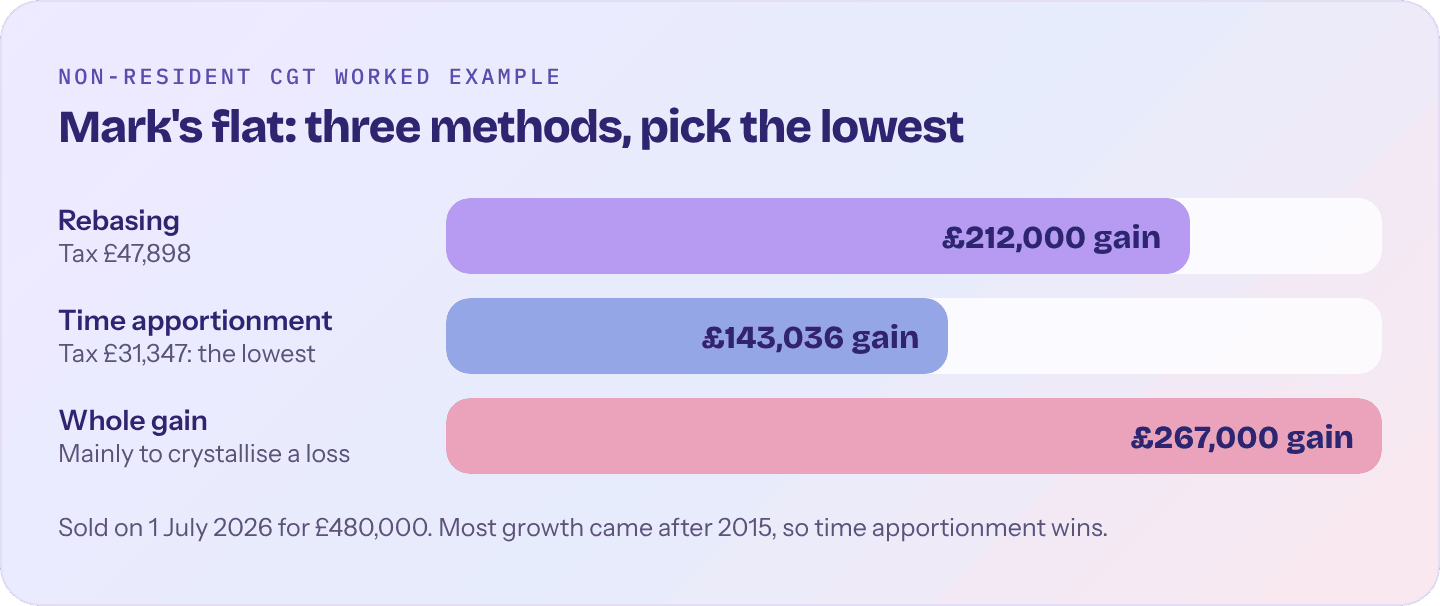
Image 2: three methods, pick the lowest
Worked example: Choosing the method
Mark bought a flat on 1 July 2005 for £200,000, plus £5,000 of buying costs. He let it out throughout, so Private Residence Relief does not apply.
It was worth £260,000 on 5 April 2015. He now lives in Singapore and completes a sale on 1 July 2026 for £480,000, with £8,000 of selling costs.
Rebasing: £480,000 less £8,000 less £260,000 gives a gain of £212,000.
Time apportionment: the whole gain is £267,000. The post-April 2015 share is 135 of 252 months, so £143,036.
Whole gain: £267,000.
Time apportionment wins here because most of the growth came after 2015. With no other UK income, Mark's tax is £31,347, against £47,898 on the rebasing figure. He files and pays by 30 August 2026.
Use our non-resident capital gains tax calculator to compare the methods on your own figures.
👉 HMRC guidance: Work out your tax if you are a non-resident selling UK property
👉 The law: Taxation of Chargeable Gains Act 1992, Schedule 4AA (rebasing for UK land)
Private Residence Relief and the 90-day rule
Private Residence Relief can remove some or all of the gain. But since April 2015, a non-resident owner has an extra condition for each tax year after they leave.
➜ The 90-day rule: a tax year only qualifies if you, your spouse or civil partner spent at least 90 midnights in the property, or in UK homes you had between you.
➜ Years you lived there: years when it was genuinely your main home qualify in the usual way.
➜ The final 9 months: always qualify if the property was your main home at some point, whether or not you lived there at the end.
➜ Absence reliefs: periods away, such as working abroad, can count as occupation, but they need you to move back in afterwards and still meet the 90-day rule, which rarely fits someone selling from overseas.
➜ Letting relief: since April 2020, only available where you shared the home with a tenant, not where you let the whole property.
You claim the relief, and nominate the property as your main residence, when you file the 60-day return. Spending 90 nights in the UK to protect the relief can also affect your UK residence position, so check the 📖 Statutory Residence Test before you plan any visits.
👉 GOV.UK: Tax if you live abroad and sell your UK home
👉 The law: Taxation of Chargeable Gains Act 1992, section 222B (the 90-day rule)
Capital gains tax on a former main residence
Selling the home you used to live in does not escape capital gains tax just because it was once your main residence. Relief covers the time you lived there, plus the final nine months of ownership. Under the default rebasing method, only the period from 6 April 2015 counts.
Worked example. Sam bought a house in 2010 and lived in it until leaving the UK on 5 April 2020. The house was worth £300,000 on 6 April 2015. Sam sells it on 5 October 2026 for £420,000.
Step | Figure |
|---|---|
Gain since 6 April 2015 (£420,000 less £300,000) | £120,000 |
Ownership counted, 6 April 2015 to 5 October 2026 | 138 months |
Lived there, 6 April 2015 to 5 April 2020 | 60 months |
Final period, always relieved | 9 months |
Share relieved (69 of 138 months) | 50% |
Private residence relief | £60,000 |
Gain left to tax | £60,000 |
Less annual exempt amount for 2026/27 | £3,000 |
Taxable gain | £57,000 |
The taxable gain is then charged at 18% or 24%, depending on Sam's other UK income. Selling and legal costs would reduce the gain further.
Which costs can you deduct?
What reduces the gain? Three types of cost:
➜ Buying costs: solicitor and survey fees and Stamp Duty Land Tax, but only under time apportionment or the whole-gain method.
➜ Selling costs: estate agent fees, conveyancing fees and advertising.
➜ Improvements: capital work such as an extension or loft conversion. Under rebasing, only improvements after 5 April 2015 count.
Repairs, maintenance and redecoration are not capital costs, and if you let the property, they were probably claimed against rent already. Keep every invoice, since HMRC can check the figures later.
Losses
You still file the 60-day return. The loss is set against other UK property gains in the same year, and any unused loss carries forward against future UK property gains. If you later become UK resident again, unused losses can be used against gains generally.
Will you be taxed twice?
Does your new country tax the gain too? Often it does. Under most treaties, the UK keeps the right to tax gains on UK land, and your country of residence gives credit for the UK tax.
➜ Report and pay in the UK within 60 days.
➜ Declare the gain in your country of residence under its rules and deadlines.
➜ Claim credit there for the UK tax, up to the local tax on the same gain.
Your new country may calculate the gain differently, using the original cost rather than a 2015 value, or giving its own main-home relief. See our guide to 📖 double tax treaties.
Start when you accept an offer
Why not wait until completion? Because 60 days goes quickly. A valuation at 5 April 2015, your improvement records, the 90-day history and the online account all take time. Starting when you accept an offer means the return is ready when the sale completes. If you would like the computation and the 60-day return handled for you, speak to our capital gains tax advisers.
If you have rental income from the property too, see our guide to the 📖 non-resident landlord scheme and our overview of 📖 what the UK taxes once you have left.
Frequently asked questions
Do non-residents pay capital gains tax on UK property?
Yes. Non-residents pay UK capital gains tax on gains from UK residential and non-residential property and land, generally only on growth since April 2015 for homes and April 2019 for other property.
What is the 60-day rule for non-residents selling UK property?
You must file a UK property return and pay any tax within 60 days of completion. Non-residents must file even if there is no gain, a loss or no tax due.
Can non-residents claim Private Residence Relief?
Yes, for years it was your main home. For tax years when you were non-resident, a year only qualifies if you or your spouse spent at least 90 nights in the property. The final 9 months always qualify.
Do non-residents get the annual exempt amount?
Yes. Non-resident individuals get the £3,000 annual exempt amount for 2026/27, the same as UK residents. It can only be used once in a tax year.
Do non-residents pay UK tax on selling shares?
Generally not, unless the company gets 75% or more of its value from UK land and you hold 25% or more. The temporary non-residence rules can also catch share gains if you return within five years.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Taxation of Chargeable Gains Act 1992, section 1A and Finance Act 2019, Schedule 2, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us work out and report your gain
We calculate your gain using the methods open to you, apply the reliefs you qualify for and file your 60-day return. Every calculation is prepared and signed off by Emma McDermott, ATT.
➜ 60-day return prepared and filed on time
➜ Rebasing and time apportionment compared to find the lower figure
➜ Private residence relief reviewed
➜ Allowable costs, losses and the annual exempt amount applied
Typical fee
£750
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico