
Key points
A treaty does not stop both countries taxing you. It decides who taxes first, how much, and how the other country gives relief.
✓ Treaties relieve double tax in three ways: exclusive taxing rights, a capped rate in the source country, or a credit in your country of residence.
✓ Under most UK treaties, private pensions are taxed only where you live, government service pensions only by the paying country, and rent first where the property is.
✓ Credit relief is capped at the UK tax on the same income, so overall you pay roughly the higher of the two rates.
✓ No treaty? UK residents can usually still claim unilateral foreign tax credit relief.
✓ Claims have time limits, usually four years from the end of the tax year for UK claims.
When you live in one country and have income or gains in another, both may want to tax the same money. Double tax treaties decide which country gets the first bite, how much the other can take, and how relief is given so you are not taxed twice.
The UK has one of the largest treaty networks in the world, covering more than 130 jurisdictions. But a treaty never applies itself. Relief has to be claimed, and the way you claim depends on where you live and what the income is.
This guide covers the three ways treaties relieve double tax, the usual position for each type of income, worked examples, and exactly how to claim.
For advice on your own cross-border position, see our international tax advice for individuals.
What is a double tax treaty (double taxation agreement)?
A double tax treaty, or double taxation agreement, is an agreement between two countries that allocates taxing rights over income and gains. Most UK treaties follow the OECD Model Tax Convention, so the structure is similar even where the detail differs.
Each treaty covers the taxes it names, usually income tax and capital gains tax. Only a handful of countries have an estate tax treaty with the UK for inheritance tax.
👉 GOV.UK: The UK's tax treaties, country by country
When does double taxation happen?
There are two common situations:
➜ You are resident in both countries: you meet the UK 📖 Statutory Residence Test and the other country's rules in the same year. The treaty's tie-breaker then decides where you are treated as resident. See our guide to 📖 dual tax residency.
➜ You are resident in one and the income comes from the other: the source country taxes income that arises there, and your residence country taxes your worldwide income.
Most treaty questions are the second kind. The key is to separate the residence country, where you live for treaty purposes, from the source country, where the income arises.
The three ways a treaty gives relief
Depending on the income, a treaty uses one of three mechanisms:

Image 1: the three relief mechanisms
➜ Exclusive taxing rights: only one country can tax, and the other must exempt the income. Private pensions are a common example, usually taxable only where you live.
➜ Limited source taxation: the source country can tax, but only up to a capped rate, often 10% or 15% for dividends and interest.
➜ Credit relief: both countries can tax, and your residence country gives a credit for the source country's tax. Overall you pay roughly the higher of the two rates.
Limited taxation and credit relief usually work together. The source country is capped, and the residence country credits whatever the source country took.
Worked example: German dividends for a UK resident
Tom is UK resident and a higher-rate taxpayer. He receives a £10,000 dividend from a German company.
Detail | Figure |
|---|---|
Dividend | £10,000 |
German tax at the treaty cap of 15% | £1,500 |
UK tax at 35.75%, ignoring the dividend allowance | £3,575 |
Foreign tax credit relief | £1,500 |
Left to pay HMRC | £2,075 |
Tom's total tax | £3,575 |
Tom pays the UK rate, not £5,075. If Germany withholds more than 15%, the excess is reclaimed from Germany, not the UK. Credit relief is capped at the UK tax on the same income, so it can never create a UK repayment.
👉 GOV.UK: UK-Germany double taxation convention
Typical treaty positions by income type
Every treaty is different, but under most UK treaties the usual position is:
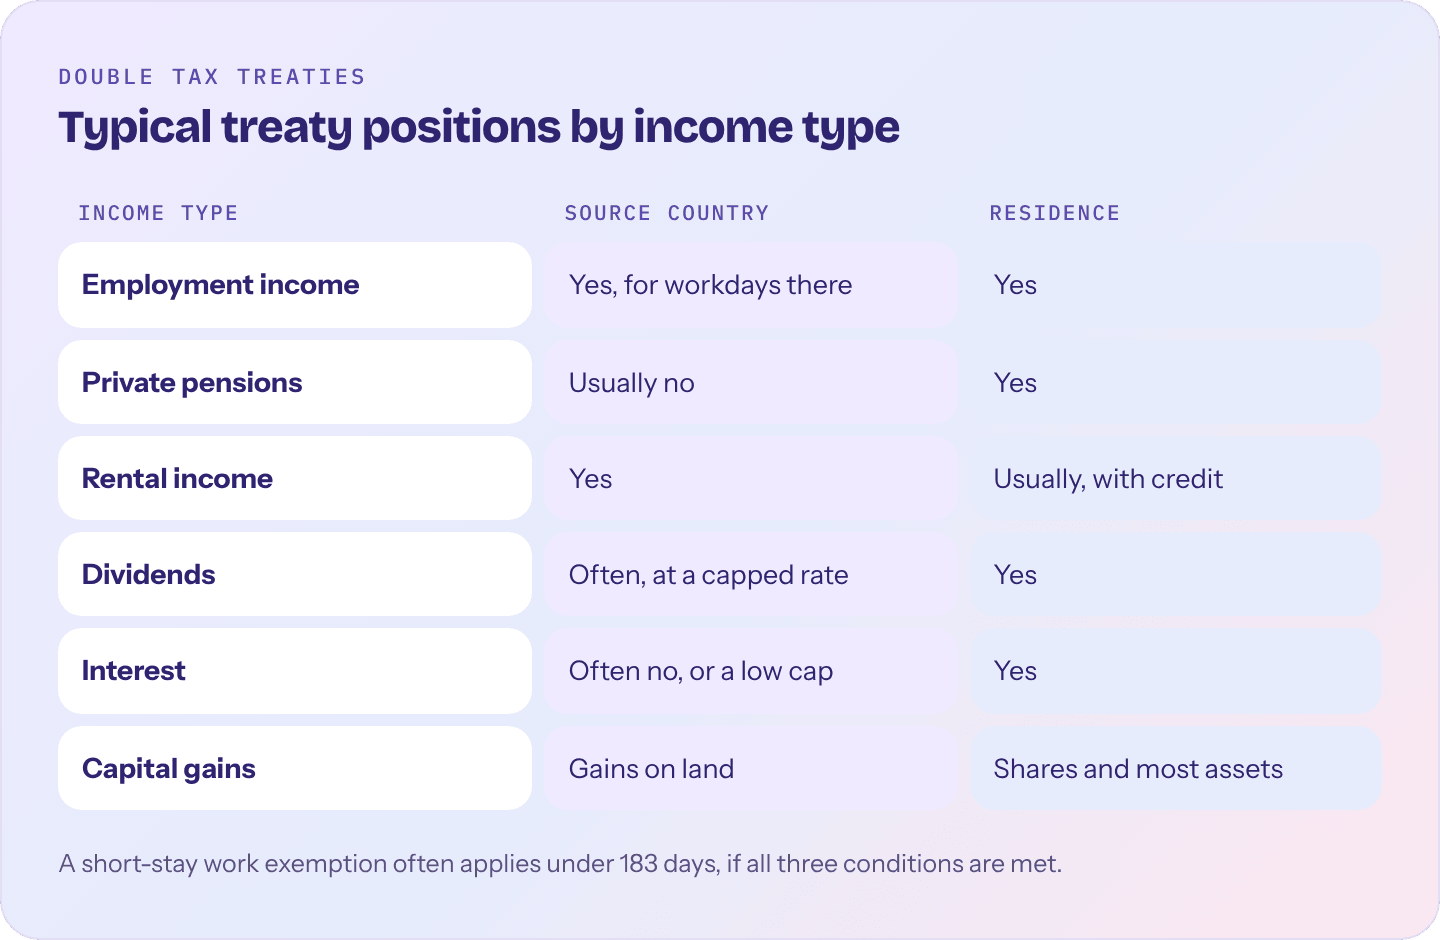
Image 2: typical positions by income type
➜ Employment income: taxed where you live, but the country where you physically work can tax pay for those workdays. A short-stay exemption often applies if you are there under 183 days, your employer is not resident there, and no local branch bears the cost. All three conditions must be met.
➜ Private and workplace pensions: usually taxable only in your country of residence. See our guide to 📖 UK pensions when you live abroad.
➜ Government service pensions: for civil service, military or teaching service, usually taxable only by the paying country, unless you are a national and resident of the other country.
➜ Rental income: taxable where the property is, and usually also where you live, with credit for the source country's tax.
➜ Dividends: taxable where you live, with the source country often allowed a capped rate.
➜ Interest: under many UK treaties, taxable only where you live, or with a low capped source rate.
➜ Capital gains: gains on land are taxable where the land is. Gains on shares and most other assets are usually taxable only where you live.
The UK does not withhold tax on dividends or bank interest, so for non-residents with UK investment income, the 📖 disregarded income rules often matter more than the treaty.
Real-world examples
UK pension, living in Spain
Under the UK-Spain treaty, a UK private or workplace pension paid to a 📖 Spanish resident is taxable only in Spain. Once HMRC approves a treaty claim, the pension provider pays it with no UK tax deducted, and it is declared in Spain.
👉 GOV.UK: UK-Spain double taxation convention
👉 The law: The Double Taxation Relief and International Tax Enforcement (Spain) Order 2013
UK rental property, living in Australia
An 📖 Australian resident with a UK buy-to-let pays UK tax on the rental profit first, usually through the 📖 non-resident landlord scheme and a UK return. Australia taxes the same profit and gives a credit for the UK tax.
👉 GOV.UK: UK-Australia double taxation convention
👉 The law: The Double Taxation Relief (Taxes on Income) (Australia) Order 2003
What if there is no treaty?
You are usually not stuck with double tax. The UK gives unilateral foreign tax credit relief to UK residents for foreign tax on foreign income and gains, even where no treaty exists. The same cap applies: the credit cannot exceed the UK tax on that income.
Where a treaty does exist, the credit is limited to the tax the treaty allows. If a country withholds more than the treaty rate, you reclaim the excess from that country.
👉 HMRC helpsheet: HS263 Calculating foreign tax credit relief on income
👉 The law: Taxation (International and Other Provisions) Act 2010, section 18 (foreign tax credit)
How to claim treaty relief
How you claim depends on which side you are claiming from:
➜ Non-resident, UK income taxed at source: use form DT-Individual, certified by the tax authority where you live, so a UK pension or other UK income is paid gross or at the treaty rate. Some countries have their own version of the form.
➜ Non-resident filing a UK return: claim the treaty relief on the SA109 residence pages, using helpsheet HS304 to work out the figures.
➜ UK resident with foreign income: declare the income on the foreign pages of your return and claim foreign tax credit relief there.
➜ UK resident facing foreign withholding: get a certificate of residence from HMRC and give it to the overseas payer or tax authority, to reduce tax at source or reclaim the excess.
Claims have time limits, usually four years from the end of the tax year for UK claims. Overseas reclaim deadlines vary by country. For every form in one place, see our guide to 📖 HMRC forms for expats.
👉 HMRC form: DT-Individual double taxation treaty relief
👉 HMRC helpsheet: HS304 Non-residents, relief under double taxation agreements
👉 The law: Taxation (International and Other Provisions) Act 2010, section 6 (effect of treaty relief)
👉 HMRC guidance: Apply for a certificate of residence
What a treaty does not do
Three limits come up again and again:
➜ It does not change your SRT status: being treaty resident elsewhere limits what the UK can tax, but you can still be UK resident for other purposes, such as the 📖 FIG regime and inheritance tax.
➜ It does not remove filing: you often still need a return to claim the relief.
➜ It does not always switch off the five-year rule: treaty-exempt pension lump sums and gains can still be caught by the 📖 temporary non-residence rules if you return within five years.
US citizens have an extra layer because the US taxes on citizenship. See our guide to the 📖 UK-US double tax treaty.
Frequently asked questions
How do UK double tax treaties work?
A UK double tax treaty allocates taxing rights between the UK and another country. Depending on the income, it gives one country the only right to tax, caps the rate the source country can charge, or lets both countries tax with a credit in your country of residence. Relief is not automatic: you claim it on a tax return, on form DT-Individual or with a certificate of residence.
How many double tax treaties does the UK have?
The UK's treaty network covers more than 130 jurisdictions, one of the largest in the world. Each treaty is published on GOV.UK, along with any protocols that update it.
Is double tax relief automatic?
No. You must claim it, either on a tax return, on a form such as DT-Individual, or by giving a certificate of residence to an overseas payer. Claims have time limits, usually four years for UK claims.
Which country taxes my UK pension if I live abroad?
Under most UK treaties, a private or workplace pension is taxable only in your country of residence. A government service pension is usually taxable only in the UK. The State Pension depends on the specific treaty.
What is foreign tax credit relief?
It is a credit against UK tax for foreign tax paid on the same income or gain. The credit is limited to the UK tax on that income and to the rate the treaty allows the other country to charge.
Can I get relief if there is no treaty?
Usually, yes. UK residents can claim unilateral foreign tax credit relief for foreign tax on foreign income and gains, subject to the same limits as treaty credit relief.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Taxation (International and Other Provisions) Act 2010, Part 2, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us plan your international tax position
We plan your residence, timing, reliefs and treaty position, then handle the claims and returns that put it into effect. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ Residence status planned under the Statutory Residence Test
➜ Asset and gain timing around the residence line
➜ Treaty and double tax planning, including foreign tax credits
➜ Claims and returns filed, including treaty claims and the SA109
Typical fee
£1,000 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico