
Are you dreaming of swapping British drizzle for the Mediterranean, the Algarve, or somewhere further afield? For many, retiring abroad is the reward after decades of working life in the UK. The lifestyle change may be refreshing, but your tax obligations do not disappear when you hand over your passport at the departure gate.
If you are planning to relocate permanently, review your pension position before you go. Failing to keep your affairs straight with HMRC can lead to unexpected bills or, just as often, to missing reliefs you were entitled to. The sensible approach is a clear roadmap for your pension income before you move.
The starting point: UK-sourced income
The most common misconception among retirees is that moving abroad severs all tax ties with the UK. The fundamental rule is that HMRC retains the right to tax UK-sourced income wherever the recipient lives. If your pension was built up in a UK scheme, it remains UK-sourced.
That applies across the range of retirement income:
● The UK state pension.
● UK occupational pensions from former employers.
● Personal pensions, including a self-invested personal pension.
Leaving the UK does not, on its own, take your UK pension out of UK tax.
The pension commencement lump sum
One significant advantage is that you can still take your 25% pension commencement lump sum as a non-resident, and in the eyes of the UK it remains tax-free.
⚠️ WARNING A word of caution. The UK may not tax the 25%, but your new country of residence might. If you become tax resident somewhere that does not recognise the UK tax-free status, you could face local tax on the entire amount. The timing of when you take the lump sum is critical, and in many cases it is better taken before you leave the UK.
Double taxation agreements
Depending on where you become tax resident, it may be possible to remove the UK’s right to tax your pension income altogether, through a double taxation agreement. These are treaties between two countries designed to ensure the same income is not taxed twice.
In many cases a treaty shifts the taxing right exclusively to the country where you are resident. The UK has one of the largest treaty networks in the world, with over 120 agreements in place. Because each one is negotiated individually, the rules vary considerably from country to country.

Image 1 — the same pension, two destinations
Spain
If you move to Spain, the treaty allows you to exempt private and state pension income from UK tax, making it taxable only in Spain.
Thailand
The treaty with Thailand is structured differently. It does not allow you to exempt private or state pension income from UK tax, so HMRC retains the taxing right. Two popular destinations, and entirely opposite answers.
🌐 UKs double tax treaty network
The public sector exception
There is a specific and often frustrating caveat for public sector pensions. Where your pension derives from government service, which typically covers the NHS, the police, the armed forces and local government, the UK almost always retains the taxing right.
Under most treaties these pensions remain taxable only in the UK regardless of where you live. The exception is where you become a national of the country you are resident in, at which point it may be possible to shift the taxing right to that country.
Do you even need a treaty claim?
Before going further, it is worth checking whether you need the exemption at all.
If you are a UK or EEA national you keep your UK personal allowance while non-resident. For a retiree whose UK pension income sits below or close to that allowance, there may be little or no UK tax to relieve in the first place, and the administrative effort of a treaty claim may not be worth it.
Where the pension is larger, or where you also have UK rental or investment income using up the allowance, the treaty route becomes far more valuable.
How to exempt pension income from UK tax
If the treaty for your new country does allow an exemption, there are two routes to stopping HMRC taxing the income.
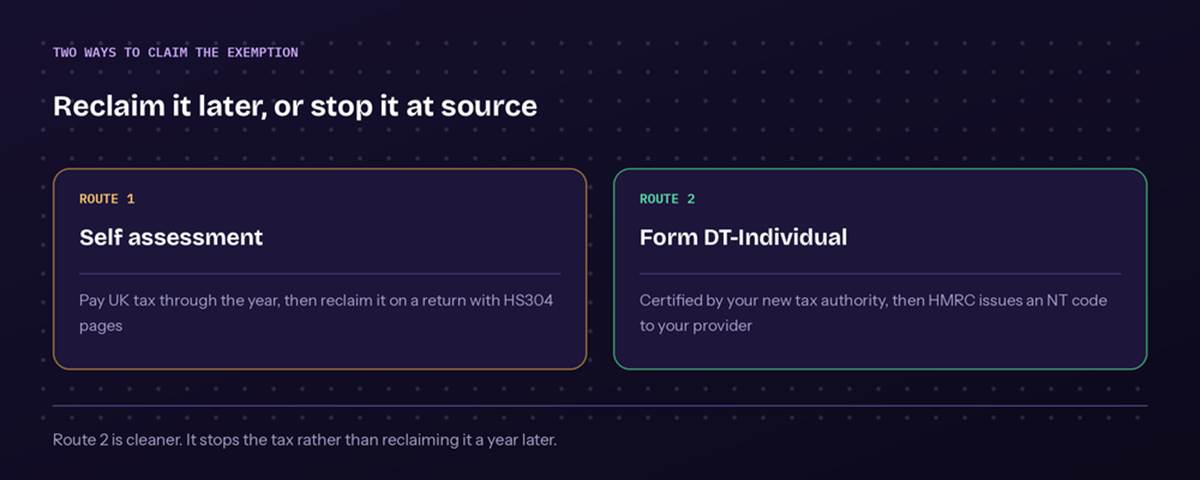
Image 2 — the two routes to relief
1. The self assessment route
You pay the UK tax through the year and reclaim it after the tax year ends, by filing a UK tax return including the HS304 pages to claim relief under the treaty.
2. The treaty relief form
The more efficient method is to submit a form DT-Individual, which is posted to the tax authority in your new country. They certify that you are tax resident there, the form goes to HMRC, and HMRC issues an NT, or no tax, code to your pension provider. That instructs the provider to pay the income without deducting UK tax at source.
Note that some countries have their own tailored version of the form, so it is worth searching for a UK and country specific treaty relief form before using the general one.
If you return to the UK within five years
One point that catches people out. Pension income you exempted from UK tax under a treaty is within the temporary non-residence rules.
⚠️ WARNING If you leave the UK, take pension income free of UK tax under a treaty, and then return within five years, that income comes back into charge in the tax year you resume UK residence. Retiring abroad for a few years and then coming home is precisely the pattern the rule is designed to catch.
Strategic planning for your retirement
Research the destination thoroughly before committing. The tax consequences of the choice can mean a difference of thousands of pounds in disposable income every year.
With planning you can often structure your affairs to reduce your overall tax burden significantly. Some countries offer exemptions or flat rates for retirees which, paired with a favourable UK treaty, create a genuinely efficient position.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated