
Key points
Thailand has two quirks: it taxes foreign income when you bring it in, and the treaty does not cover pensions.
✓ You are Thai tax resident if you spend 180 days or more in Thailand in a calendar year, whatever visa you hold.
✓ Since 1 January 2024, foreign income you bring into Thailand while resident can be taxed. Income earned before 2024 can be brought in without Thai tax.
✓ HMRC will not issue an NT code for Thai residents, so UK pensions stay taxed in the UK. British nationals keep the UK personal allowance.
✓ The UK State Pension is frozen for people living in Thailand.
✓ UK rent, UK workdays and gains on UK property stay in the UK tax net.
Moving to Thailand from the UK is popular with retirees and remote workers, and it has two tax quirks that most destinations do not. Thailand taxes foreign income when you bring it into the country, not when you earn it. And the UK-Thailand treaty has no pensions article, so your UK pension does not simply move to Thai tax.
Leaving the UK does not end your UK tax either. HMRC keeps taxing UK pensions, UK rental income, UK workdays and gains on UK property after you have gone.
This guide covers when Thailand treats you as resident, how the remittance rules work since 2024, how to break UK residence, what HMRC still taxes, how UK pensions are taxed in both countries, and the UK filings for the year you move.
When do you become tax resident in Thailand?
What makes you Thai tax resident? One test: you spend 180 days or more in Thailand in a calendar year. The days do not have to be in a row, and each year stands on its own. Your visa does not decide it, so a retirement visa, an Elite visa or a Destination Thailand Visa can all lead to residence if you stay long enough.
Residence alone does not make your foreign income taxable in Thailand. What triggers Thai tax on foreign income is bringing it into the country.
How does Thailand tax money you bring in?
Until the end of 2023, foreign income was only taxed if you brought it into Thailand in the same year you earned it. Waiting until the next January made it tax-free. From 1 January 2024, that gap closed.
➜ Income earned from 2024 while Thai resident: taxed in the year you bring it in, whichever year that is, at progressive rates from 0% to 35%.
➜ Money earned before 1 January 2024: can be brought in without Thai tax. The hard part is proving it, so keep old statements.
➜ Mixed accounts: a transfer from an account holding both old savings and new income can be treated as new income. Keep pre-2024 savings in a separate account.
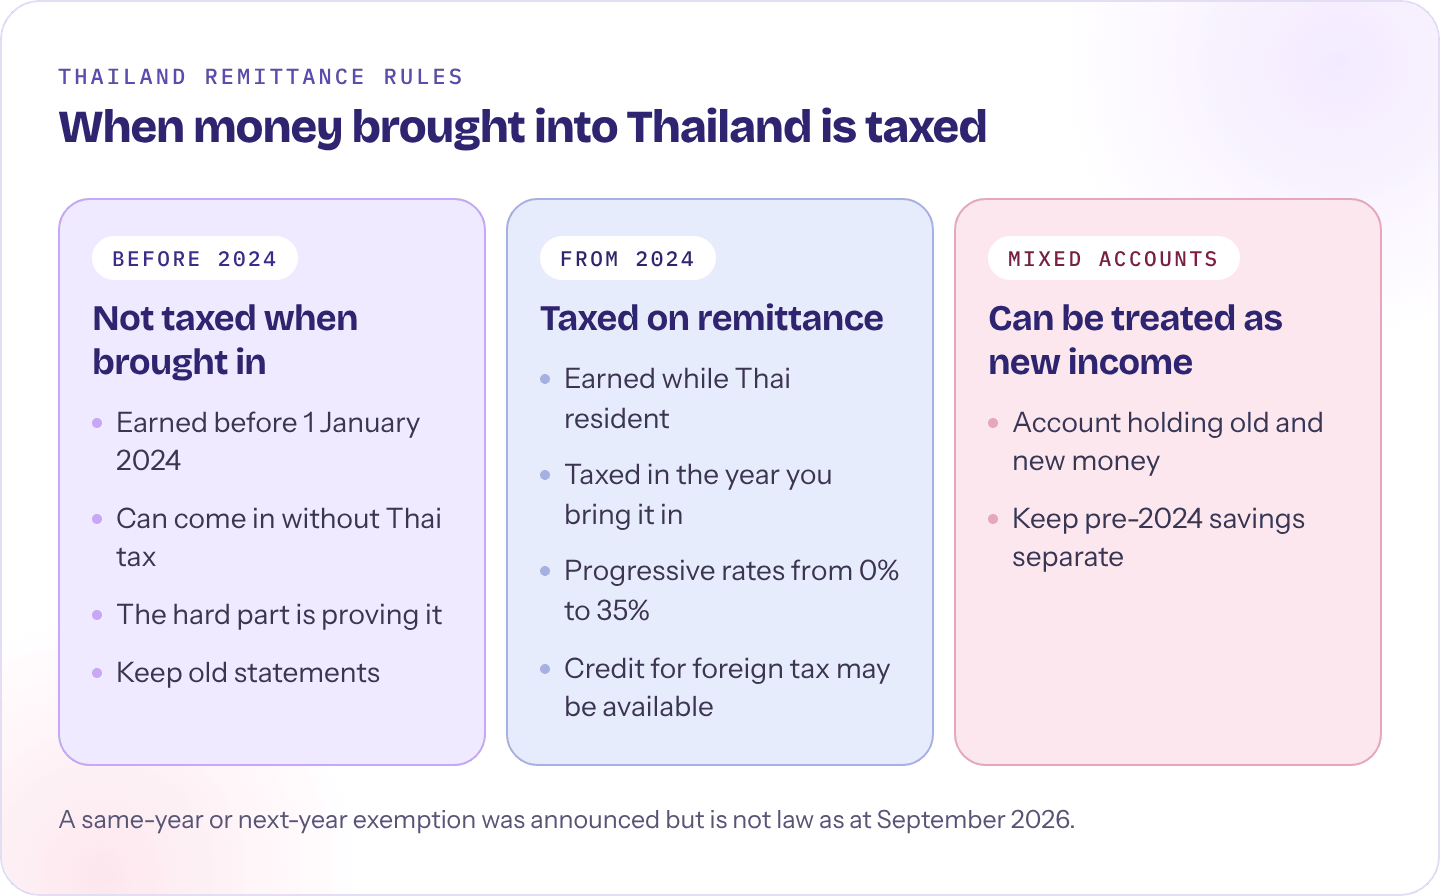
Image 1: when money brought into Thailand is taxed
When the money was earned | Thai tax when you bring it in | What to know |
|---|---|---|
Earned before 1 January 2024 | Not taxed | Savings built up before 2024 can be brought into Thailand without Thai tax. The hard part is proving it. |
Earned from 2024 while Thai resident | Taxed on remittance | Taxed in the year you bring it in, whichever year that is, at 0% to 35%. Credit for foreign tax may be available. |
Mixed accounts | Keep records | A transfer from an account holding old and new money can be treated as new income. Keep pre-2024 savings separate. |
Same-year or next-year exemption | Draft, not law | An exemption for income brought in the year it is earned or the year after has been announced but not enacted (as at September 2026). Do not plan around it yet. |
You may have read that income brought in during the year it is earned, or the year after, will be exempt. The Revenue Department announced that plan in 2025, but as at September 2026, it is still a draft and not law. Do not plan around it until it is enacted.
Some Long-Term Resident (LTR) visa categories come with an exemption for foreign income brought into Thailand. The Destination Thailand Visa does not. If you are Thai resident and bringing in taxable income, you will need a Thai tax ID and a return filed by the end of March, with a short extension for online filing.
👉 Thai Revenue Department: personal income tax for individuals
How do you stop being UK resident?
Does moving to Thailand make you non-resident in the UK? Not by itself. HMRC applies the Statutory Residence Test to each tax year separately, and a Thai visa makes no difference to it.
➜ Automatic overseas tests: fewer than 16 UK days if you were UK resident in any of the previous three tax years, fewer than 46 if you were not, or full-time work abroad with fewer than 91 UK days and fewer than 31 UK workdays.
➜ Sufficient ties test: if no automatic test settles it, HMRC weighs your UK days against your UK ties.
➜ The country tie: if you spend more midnights in the UK than in any other single country, that is a tie. People who split their year between Thailand, Vietnam and Bali trip this more than anyone.
➜ Split-year treatment: in the year you leave, the year can be split into a UK part and an overseas part, if one of the statutory cases applies.
See our guides to the 📖 Statutory Residence Test and 📖 split-year treatment.
👉 HMRC guidance: RDR3 Statutory Residence Test
👉 The law: Finance Act 2013, Schedule 45 (statutory residence test)
What does HMRC still tax once you have moved?
Which UK income stays in the UK tax net? Broadly anything with a UK source:
➜ UK pensions: workplace and personal pensions stay UK-taxable (see the next section).
➜ UK workdays: salary for days you physically work in the UK.
➜ UK rental income: taxed in the UK first. Register for the 📖 Non-Resident Landlord Scheme to receive rent without tax deducted. Rates on property income rise by two percentage points from 6 April 2027.
➜ Savings interest and dividends: for most non-residents, the 📖 disregarded income rules cap UK tax at whatever was deducted at source, which is often nil.
➜ Gains on UK property: taxed in the UK whatever your residence.
British nationals keep the £12,570 UK personal allowance wherever they live. See 📖 what the UK taxes after you leave for the wider picture.
How are UK pensions taxed in Thailand?
Here is where Thailand differs from Spain, Portugal, the UAE and Australia. The 1981 UK-Thailand treaty has no pensions article and no "other income" article. HMRC's position is that there is no treaty relief for UK pensions, lump sums or the State Pension, so they stay taxable in the UK.
➜ Workplace and personal pensions: the UK keeps taxing them through PAYE. There is no NT code to apply for, so form DT-Individual does not help. Thailand can also tax what you bring in, and you claim a credit for the UK tax in your Thai return.
➜ Government service pensions: civil service, armed forces and police pensions are taxable only in the UK under Article 19, unless you are a Thai national living in Thailand.
➜ UK State Pension: it is UK-taxable, but as a non-resident it can fall within the disregarded income rules. It is frozen at the rate you first receive in Thailand, so it will not rise each April.
➜ Lump sums: the 25% tax-free lump sum stays tax-free in the UK. Thailand may tax it if you bring it in while resident, so take advice on timing.

Image 2: why Thailand is different for UK pensions
Point | Spain, Portugal, UAE, Australia | Thailand |
|---|---|---|
What the treaty says | The treaty gives private pensions to your new country | No pensions article and no other income article |
UK tax | Apply to HMRC for an NT code and your provider stops deducting UK tax | The UK keeps taxing under PAYE, with no NT code. British nationals keep the UK personal allowance |
Result | Taxed once, where you live | Thailand taxes what you remit, with a credit for UK tax claimed in Thailand |
Government pensions | Not covered in the image | Civil service, armed forces and police pensions are taxed only in the UK under Article 19, unless you are a Thai national living in Thailand |
Worked example: Working out the UK tax
David, 67, lives in Chiang Mai and is non-resident for 2026/27. He has a £24,000 workplace pension and a £12,000 State Pension.
On the normal basis, his taxable income is £36,000 less his £12,570 personal allowance, which leaves £23,430 taxed at 20%. His UK tax is £4,686.
On the disregarded income basis, his State Pension drops out but he loses his personal allowance, so the whole £24,000 workplace pension is taxed at 20%. That is £4,800.
HMRC charges the lower of the two, so David pays £4,686. The disregarded basis only wins when most of your UK income is disregarded.
When David brings pension income into Thailand, it is assessable there too, and he claims a credit for the UK tax against the Thai tax on it. See 📖 UK pension tax when living abroad for how other treaties compare.
👉 HMRC helpsheet: HS300 Non-residents and investment income
👉 The law: Income Tax Act 2007, section 811 (limit on liability of non-residents)
Selling your UK home after moving to Thailand
Planning to sell your former home once you have gone? Non-residents pay UK capital gains tax on UK property. For 2026/27, the annual exempt amount is £3,000, and residential gains are taxed at 18% within your remaining basic rate band and 24% above it.
➜ Private residence relief: covers the years it was your main home, plus the final nine months of ownership.
➜ April 2015 rebasing: if you owned the property on 5 April 2015, you can usually use its value at that date.
➜ 60-day deadline: report the sale and pay any tax within 60 days of completion, even if there is nothing to pay. With a six or seven hour time difference and conveyancing happening without you, get the figures ready before exchange.
Thailand can tax the gain if you are Thai resident when you sell and you bring it in. Keep the completion statement so you can separate your original capital from the gain. Our 📖 non-resident capital gains tax guide covers the UK calculation.
👉 GOV.UK: report and pay capital gains tax on UK property
👉 The law: Finance Act 2019, Schedule 2 (returns for disposals of UK land)
UK-Thailand double tax treaty: what it actually does
If it does not cover pensions, what does it cover? It still matters for other income:
➜ Rental income: the UK taxes UK property income first, and Thailand gives credit if it taxes the same income.
➜ Dual residence: it has tie-breaker rules for years when both countries treat you as resident. See 📖 dual tax residency.
➜ A limitation you will not see elsewhere: under Article 6, where the treaty relieves UK tax on income that Thailand only taxes when remitted, the UK relief only covers the amount you actually bring into Thailand.
For how exemption, rate limits and credits work across treaties, see 📖 double tax treaties: how relief works.
👉 GOV.UK: UK-Thailand double taxation convention
👉 The law: The Double Taxation Relief (Taxes on Income) (Thailand) Order 1981
👉 HMRC manual: UK-Thailand treaty Article 6, limitation of relief (DT18705)
What else changes: State Pension and inheritance tax
What happens to the rest of your UK position?
➜ State Pension: frozen at the rate you first receive in Thailand, or the rate when you move if you are already claiming it. Over a long retirement, the gap adds up.
➜ Inheritance tax: if you have been UK resident for at least 10 of the last 20 tax years, your worldwide estate stays within UK inheritance tax for 3 to 10 years after you leave. From 6 April 2027, most unused pension funds come into the calculation too.
👉 GOV.UK: State Pension if you retire abroad
👉 HMRC guidance: inheritance tax if you are a long-term UK resident
👉 The law: Inheritance Tax Act 1984, section 6A (long-term UK resident)
What if you come back within five years?
Is the move permanent? If you were UK resident in at least four of the seven tax years before you left, and you return within five years, the 📖 temporary non-residence rules can tax some income and gains in the year you come back:
➜ Close company dividends: from 6 April 2026, this includes dividends paid from profits earned after you left.
➜ Gains on assets owned before you left: such as shares, taxed as if made in the year you return.
➜ Some pension withdrawals: flexible drawdown and lump sums taken while abroad, where they escaped UK tax.
Your UK checklist for the year you move
Keep a day log for the UK, Thailand and every other country you spend time in.
Tell HMRC you have left. Use form P85 if you will not be filing a return, or the SA109 residence pages if you will.
Check your pension tax codes. There is no NT code for Thailand, so make sure your provider is using a code with your personal allowance, not an emergency code.
Separate your savings. Keep pre-2024 money in its own account before you start moving funds to Thailand.
Register as a non-resident landlord if you are letting your UK home.
File by 31 January 2028 for 2026/27. HMRC's free online service cannot file the SA109, so you will need commercial software or an adviser.
For the wider move, see how we help people leaving the UK, and try our leaving the UK tax calculator before you go.
See 📖 HMRC forms for expats and 📖 do I need to file a UK tax return.
👉 GOV.UK: check if you need to send a Self Assessment return
👉 The law: Taxes Management Act 1970, section 7 (notice of liability to tax)
How we help people moving to Thailand
Need UK tax advice before you move to Thailand? Global Tax Consulting advises people leaving the UK for Thailand on their UK tax position before they go: when UK tax residence ends under the Statutory Residence Test, split-year treatment, what the UK still taxes after you leave, and the temporary non-residence rule if you return within about five years. All advice is reviewed and signed off by Emma McDermott, ATT. A leaving the UK exit plan typically costs £1,000 to £4,000, fixed before work starts.
Frequently asked questions
Is my UK pension taxed in Thailand or the UK?
Potentially both. The UK-Thailand treaty has no pensions article, so the UK keeps taxing workplace and personal pensions. Thailand can also tax pension income you bring in while Thai resident, with a credit for the UK tax.
Can I get an NT code for my pension if I live in Thailand?
No. Because the treaty does not cover pensions, HMRC will not issue an NT code for Thai residents. British nationals still get the UK personal allowance against their pension.
Is money I saved before 2024 taxed when I bring it to Thailand?
No. Income earned before 1 January 2024 can be brought into Thailand without Thai tax. Keep records that prove when it was earned, ideally in a separate account.
How many days make me tax resident in Thailand?
180 days or more in a calendar year, counted in total rather than in a row. Residence is decided year by year, whatever visa you hold.
Will my UK State Pension go up if I live in Thailand?
No. The UK State Pension is frozen for people living in Thailand, so it stays at the rate you first receive there.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Finance Act 2013, Schedule 45 and The Double Taxation Relief (Taxes on Income) (Thailand) Order 1981, and the HMRC guidance cited above.
How Global Tax Consulting can help
Plan your move before you go
Our exit plan establishes your residence position, times your departure and disposals, and plans for the five-year return window. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ Your residence position established for the year you leave
➜ Departure and disposals timed around the residence line
➜ Split-year treatment and the five-year return window planned
➜ Treaty claims and returns handled when it is time to file
Typical fee
£1,000 to £4,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico