
Are you planning to move your life across borders part way through a tax year?
Under normal circumstances the Statutory Residence Test treats residence as a binary state. You are either UK resident for the whole year or you are not. The UK tax system does, however, offer a mechanism known as split year treatment.
If you meet the criteria for one of the cases, you can divide the tax year into a resident part and a non-resident part, limiting HMRC’s taxing rights for part of the year in line with your actual travel pattern.
There are eight cases in total. Three apply when you leave the UK and five when you arrive.
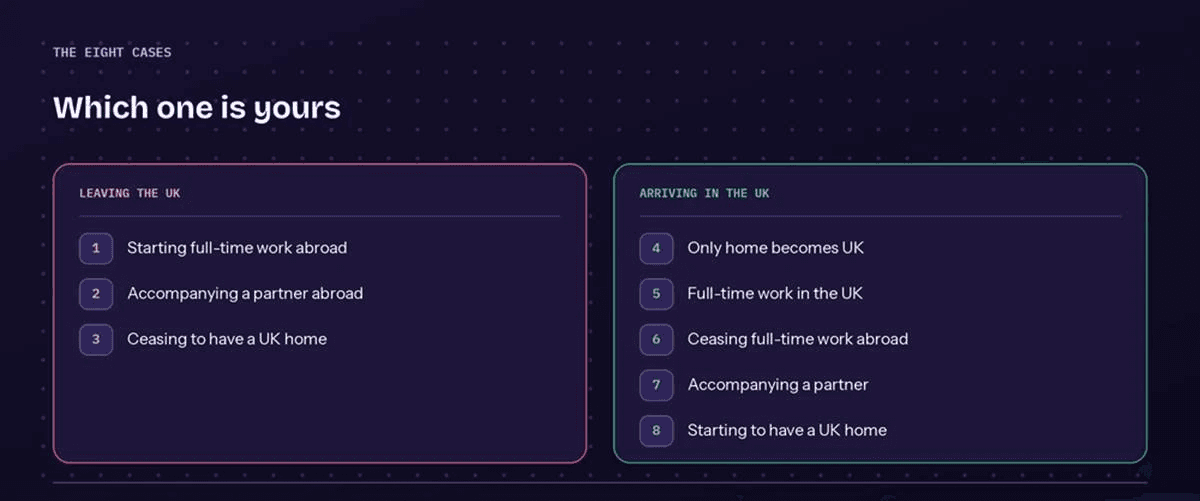
Image 1 — the eight cases
Leaving the UK
When you move abroad, the usual objective is to stop being UK tax resident from the day you go. Without split year treatment you could remain UK resident on your worldwide income until the following 5 April, even though you are already living and working elsewhere. Three cases apply on departure.
Case 1: Starting full-time work abroad
This is the most common scenario for expatriates, and it can be met by working remotely for a UK company. To qualify:
● You were resident in the previous tax year.
● You will be non-resident in the following tax year.
● You work at least 35 hours overseas per week, without significant breaks, to the end of the following tax year.
● Your midnights and workdays in the UK stay within the limits. For the year of departure this depends on when you leave, and for the following tax year the limits are 90 midnights and 30 workdays.
Case 2: Accompanying a partner abroad
Case 2 applies where you leave the UK to join a spouse, civil partner or cohabiting partner who qualifies for split year treatment under Case 1. It exists so that the accompanying partner is not left resident for the full year simply because they are not the one starting the overseas job.
Case 3: Ceasing to have a UK home
If you are moving abroad but will not be in full-time work, for example on retirement, Case 3 is usually the relevant one. To qualify:
● You were resident in the previous tax year.
● You will be non-resident in the following tax year.
● You give up your home in the UK and do not have access to a UK home for the rest of the tax year.
● You are present in the UK at midnight on no more than 15 days, from the day you give up the home to the end of the tax year.
● You acquire a sufficient link with an overseas country within six months of giving up the home.
⚠️ WARNING Your split year claim depends on being non-resident in the following tax year. If you return to the UK too soon, HMRC will retrospectively withdraw the split year treatment, and the tax that was never charged becomes payable in full.
Moving to the UK
For people moving to the UK, split year treatment is equally valuable. It prevents the UK taxing income you earned abroad before you set foot in the country. Five cases apply on arrival.
Case 4: Starting to have an only home in the UK
This applies where your only home becomes a UK one on relocation. To qualify:
● You were non-resident in the previous tax year.
● At some point in the tax year your only home is in the UK, and it remains available to you at least to the end of that tax year.
● During the non-resident part of the year, your UK ties and UK midnights stay below a threshold set by the month in which you begin to meet the test.
Case 5: Starting full-time work in the UK
This applies where you begin full-time work in the UK on relocation. To qualify:
● You were non-resident in the previous tax year.
● At some point in the tax year you begin a period of full-time work in the UK lasting at least 365 days.
● During the non-resident part of the year, your UK ties and UK midnights stay below the threshold for the month concerned.
Case 6: Ceasing full-time work abroad
This applies where you repatriate within five years of leaving, having been non-resident on the basis of full-time work overseas. To qualify:
● You were non-resident in the previous tax year through the full-time work abroad criteria, being the third automatic overseas test.
● You were resident in one or more of the four tax years preceding that previous tax year.
● During the non-resident part of the year, your UK midnights and UK workdays stay below the threshold for the month concerned.
● You will be resident in the following tax year.
Case 7: Accompanying a partner to the UK
Case 7 is the arrival equivalent of Case 2. It applies where you come to the UK to join a partner who qualifies for split year treatment under Case 6, having ceased full-time work abroad.
Case 8: Starting to have a home in the UK
This applies where you begin to have access to a UK home during the tax year. To qualify:
● You were non-resident in the previous tax year.
● At some point in the tax year you acquire access to a UK home, and it remains available to you at least to the end of the following tax year.
● During the non-resident part of the year, your UK ties and UK midnights stay below the threshold for the month concerned.
● You will be resident in the following tax year.
When arriving in the UK, the period between 6 April and the date your split year begins needs careful monitoring. Keep track of the number of days you spend in the UK, the number of workdays you exercise here, and the number of ties you have, such as family, accommodation or work.
Failing to manage those variables can result in you being treated as UK resident for the whole tax year, which exposes your pre-arrival foreign income to UK tax.
Claiming the treatment: compliance and evidence
It is a common misconception that split year treatment is a simple box to tick. The claim is actually made on the SA109 pages of the self assessment return, where you notify HMRC of your arrival or departure date and specify which case applies.
Because split year treatment is an exception to the general rule of full year residence, it attracts scrutiny. Keeping thorough evidence is not optional. If HMRC asks you to substantiate the claim, be ready to provide:
● Travel records, including boarding passes and hotel bookings.
● Employment contracts setting out overseas or UK working hours.
● Lease agreements, or completion of sale documents, for your homes.
● Utility bills or bank statements showing where you were actually spending.
Note that the SA109 pages cannot be submitted through HMRC’s free online filing service. You will need commercial software, or an adviser, to file them alongside the main return.
The importance of precise timing
Split year treatment is the most effective tool available if you are mobile during a tax year. It lets you keep foreign income outside the UK system for the periods you were genuinely living abroad. The rules are rigid, though. There is no equitable middle ground. You either meet the conditions of a specific case or you do not.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated