
Key points
Once you are non-resident, HMRC can only tax salary for work you physically do in the UK.
✓ Split-year Case 1 depends on where you physically work, not where your employer is.
✓ Under the full-time work abroad test you need fewer than 31 UK workdays and fewer than 91 UK days.
✓ Bonuses and equity are sourced to when they were earned, so pay for UK-resident work can stay taxable after you leave.
✓ Form P85 lets HMRC issue an NT code to your employer. Or reclaim overpaid PAYE through the SA109.
✓ UK and EEA nationals keep the UK personal allowance while non-resident.
Working remotely abroad for a UK company is no longer unusual, and digital nomads are only part of the picture. Your lifestyle may be flexible, but your UK tax position is not. Before you go, you need to know how HMRC will treat your residence status, your salary, and any bonus or equity that lands after you have left.
This guide covers UK personal tax for employees working remotely for a UK employer. It does not deal with tax in your new country, immigration, or your employer's corporate obligations, though we flag where those matter.
The key question is simple. If you leave the UK, when does HMRC stop taxing your salary?
Watch: Working Abroad for a UK Employer? You May Be Owed a Tax Refund
Split-year treatment: when non-resident treatment starts
Why does residence matter so much? Because once you are non-resident, HMRC can only tax the salary for work you physically do in the UK. Getting to non-resident status, and getting the timing right in the year you leave, is the turning point.
If you leave part-way through a tax year, you can be treated as non-resident from your first day of full-time work overseas under split-year Case 1: starting full-time work overseas. You can meet this even while working for a UK employer, because what matters is where you physically work, not where your employer is based or where you are paid.
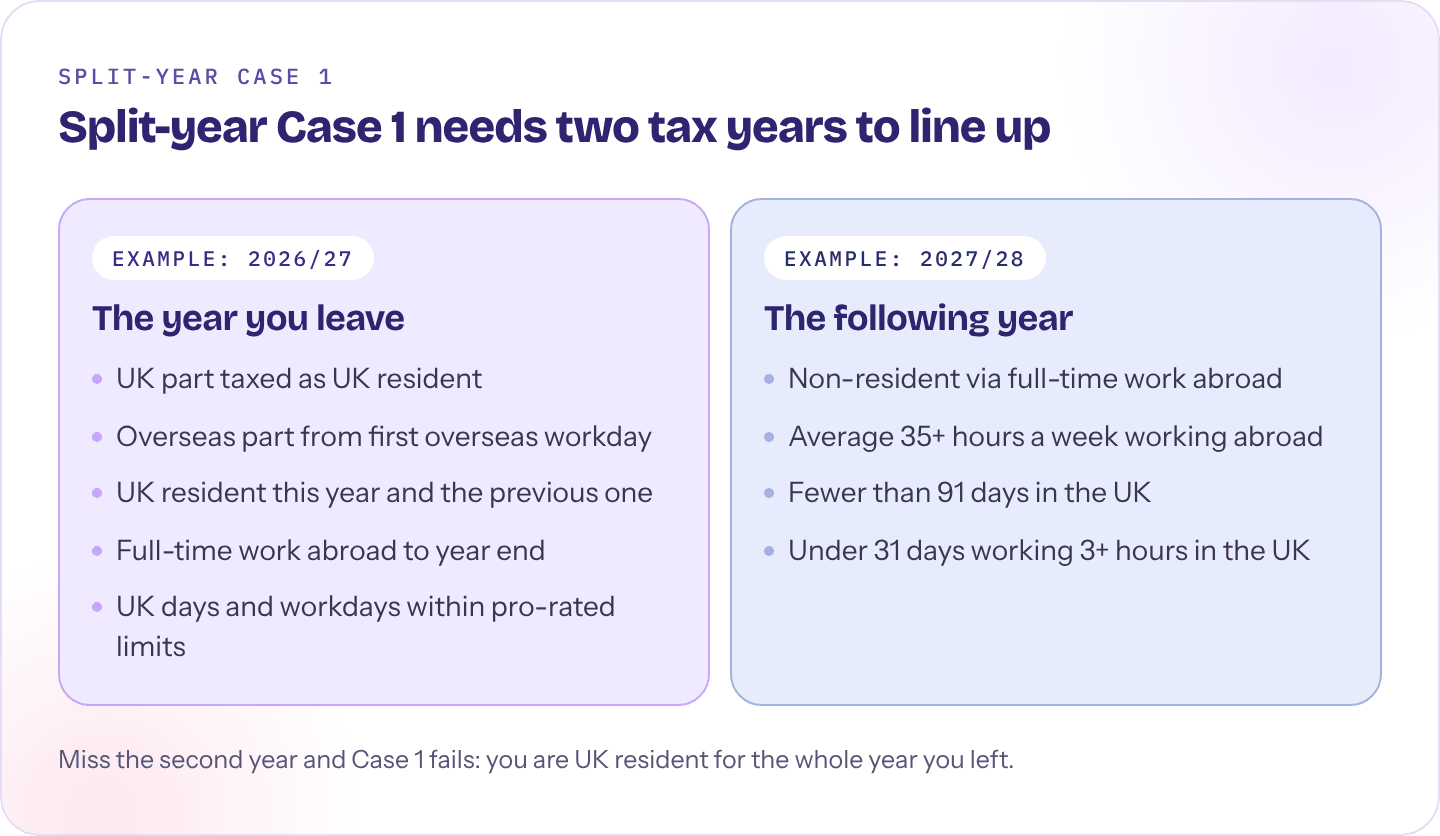
Image 1: split-year Case 1 needs two tax years to line up
Tax year | Your status | What you need |
|---|---|---|
Year you leave (for example 2026/27) | UK part taxed as UK resident, then an overseas part from your first overseas workday | UK resident for the year, and for the previous year. Full-time work abroad through the rest of the year. UK days and UK workdays within the pro-rated limits. |
The following year (for example 2027/28) | Non-resident via the full-time work abroad test | Average 35+ hours a week working abroad. Fewer than 91 days in the UK. Fewer than 31 days working 3+ hours in the UK. |
Miss the second year and Case 1 fails. Unless another case applies, you are UK resident for the whole year you left and taxed on your worldwide salary.
A critical point is often missed. To use Case 1, you must also be non-resident in the following tax year through the full-time work abroad test. In practice that means:
➜ working an average of 35 hours or more a week overseas, without significant breaks
➜ spending fewer than 91 days in the UK
➜ working more than three hours a day in the UK on fewer than 31 days
Fail that in the next year and Case 1 fails for the year you left. Unless another split-year case applies, you are UK resident for the whole departure year and taxed on your worldwide salary for it. In the departure year itself, the UK day and UK workday limits are reduced proportionally for the overseas part.
For later years, the most reliable approach is to keep meeting the full-time work abroad test by working full-time overseas and managing your UK days and workdays. See our 📖 guide to all eight split-year cases and our 📖 Statutory Residence Test 101.
👉 HMRC guidance: RDR3 Statutory Residence Test (including split years)
👉 The law: Finance Act 2013, Schedule 45 (statutory residence test)
How your salary is sourced once you are non-resident
Where is your salary taxed if you are non-resident? For UK purposes, employment income is sourced to where the duties are physically performed. Under section 27 ITEPA 2003, a non-resident employee is only taxable in the UK on earnings for UK duties. HMRC looks at where you work, not where your employer is based or where your salary is paid.
Where you work partly in the UK and partly overseas, HMRC normally apportions your salary by workdays: UK workdays against total workdays in the period.
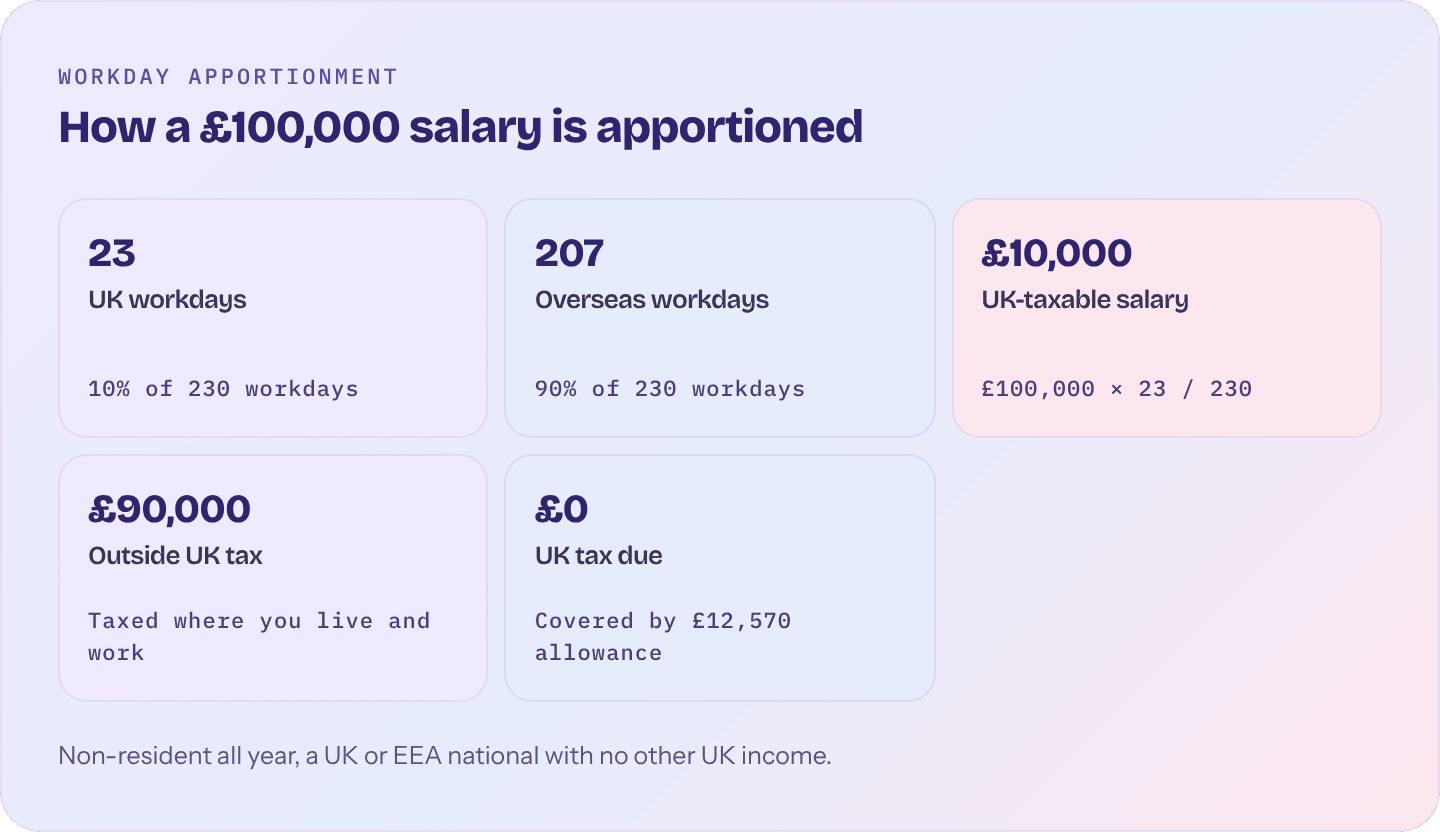
Image 2: how workdays are apportioned
£100,000 salary, 230 workdays, non-resident for the whole year | Figure |
|---|---|
UK workdays | 23 (10%) |
Overseas workdays | 207 (90%) |
UK-taxable salary | £10,000 (£100,000 × 23 / 230) |
Outside UK tax | £90,000, taxed where you live and work |
UK tax due | £0, covered by the £12,570 personal allowance for UK and EEA nationals with no other UK income |
➜ 10% of workdays in the UK: HMRC taxes the 10% UK portion only, provided you are non-resident.
➜ 0% of workdays in the UK: HMRC has no taxing right over your salary.
Duties in the UK that are "merely incidental" to your overseas job, such as a short briefing trip, can be treated as performed abroad, but that is a narrow exception. Most real work done here counts.
👉 HMRC manual: section 27 ITEPA 2003, UK duties of non-resident employees (EIM40110)
👉 The law: Income Tax (Earnings and Pensions) Act 2003, section 27 (UK duties of non-residents)
This is why record keeping matters. Keep travel records, work calendars and evidence of where your duties were performed. If HMRC asks, you will need to show it day by day.
Bonuses and equity: when are they taxable?
What about bonus payments, share awards or other deferred pay? They are not taxed by reference to the payment date alone. They are sourced to the period in which they were earned or vested. Leaving the UK does not automatically take a later payment out of UK tax.
Bonus example
➜ You are UK resident and working in the UK for the whole of the 2025 calendar year.
➜ You leave the UK on 1 January 2026 and become non-resident, with no UK workdays afterwards.
➜ In April 2026 you receive a bonus for your 2025 performance.
The bonus is wholly taxable in the UK, because it was earned entirely during your UK period. Being paid after you left does not change where it came from.
Equity example
➜ You are UK resident for the whole of the 2025 calendar year.
➜ You leave on 1 January 2026, become non-resident and do no UK work in 2026.
➜ RSUs granted on 1 January 2025 vest on 31 December 2026.
HMRC taxes roughly 50% of the value at vesting, being the half of the grant-to-vest period when you were UK resident. The other half, earned while working wholly overseas, is outside UK income tax. The date the shares are delivered is not decisive. The gain is sourced back to the period in which it was earned.
Equity has more traps than bonuses: graded vesting, option exercise timing and payroll withholding all change the answer. See our full guide to 📖 RSUs and share options after you leave the UK.
The personal allowance for non-residents
UK and EEA nationals keep the UK personal allowance while non-resident. Others may qualify under a double tax treaty.
In practice, that means there may be no UK tax at all on a small amount of UK-sourced income, such as a few UK workdays or a trailing bonus, because the allowance covers it.
👉 HMRC manual: personal allowance entitlement for non-residents (INTM334580)
👉 The law: Income Tax Act 2007, section 56 (non-residents who can claim allowances)
Using form P85 to stop UK tax on your salary
You can submit form P85 to tell HMRC you have left, that you are non-resident and that you are working full-time abroad. If HMRC accepts the facts, it may issue an NT (no tax) code to your employer, so your salary is paid without UK PAYE.
Three points to be aware of:
➜ Self Assessment filers usually report their departure on the tax return instead. But if you are working full-time abroad for a UK employer for at least a full tax year, HMRC's guidance asks for a P85 and a Self Assessment return with the SA109 residence pages.
➜ Some UK workdays? An NT code may not be appropriate, because PAYE still applies to the UK portion. A reduced code or year-end reconciliation may fit better.
➜ The P85 does not make you non-resident. Your status still comes from the Statutory Residence Test each year.
👉 HMRC guidance: Get your Income Tax right if you are leaving the UK (P85)
For a step-by-step walkthrough, read our 📖 P85 form guide.
The Self Assessment route
Some people leave payroll as it is during the tax year and deal with it afterwards through a UK tax return. PAYE may keep being deducted at first. You then file a return to:
➜ claim non-resident status
➜ apply split-year treatment where available
➜ report the correct UK workday allocation
➜ reclaim any excess UK tax deducted through payroll
This route suits you if your facts are still developing, if your employer will not change payroll mid-year, or if you want the final position reconciled in one place. HMRC's free online service cannot file the SA109 residence pages, so you will need commercial software or a paper return. See 📖 do I need to file a UK tax return? for the deadlines.
👉 HMRC guidance: Register for Self Assessment
What else to check before you go
Personal UK tax is only one piece. Before you start working abroad, check:
➜ Tax in your new country. It will usually tax your salary once you are resident there, and may require local payroll or withholding.
➜ Your employer's position. Having an employee working abroad can create payroll, employment law and permanent establishment questions for the company. Raise it with HR before you leave, not after.
➜ Digital nomad plans. If you will move between countries rather than settle in one, full-time work abroad and the country tie need extra care. See 📖 digital nomad tax and the 183-day myth.
If you would like all of that looked at together, see how we help digital nomads and remote workers.
Frequently asked questions
Do I pay UK tax if I work remotely abroad for a UK company?
It depends on your UK tax residence, not on who pays you. If you are still UK resident, the UK taxes your whole salary. If you are non-resident under the Statutory Residence Test, the UK generally taxes only the pay for days you work in the UK, so salary for work done wholly abroad is usually outside UK Income Tax. Your employer may keep deducting PAYE until HMRC issues an NT tax code, and you can reclaim what was overpaid. The country you live in may tax the salary too.
Can I get split-year treatment if my employer is in the UK?
Yes. Split-year Case 1 depends on where you physically work, not where your employer is. You must work full-time overseas for the rest of the departure year and meet the full-time work abroad test in the following tax year too.
How many days can I work in the UK while non-resident?
Under the full-time work abroad test, you need fewer than 31 days working more than three hours in the UK and fewer than 91 days in the UK in total. Those UK workdays remain taxable in the UK.
Is a bonus paid after I leave the UK taxable in the UK?
It can be. Bonuses are sourced to the period in which they were earned, so a bonus for work done while you were UK resident is taxable in the UK even if it has paid after you have left.
How do I stop PAYE on my salary after moving abroad?
Submit form P85 so HMRC can consider issuing an NT code to your employer. Alternatively, leave payroll unchanged and reclaim overpaid tax through a Self Assessment return with the SA109 residence pages.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Income Tax (Earnings and Pensions) Act 2003, section 27 and Finance Act 2013, Schedule 45, and the HMRC guidance cited above.
How Global Tax Consulting can help
Let us sort your UK position as a nomad
We advise digital nomads and remote workers on residence, income earned abroad and UK returns, fully online. Every piece of work is prepared and signed off by Emma McDermott, ATT.
➜ Split-year residency planning under the Statutory Residence Test
➜ Employment income abroad, including reclaiming PAYE already deducted
➜ Freelance and sole trade income advised on
➜ UK returns filed, including the SA100 and SA109
Typical fee
£1,000 to £4,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico