
For many years the UK’s tax treatment of arriving residents was defined by the complex and often contested remittance basis. From April 2025 that changed. If you are considering a move to the UK, or have recently arrived, you are entering a new regime built around foreign income and gains, known as FIG.
The FIG regime offers a powerful but time limited opportunity. If you meet the criteria, you get four tax years in which your foreign income and gains are entirely exempt from UK tax, whether or not you bring those funds into the country.
Understanding the detail is not simply about compliance. It is about making sure you do not leave significant savings on the table, and that you are not caught out when the window closes.
Understanding the four year FIG regime
The four year FIG regime is the centrepiece of the new rules. It is designed to attract high net worth individuals and skilled professionals by offering a simple and competitive tax position during their first years of UK residence.
Under the regime, qualifying individuals pay no UK tax on foreign income, such as overseas rental income or dividends, or on foreign capital gains, such as the sale of an overseas property or share portfolio.
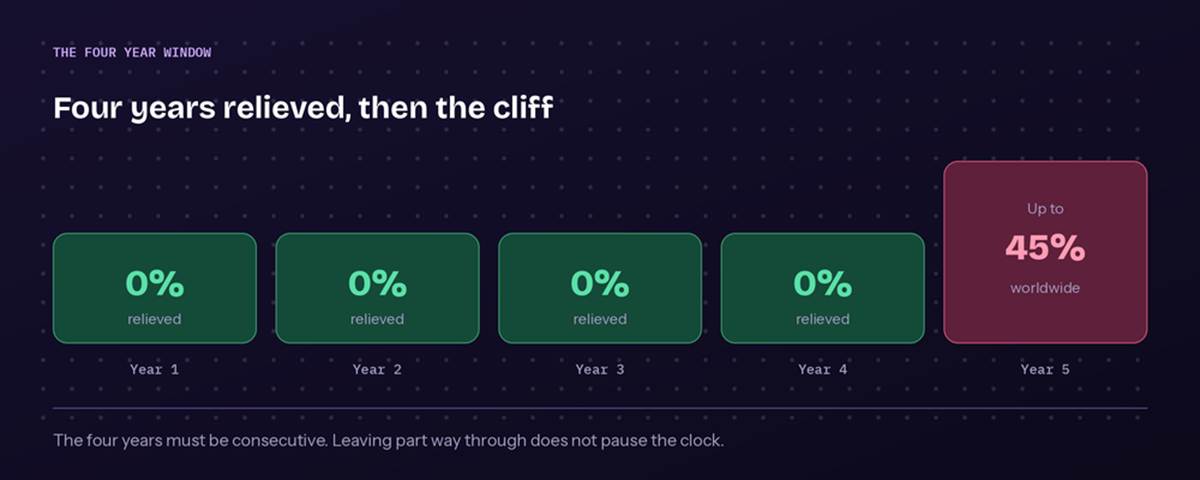
Image 1 — four relieved years, then the cliff
Do you qualify?
To use the FIG regime you must be a qualifying new resident, which means both of the following apply.
● You were non-UK tax resident for at least ten consecutive tax years immediately preceding the tax year you arrive in the UK.
● You are within your first four tax years of UK residence following that ten year period of non-residence.
The four years are consecutive tax years of UK residence. They are not four years of your choosing. If you leave the UK part way through the window, the clock keeps running, and any year you spend outside the UK is a year of relief you simply lose.
NOTE The point about the four years being consecutive is new. It is one of the most common misunderstandings about the regime and it costs people a full year of relief.
HMRC guidance on qualifying new resident conditions.
What claiming FIG costs you
Opting into the regime is not free. By making a FIG claim you give up your entitlement to the UK personal allowance of £12,570 and the capital gains annual exempt amount of £3,000 for that tax year.
As a result, the regime tends to suit those with substantial foreign income. If your overseas income is modest, the loss of your allowances can outweigh the relief you receive. Three broad scenarios illustrate the point.
● High foreign income, low UK income. Relief is likely to be beneficial. You shelter significant foreign earnings while losing an allowance you would not have fully used anyway.
● Moderate foreign income, full UK salary. The calculation becomes much tighter and is worth modelling both ways before you decide.
● Low foreign income. Claiming relief may actually increase your overall tax bill, because of the allowances you give up.
The choice is made year by year, so claiming in one tax year does not commit you to claiming in the next.
HMRC guidance on loss of personal allowance if you claim FIG.
The freedom of remittance
One of the most significant advantages of the FIG regime is that you can bring your money into the UK freely.
You can remit foreign income and gains to a UK bank account, use them to buy UK property, or invest them in UK businesses without triggering a further UK tax charge. That removes most of the administrative burden that made the old remittance basis so difficult to live with.
Employment income and Overseas Workday Relief
For many professionals moving to the UK, employment income makes up the bulk of their earnings. The FIG regime works alongside a revised version of Overseas Workday Relief, which is aimed at people who live in the UK but perform some of their employment duties abroad.
If you qualify for the FIG regime you are eligible for Overseas Workday Relief, which excludes the portion of your earnings relating to overseas workdays from UK taxation. Under the new rules that income no longer has to be kept offshore.
The relief is now subject to an upper limit. It is capped at the lower of 30% of your qualifying employment earnings, or an annual financial limit of £300,000.

Image 2 — how the Overseas Workday Relief cap works
By way of example, if your total qualifying earnings are £1,500,000, then 30% would be £450,000. Because of the annual cap, the maximum exempt amount is limited to £300,000.
HMRC guidance on Overseas workday relief.
The all or nothing rule for self employed income
While the regime is generous for investment income and employment income, it is far more restrictive for the self employed. If you run a business as a sole trader, the rule is all or nothing.
If the business activities are managed and performed wholly overseas, you can use the FIG regime to exempt the entire profits from UK taxation. However, if any of the business activities are managed or performed within the UK, the income is wholly subject to UK tax, even if you split your time between the UK and abroad.
In practice it is extremely difficult to reach a position where self employment profits fall outside UK tax, because living in the UK while running the business entirely from overseas is rarely realistic.
HMRC guidance on qualifying income for FIG.
Claiming FIG: the time limits
The FIG regime is not applied automatically. To benefit you must make a claim through your UK self assessment tax return, and missing the deadline means losing the relief for that year entirely.
The time limit for a FIG claim is the first anniversary of the 31 January following the end of the tax year to which the claim relates, which effectively gives you a twelve month window beyond the normal filing date. For the 2025/26 tax year that works as follows.
● Tax year ends 5 April 2026
● Normal filing deadline 31 January 2027
● FIG claim deadline 31 January 2028
The same limit applies to foreign income claims and foreign gains claims. While the extra twelve months gives you a buffer, we would advise against relying on it. Filing early gives a clearer picture of your longer term position and keeps the return consistent with your residence status.
One point that surprises people. Even where you claim FIG and pay no UK tax on the income, you still have to report those foreign income and gains to HMRC on the return. The relief is claimed, not automatic, and the disclosure is part of claiming it.
Transitioning beyond the four year mark
The FIG regime is powerful but temporary. Once you enter your fifth year of UK residence you are taxed on worldwide income and gains under the arising basis.
That transition is a genuine cliff edge. Without planning you may find yourself suddenly liable to tax at up to 45% on foreign income, or 24% on foreign gains, on amounts that were entirely exempt the year before.
Planning options to consider before the window closes include:
● Realising gains on assets while they remain relieved, which resets the base cost for the years that follow.
● Moving investments into tax efficient wrappers such as pensions or ISAs, which continue to shelter income and gains afterwards.
The time to look at this is during year three, not during year five.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated