
Key points
The TRF is a three-year window to clear old offshore income and gains at a flat rate instead of up to 45%.
✓ You must be UK resident in the year you designate and have been taxed on the remittance basis for at least one earlier year.
✓ The rate is 12% for 2025/26 and 2026/27 and 15% for 2027/28. The facility ends after 5 April 2028.
✓ The election deadlines are 31 January 2028, 31 January 2029 and 31 January 2030 for the three designation years.
✓ Designating is not remitting. The money can stay offshore and come to the UK later, or never.
✓ No foreign tax credit is given against the TRF charge, so a heavily taxed gain can cost less as an ordinary remittance.
✓ Paying the charge from undesignated offshore funds is itself a taxable remittance.
If you used the remittance basis as a non-dom, you may still hold foreign income and gains that have never been taxed in the UK. The Temporary Repatriation Facility (TRF) is a three-year window to clear them at a flat 12% or 15%, instead of up to 45%.
Once an amount is designated and the TRF charge is paid, you can bring it to the UK whenever you like, or never, with no further UK tax. For anyone planning to live, invest or spend in the UK, that can unlock years of trapped offshore money.
This guide covers who can use the TRF, what can be designated, the rates and real deadlines, the foreign tax trap and how to decide.
What is the Temporary Repatriation Facility?
The remittance basis ended on 5 April 2025. Before then, non-doms could leave foreign income and gains outside UK tax as long as they kept them offshore. Those pre-April 2025 amounts are still taxable if they are ever brought to the UK, at income tax rates of up to 45% or capital gains rates of up to 24%.
The TRF lets you pay a flat charge on them now instead:
➜ 12% on amounts designated for 2025/26 or 2026/27.
➜ 15% on amounts designated for 2027/28, the final year.
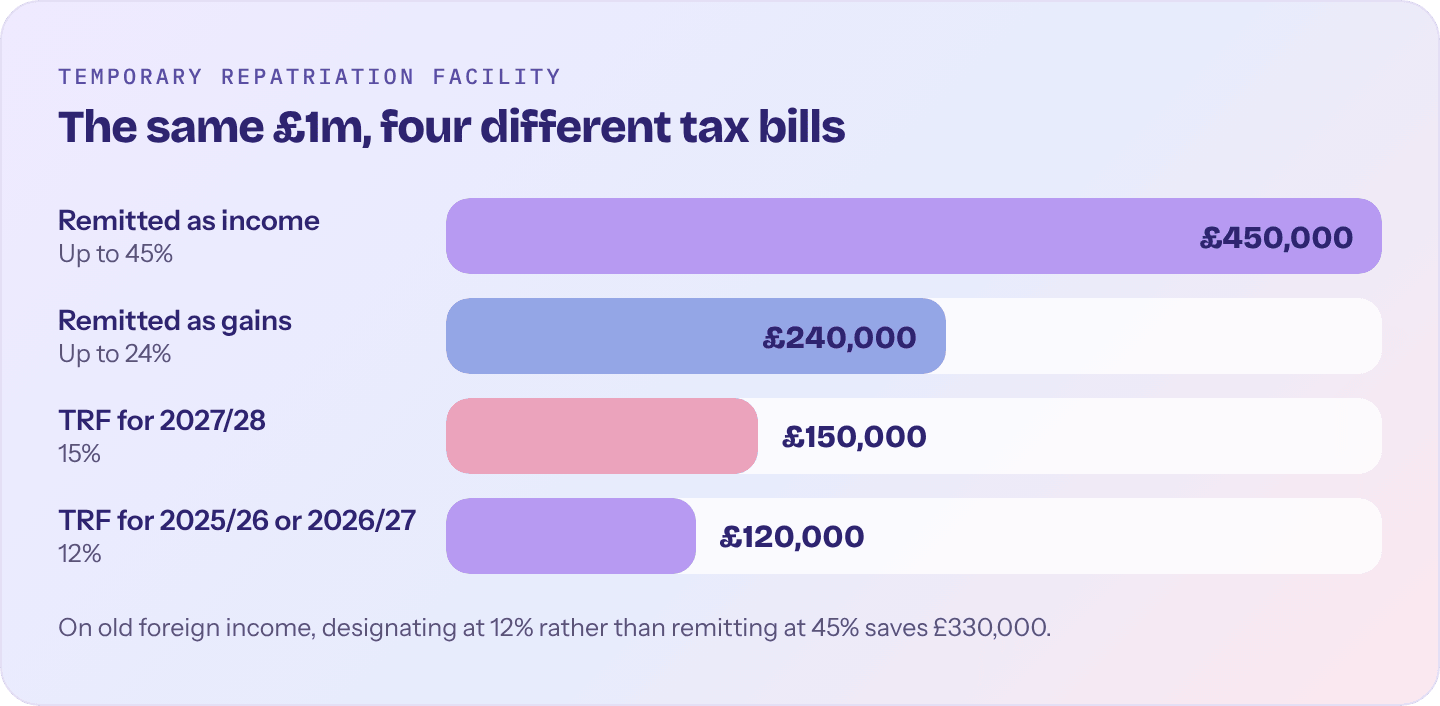
Image 1: the same £1m, four different tax bills
How £1,000,000 of pre-2025 foreign money is brought in | Rate | UK tax |
|---|---|---|
Remitted as income | Up to 45% | £450,000 |
Remitted as gains | Up to 24% | £240,000 |
TRF, designated for 2027/28 | 15% | £150,000 |
TRF, designated for 2025/26 or 2026/27 | 12% | £120,000 |
On £1,000,000 of old foreign income, an ordinary remittance at 45% costs £450,000. Designated at 12% it costs £120,000, a saving of £330,000. The saving on gains is smaller, because the alternative is capital gains tax at up to 24%.
Who can use the TRF?
You can designate amounts for a tax year if:
➜ You are UK resident that year: under the 📖 Statutory Residence Test. You cannot designate for a year you are non-resident.
➜ You were taxed on the remittance basis before: for at least one tax year. That includes years it applied automatically because your unremitted income and gains were under £2,000.
➜ You have qualifying overseas capital: amounts that meet HMRC's definition, set out below.
Being non-domiciled is not enough on its own. The remittance basis must actually have applied to your income or gains for at least one year.
👉 HMRC manual: TRF eligibility (RDRM73200)
👉 The law: Finance Act 2025, Schedule 10, paragraph 1 (eligibility, designation and rates)
What can you designate?
What counts as qualifying overseas capital? Broadly:
➜ Your own pre-2025 foreign income and gains: amounts that arose in 2024/25 or earlier while you were on the remittance basis, whether still offshore or remitted during the TRF window.
➜ Amounts of uncertain origin: offshore funds you held on 6 April 2025 where you cannot trace the source, which can simplify old mixed funds.
➜ Offshore trust distributions: capital payments and benefits received from 2025/26 to 2027/28 that are matched to trust gains or income from before 6 April 2025.
➜ Assets, not just cash: an overseas investment or property bought with pre-2025 foreign income or gains can be designated without selling it.
👉 HMRC manual: qualifying overseas capital (RDRM72100)
👉 The law: Finance Act 2025, Schedule 10, paragraph 2 (qualifying overseas capital)
Designation is not remittance
Do you have to bring the money to the UK? No. Designating and remitting are separate steps:
Designate the amount in your Self Assessment return for the tax year.
Pay the TRF charge through Self Assessment, normally due by 31 January after the end of that tax year.
Remit the money whenever you choose, later or never, with no further UK tax.
A designation is treated as made at the start of the tax year the return covers. So an amount designated in your 2026/27 return counts as designated from 6 April 2026, even if you remitted it during that year.
One practical trap: paying the TRF charge from undesignated offshore funds is itself a taxable remittance. Pay it from clean capital, UK money, or funds you have already designated.
👉 HMRC manual: the TRF charge and how to pay it (RDRM73400)
👉 The law: Finance Act 2025, Schedule 10, paragraph 9 (paying the TRF charge)
The real deadlines
The designation election must be made in your tax return by the first anniversary of the normal 31 January filing date. That gives you an extra 12 months beyond the usual deadline:
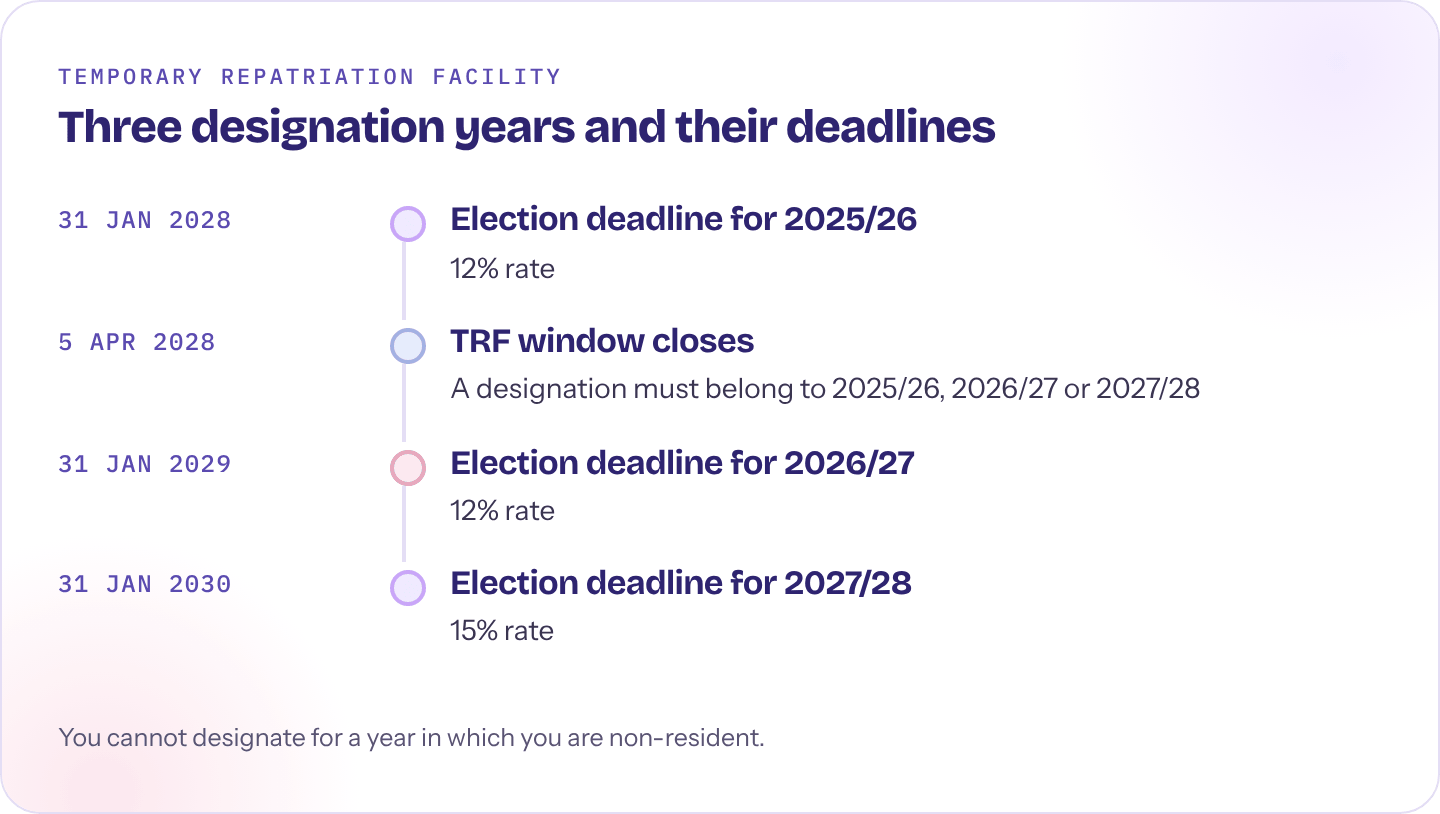
Image 2: the three designation years and their deadlines
➜ 2025/26 designations: 12% rate, election by 31 January 2028.
➜ 2026/27 designations: 12% rate, election by 31 January 2029.
➜ 2027/28 designations: 15% rate, election by 31 January 2030.
Do not confuse the election deadline with the window itself. The TRF only covers the three tax years ending on 5 April 2028, so a designation must belong to one of them. And you cannot designate for a year in which you are non-resident.
Designations can be amended up to the same deadline. After that, they cannot be withdrawn, and there is no repayment if you later spend the money abroad instead.
👉 HMRC manual: TRF time limits (RDRM73320)
👉 The law: Finance Act 2025, Schedule 10, paragraph 8 (designation and time limits)
The foreign tax trap
Is the TRF always cheaper? No. You cannot claim foreign tax credit relief against the TRF charge. Instead, you designate the amount net of foreign tax already paid. Where the overseas tax was high, an ordinary remittance with a full credit can cost less.
Worked example: A heavily taxed foreign gain
Leila made a £100,000 gain on an overseas property in 2022/23 while on the remittance basis. She paid £20,000 of local tax and kept the £80,000 net gain offshore.
Ordinary remittance in 2026/27: as a higher-rate taxpayer, capital gains tax at 24% on £100,000 is £24,000. Credit for the £20,000 foreign tax leaves £4,000 to pay.
TRF designation in 2026/27: 12% on the £80,000 net amount is £9,600, with no credit available.
Leila is £5,600 better off not designating that gain. The TRF saves the most on untaxed or lightly taxed income, such as offshore interest and dividends.
👉 HMRC manual: TRF and foreign tax credits (RDRM73340)
Returning to the UK or leaving it
Two situations come up often:
➜ Former residents coming back: if you return during the TRF years, you can designate as soon as you are UK resident. Remittances made while you were away may be treated as made in your year of return under the 📖 temporary non-residence rules, and can then be designated.
➜ New arrivals: if you have never used the remittance basis, the TRF is not for you. Look at the 📖 four-year FIG regime instead.
Should you use the TRF?
A designation usually makes sense when:
➜ You are staying in the UK: you expect to spend, invest or buy property here in the long term.
➜ The foreign tax was low: the amounts were untaxed or lightly taxed abroad.
➜ The sums are material: the saving justifies paying tax now on money you may not bring in for years.
➜ You can fund the charge cleanly: from clean capital, UK funds or designated money.
➜ The records are messy: designating mixed or uncertain funds can end years of tracing work.
It may not be worth it if you will only be in the UK briefly and never plan to bring the money here. Model each pot separately, because you can designate some amounts and leave others. If the TRF is one part of a wider move or return to the UK, see how we help people moving to the UK, or try our moving to the UK tax calculator.
If you have old remittances or offshore income that was never reported properly, deal with that first. See our guide to the 📖 Worldwide Disclosure Facility.
Frequently asked questions
What is the Temporary Repatriation Facility?
It is a time-limited UK scheme for people who used to claim the remittance basis. It lets them designate foreign income and gains from before 6 April 2025 and pay a flat rate of tax on them: 12% in 2025/26 and 2026/27, and 15% in 2027/28. It closes on 5 April 2028. You make the designation on your Self Assessment tax return, and the money does not have to be brought to the UK to be designated.
What is the TRF rate for 2026/27?
12%. Amounts designated for 2025/26 and 2026/27 are charged at 12%, and amounts designated for 2027/28 at 15%. The facility ends after 5 April 2028.
What is the deadline to designate under the TRF?
The election must be in your return by the anniversary of the normal filing date: 31 January 2028 for 2025/26, 31 January 2029 for 2026/27 and 31 January 2030 for 2027/28.
Do I have to bring the money to the UK to use the TRF?
No. You designate the amount in your tax return and pay the charge. The money can stay offshore and come to the UK later, or never, with no further UK tax.
Can I claim foreign tax credit relief against the TRF charge?
No. The charge applies to the amount after deducting foreign tax, and no further credit is given. Where foreign tax was high, an ordinary remittance with full credit can cost less.
Can I use the TRF if I am not UK resident?
No. You must be UK resident under the Statutory Residence Test for the tax year of designation, and you must have been taxed on the remittance basis for at least one earlier year.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Finance Act 2025, Schedule 10 and Finance Act 2025, section 41, and the HMRC guidance cited above.
How Global Tax Consulting can help
Plan your arrival before you land
Our entry plan confirms whether you can claim the FIG regime, plans your arrival date and capital, and handles your first UK return and claims. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ FIG eligibility confirmed before you arrive
➜ Arrival date planned, including split-year treatment
➜ Capital and overseas income planned before you become UK resident
➜ Your first UK return and claims handled for you
Typical fee
£1,250 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico