
Moving to Australia can be an exciting opportunity, whether you are relocating for work, joining family, or seeking a long-term change of lifestyle. Your move can also create important UK tax considerations.
You may need to establish when you cease to be UK resident, identify the UK income that remains taxable after your departure, and consider how the UK-Australia double tax treaty applies. This guide explains the key points for 2026, including the Statutory Residence Test, capital gains tax, the temporary non-resident rules, and your ongoing filing obligations.
How you are taxed in the UK
The UK operates a residence-based tax system, so your UK residence status determines the extent to which HMRC can tax your income and gains.
If you are UK resident, you are generally liable to UK tax on your worldwide income and gains. That can include:
● Employment or self-employment income earned overseas.
● Foreign rental income.
● Overseas dividends and interest.
● Gains on foreign shares, investments and property.
If you become non-resident, you are generally liable to UK tax only on:
● UK-source income.
● Gains arising from certain UK assets, particularly UK land and property.
● Other income or gains where specific anti-avoidance provisions apply.
UK income that HMRC can continue to tax after you leave
What happens to your UK income when you move to Australia? Becoming non-resident does not remove every UK tax obligation.
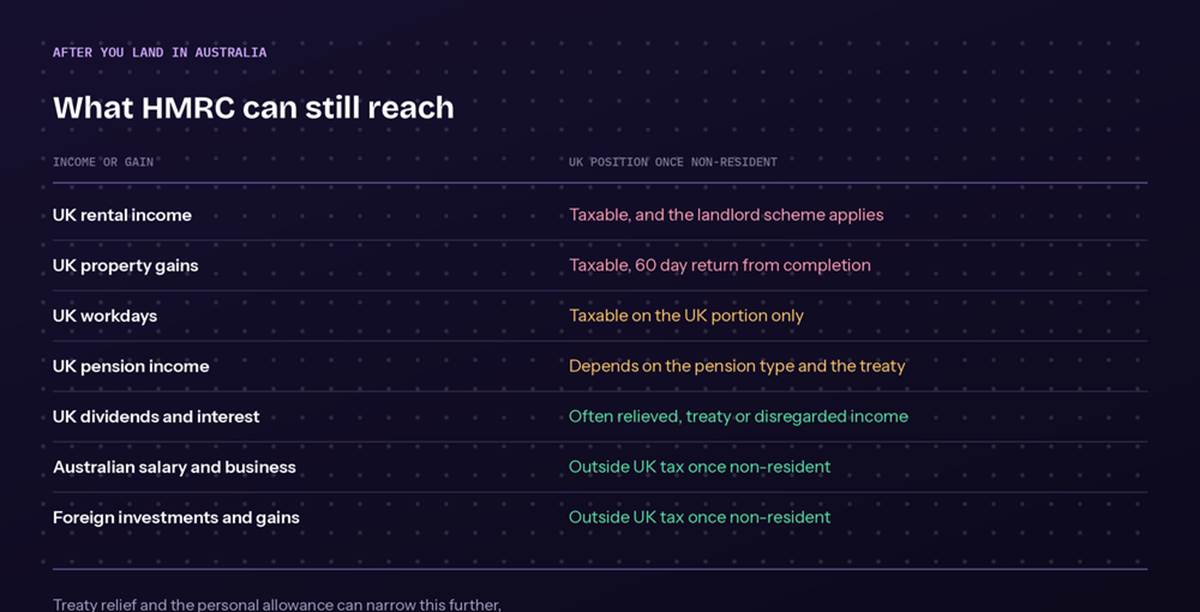
Image 1 — what stays within UK scope
As a starting point, HMRC can continue to tax UK-source income as follows.
● Employment income. Income relating to workdays physically exercised in the UK may remain taxable in the UK.
● Self-employment income. Profits from a business carried on in the UK can remain within the UK tax net.
● Pension income. Pension income from schemes established in the UK may be taxable, subject to the terms of the UK-Australia double tax treaty.
● Investment income. Interest, rental income, dividends and other returns from UK-situated assets may require UK tax consideration.
If you retain a UK property and receive rental income after moving to Australia, you will generally need to report that income to HMRC. You may also need to register under the Non-Resident Landlord Scheme, which otherwise requires your letting agent or tenant to withhold basic rate tax from the rent.
Note that British nationals are entitled to the UK personal allowance regardless of residence status, subject to the relevant conditions. If your total taxable UK-source income does not exceed your personal allowance, no UK income tax may be payable.
Selling your family home: capital gains tax considerations
If you sell your former UK family home after moving to Australia, you may need to consider UK capital gains tax.
Non-residents are generally within the UK capital gains tax regime for gains on UK land and property. The amount due depends on several factors, including:
● The purchase price and the sale proceeds.
● Acquisition and disposal costs.
● The period you occupied the property as your main residence.
● The period it was rented or left empty.
● Whether you qualify for private residence relief.
● Your wider taxable income and the applicable capital gains tax rate.
For 2026/27 the annual exempt amount is £3,000, and residential property gains are taxed at 18% within your remaining basic rate band and 24% above it.
If the property was your main home for all or most of your ownership period, private residence relief may reduce the taxable gain. Relief is not automatic. You must consider periods of absence, letting activity, the final period exemption, and the detailed conditions applying to your circumstances.
The 60 day reporting deadline
If you dispose of UK residential property as a non-resident, you must report the disposal to HMRC and pay any tax due within 60 days, even where no capital gains tax is ultimately payable.
⚠️ WARNING The 60 days runs from completion, not from exchange of contracts. Those dates can be weeks or months apart, and the return is required even where the disposal produces no gain or a loss. Managing this from the other side of the world, with a twelve hour time difference, is considerably easier if the valuation work is done before you exchange.
You should also consider Australian tax. If you are Australian resident when the property is sold, Australia may tax the gain under its worldwide income rules. The treaty and domestic foreign tax credit rules may then provide relief against double taxation.
How to become non-resident under the Statutory Residence Test
Your UK residence status is determined for each UK tax year, which runs from 6 April to 5 April of the following year.
To become non-resident you must satisfy one of the automatic overseas tests, or avoid the automatic UK tests and fall outside the sufficient ties rules.
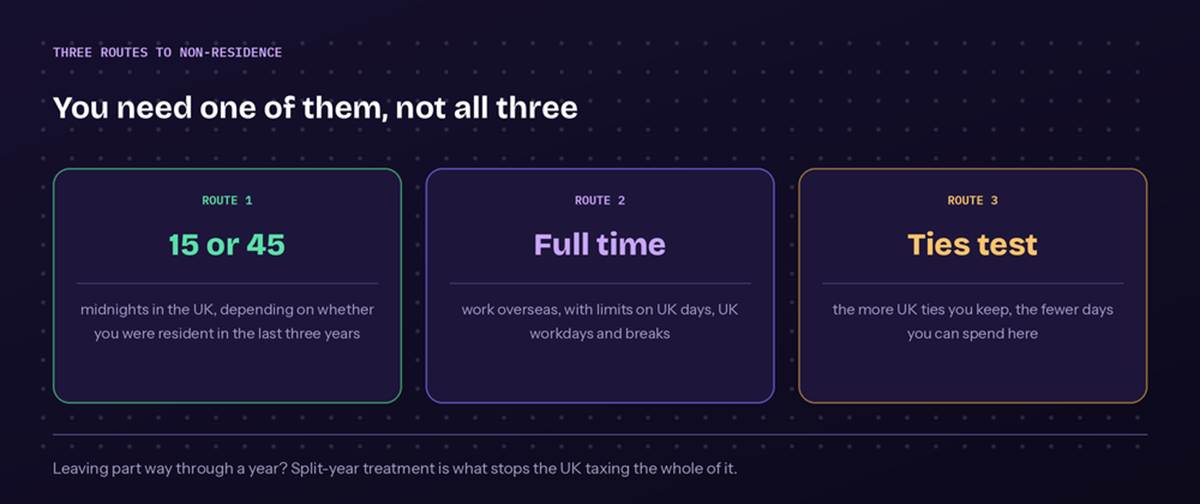
Image 2 — the three routes out
1. Limit your UK physical presence
If you were UK resident in one or more of the previous three tax years, you may be automatically non-resident if you spend no more than 15 midnights in the UK during the tax year.
If you were not UK resident in any of the previous three tax years, the relevant limit may be no more than 45 midnights.
These limits are not the only consideration. If you exceed them, your status may depend on your UK ties, including family, accommodation, work and historic presence.
2. Work full-time overseas
You may qualify as non-resident if you work full-time overseas, subject to detailed conditions. These include restrictions on:
● The number of days you spend in the UK.
● The number of days you work in the UK.
● Your average working hours, broadly 35 a week.
● Gaps in your overseas work.
You must maintain appropriate records of travel and working days. A person who works remotely from the UK for an Australian employer may still create UK residence or UK employment tax issues, depending on the facts.
3. Cut UK ties and minimise your presence
If you do not meet an automatic overseas test, the sufficient ties test may apply. The more UK ties you retain, the fewer days you may be able to spend in the UK without becoming resident.
Relevant ties can include:
● A UK-resident spouse, civil partner or minor child.
● Available accommodation in the UK.
● Substantive work performed in the UK.
● Spending more than 90 days in the UK in either of the previous two tax years.
● Spending more days in the UK than in any other country.
Split-year treatment
If you leave part way through a tax year, split-year treatment may apply. Where the conditions are met, the year is divided into a UK-resident part and a non-resident part. This can prevent Australian employment or business income arising after your departure from being treated as part of your UK worldwide income.
The precise split-year case and effective date depend on your circumstances. We recommend obtaining advice before departure if your move involves employment, business interests, property or significant investment assets.
The UK-Australia double tax treaty
The UK and Australia have a comprehensive double taxation convention. The treaty can restrict or remove HMRC’s right to tax certain income, or require one country to give credit for tax paid in the other.
It may help you in several ways:
● It can allocate primary taxing rights over employment, pension, interest, dividend and rental income.
● It can provide tie-breaker rules if you are resident in both countries under domestic law.
● It can reduce the UK tax rate applying to certain income.
● It can require Australia to credit UK tax paid on income that is also taxable in Australia.
For example, if you retain a UK property after moving to Australia, the rental income may be taxable in both countries. Australia may be required to give credit for UK tax paid on that income, subject to its domestic rules and the relevant treaty provisions.
Certain income may also be exempt from UK tax under the treaty. Depending on your Australian status, including whether you qualify as a temporary resident under Australian law, the same income may receive different treatment in Australia.
The treaty does not apply automatically in every case. You may need to make a claim and provide evidence of Australian tax residence, and to submit form DT-Individual where you are seeking relief from UK tax on income allocated to Australia.
⚖️ UK-Australia double tax treaty
Pensions
The treatment of pensions requires particular care. UK pension income may be taxable in Australia once you become Australian resident, while the UK’s taxing rights depend on the type of pension and the relevant treaty article. Review private pensions, state pension income and government service pensions separately, as they can each land differently.
Returning to the UK: temporary non-resident rules
Are you moving to Australia permanently, or could you return to the UK within a few years? If your absence is temporary, anti-avoidance rules may affect the timing of your tax charges.
The temporary non-resident rules are designed to prevent people leaving the UK temporarily to receive income or dispose of assets without paying the tax that would have applied had they remained UK resident.
Broadly, the rules can apply where you:
● Were UK resident and owned assets or generated income.
● Left the UK and became non-resident.
● Received the income or disposed of the assets while non-resident.
● Returned to the UK within a specified period and resumed UK residence.
Where the rules apply, the relevant income or gains may be brought into charge in the tax year in which you return. Potentially affected items include:
● Dividend income from profits generated before your departure.
● Pension income excluded from UK tax under a double tax treaty.
● Gains on shares acquired before you left the UK.
● Gains relating to property disposals, or gains arising before 6 April 2015, depending on the circumstances.
That specified period is generally five years, so an absence of more than five years takes you outside the rules. The conditions are detailed and cover the length of your non-resident period, the nature of the income or gain, and the date an asset was acquired.
⚠️ WARNING Given the distance and cost involved, a move to Australia is rarely a short one. But people do return sooner than planned, for family reasons or because a posting ends early. If there is any prospect of that, consider the rules before taking large dividends, drawing down pensions, or disposing of investments.
Your UK compliance obligations
The UK tax year runs from 6 April to 5 April. The normal deadline for filing an online tax return and paying the resulting liability is 31 January following the end of the tax year.
You may still need to file a UK tax return after becoming non-resident if you receive UK rental income, perform UK workdays, dispose of UK property, or need to claim split-year treatment or treaty relief.
Note that HMRC’s own free filing service cannot submit the residence pages that every non-resident needs, so you will require commercial software or an adviser.
➡️ Check if you need to file a UK tax return
Before you go: a short checklist
● Confirm your residence position. Work through the Statutory Residence Test for the year of departure and the year after, since split-year treatment under the full-time work route depends on both.
● Deal with UK property. Register under the Non-Resident Landlord Scheme if you are letting it, and get a valuation if you may sell.
● Review your pensions. Establish which treaty article applies to each scheme before you draw anything.
● Keep records from day one. Travel dates, UK workdays and UK nights. Reconstructing them two years later is difficult and unconvincing.
● Consider the return. If you may come back within five years, model that before making large disposals.
work with GTC
Get your position confirmed in writing
Global Tax Consulting advises internationally mobile individuals on residency reviews, UK tax planning and tax return preparation. Tell us where you are and what you earn, and you will have a fixed fee and a clear view of your UK tax position.
⭐ 5★ rated