
Key points
The remittance basis has gone, but the money it sheltered is still taxed when it comes to the UK.
✓ It cannot be used for 2025/26 or any later tax year. Residence under the Statutory Residence Test is what counts now, not domicile.
✓ A claim cost your personal allowance and CGT annual exempt amount, plus a £30,000 or £60,000 annual charge for long-term residents.
✓ A remittance is wider than a bank transfer. Paying for a UK service or a UK-related debt from offshore funds can count.
✓ The Temporary Repatriation Facility charges 12% for 2025/26 or 2026/27 and 15% for 2027/28, with no foreign tax credit.
✓ Some former users can rebase foreign assets to their 5 April 2017 value when they sell.
✓ New arrivals after 10 tax years of non-residence can claim the FIG regime for four tax years.
The remittance basis was a way of being taxed that let UK residents who were not domiciled here pay UK tax on their foreign income and gains only when they brought the money to the UK. It was abolished from 6 April 2025, and 2024/25 was the last tax year it could be used.
It still matters in 2026/27. Foreign income and gains that built up under the remittance basis before 6 April 2025 are still taxed if you bring them to the UK now. New arrivals get a different relief, the 4-year FIG regime, which depends on residence and not domicile.
This guide covers how the remittance basis of taxation worked, what it cost, what still counts as a remittance, what replaced the remittance basis, and what former users and new arrivals should do now.
If you would like this checked for your own situation, see our help for people moving to the UK.
What was the remittance basis of taxation?
You had to be UK resident and not domiciled in the UK. Domicile is broadly the country the law treats as your permanent home. Up to 2012/13, people who were resident but not ordinarily resident in the UK could use it too.
Most UK residents are taxed on the arising basis: worldwide income and gains are taxed in the year they arise, wherever the money is kept. The remittance basis put off UK tax on foreign income and gains until they were remitted, meaning brought to or used in the UK. UK income and gains were taxed in full.
It was a choice made year by year, by a claim on your Self Assessment return.
👉 HMRC manual: what is the remittance basis? (RDRM31030)
👉 The law: Income Tax Act 2007, section 809B (claim for remittance basis)
What did the non dom remittance basis cost?
Was a claim free? No. From 6 April 2008, a claim came at a price:
➜ Your personal allowance: you lost it for the year of the claim.
➜ Your capital gains tax annual exempt amount: you lost that too.
➜ The remittance basis charge: an annual charge for long-term resident adults, on top of the tax on anything remitted.
The remittance basis charge, 2017/18 to 2024/25
Your UK residence | Annual charge for claiming |
|---|---|
Fewer than 7 of the previous 9 tax years | None |
At least 7 of the previous 9 tax years | £30,000 |
At least 12 of the previous 14 tax years | £60,000 |
At least 15 of the previous 20 tax years | No claim: deemed UK domiciled |
The last row is the deemed domicile rule, which applied from 6 April 2017. After 15 of the previous 20 tax years of UK residence, you were treated as UK domiciled and could no longer claim.
There was one automatic rule. If your unremitted foreign income and gains for the year were under £2,000, the remittance basis applied without a claim. You kept your allowances and paid no charge.
👉 HMRC manual: the remittance basis charge (RDRM32210)
👉 The law: Income Tax Act 2007, section 809H (remittance basis charge)
When was the remittance basis abolished?
When did it end? It was abolished from 6 April 2025. The Finance Act 2025 says the remittance basis is not available for 2025/26 or any later tax year, so the final claims were for 2024/25.
Domicile stopped mattering for income tax and capital gains tax at the same time. What counts now is residence under the 📖 Statutory Residence Test. Every UK resident is taxed on the arising basis unless they qualify for the new 4-year relief and claim it. See our guide to 📖 UK tax on foreign income.
👉 The law: Finance Act 2025, section 40 (remittance basis not available after 2024/25)
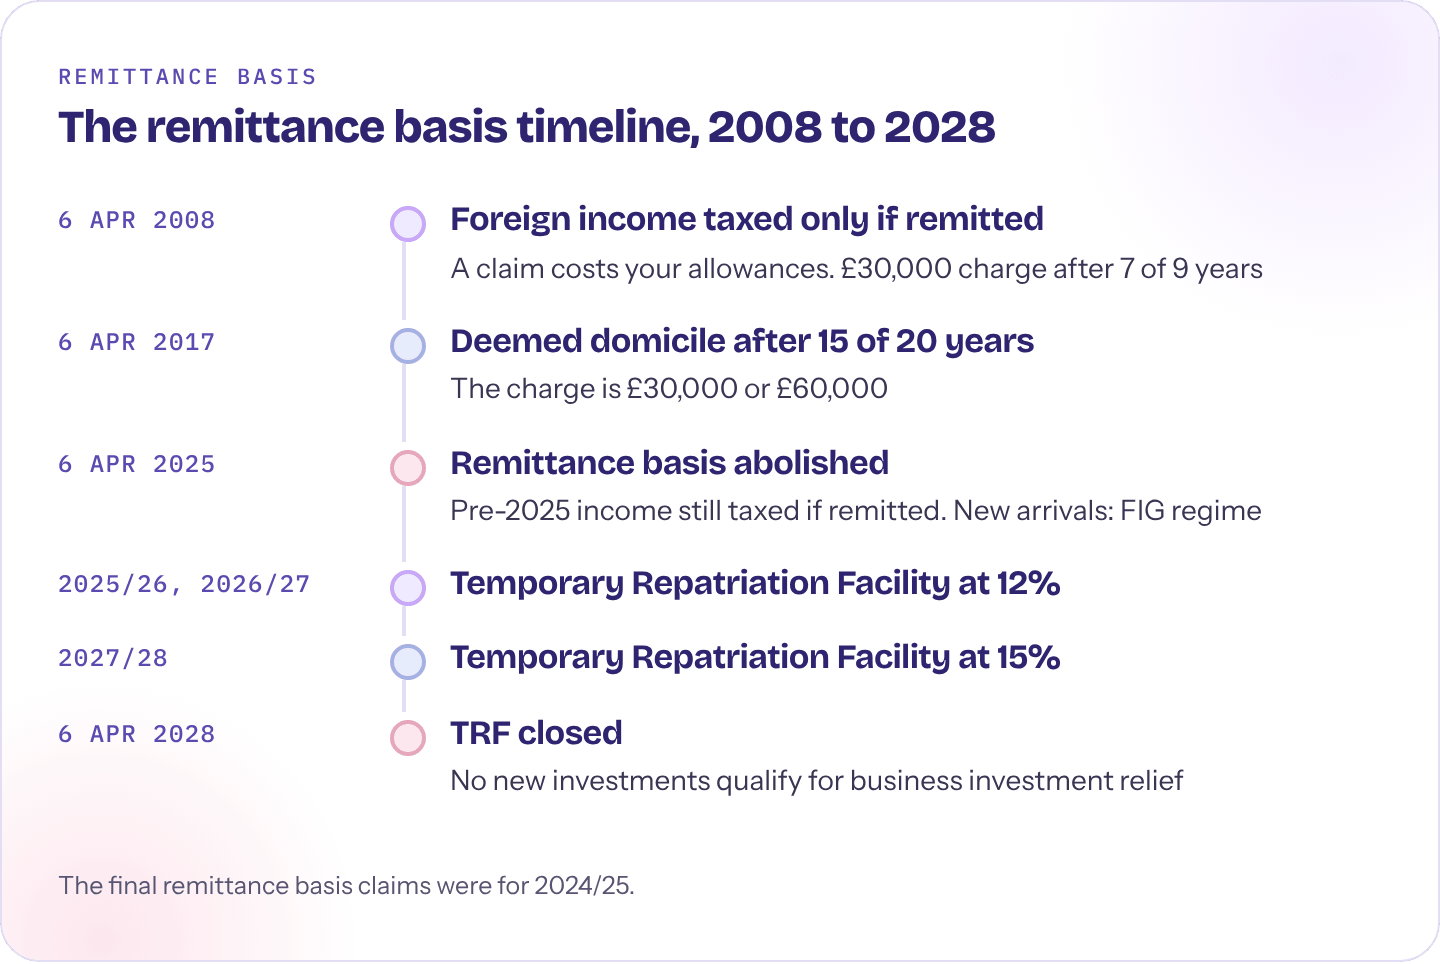
Image 1: The remittance basis timeline, 2008 to 2028
Date or period | What applies |
|---|---|
6 April 2008 | A remittance basis claim costs your allowances. £30,000 charge after 7 of 9 years resident. |
6 April 2017 | Deemed domicile after 15 of 20 years. The charge is £30,000 or £60,000. |
2008/09 to 2024/25 | Remittance basis: foreign income and gains taxed only if remitted. |
6 April 2025 | Remittance basis abolished. Pre-2025 income is still taxed if remitted. New arrivals after 10 tax years away can claim the 4-year FIG regime instead. |
2025/26 and 2026/27 | Temporary Repatriation Facility (TRF) rate of 12%. |
2027/28 | TRF rate of 15%. |
6 April 2028 (2028/29 on) | TRF closed. No new investments qualify for business investment relief. |
Why the remittance basis still matters in 2026/27
Is old foreign income now safe to bring in? No. If the remittance basis applied to you in an earlier year, the foreign income and gains it sheltered are still taxed at the usual rates when you remit them, however long ago they arose.
You report the remittance on your tax return for the year you make it. Remitted foreign dividends are taxed at the normal income tax rates, not the dividend rates, with no dividend allowance.
What counts as a remittance?
It is wider than a bank transfer. Pre-April 2025 foreign income or gains, or anything bought with them, are remitted when:
➜ Money or assets come to the UK: they are brought to, received in or used in the UK by you or for your benefit.
➜ You pay for a UK service: the service is provided in the UK and paid for from the offshore funds.
➜ You pay a UK-related debt abroad: for example, repaying an overseas loan that funded a UK purchase, including the interest.
➜ A relevant person does any of this: your spouse, civil partner or cohabiting partner, your children and grandchildren under 18, and trusts and closely held companies connected to any of you.
👉 HMRC helpsheet: HS264 Remittance of pre-6 April 2025 foreign income and gains
👉 The law: Income Tax Act 2007, section 809L (meaning of remitted to the UK)
Mixed funds
A mixed fund is an overseas account or asset holding more than one kind of money, or money from more than one tax year. One account holding salary, interest and sale proceeds is typical.
You cannot pick which part you are remitting. Fixed ordering rules apply, starting with the most recent tax year. Within each year, untaxed employment income comes out first, then other untaxed foreign income, then untaxed foreign gains, then income and gains that suffered foreign tax, and capital last.
👉 HMRC manual: mixed fund ordering rules (RDRM35240)
👉 The law: Income Tax Act 2007, section 809Q (transfers from mixed funds)
What is not a remittance?
A few exemptions remain. Exempt property includes clothing, footwear, jewellery and watches for personal use, items brought in temporarily or for repair, and items where the amount remitted would be under £1,000.
Business investment relief lets you bring pre-April 2025 income and gains to the UK without a tax charge if you invest them in a qualifying company within 45 days. No new investments qualify from 6 April 2028.
👉 HMRC manual: business investment relief (RDRM34310)
👉 The law: Income Tax Act 2007, section 809VA (business investment relief)
What replaced the remittance basis?
The foreign income and gains (FIG) regime. If you become UK resident after at least 10 consecutive tax years of non-residence, you can claim relief from UK tax on foreign income and gains arising in your first four tax years here. Domicile and nationality do not matter.
A claim still costs your personal allowance and capital gains tax annual exempt amount, but there is no annual charge, and relieved money can be brought to the UK freely. See our guide to the 📖 4-year FIG regime.
Overseas Workday Relief, for pay for work done abroad, now runs for the same four years. It is capped at the lower of 30% of your qualifying employment income and £300,000 a year, and the pay no longer has to stay offshore.
Old rules and new rules compared
Area | Up to 5 April 2025 | From 6 April 2025 |
|---|---|---|
Who qualifies | UK residents not domiciled here | New residents after 10 tax years away |
Foreign income and gains | Taxed only if remitted | Relieved if claimed |
How long | Until deemed domiciled | Four tax years |
Cost of a claim | Allowances, plus up to £60,000 a year | Allowances only |
Inheritance tax on overseas assets | Based on domicile | Based on long-term residence |
The FIG regime does not cover the past. Former remittance basis users cannot claim it on income and gains from before 6 April 2025.
👉 HMRC manual: FIG regime introduction (RFIG41000)
👉 The law: Income Tax (Trading and Other Income) Act 2005, Part 8, Chapter 5 (the FIG regime)
The Temporary Repatriation Facility
Is there a cheaper way to bring old money in? Yes, for now. Under the Temporary Repatriation Facility (TRF), you designate pre-6 April 2025 foreign income and gains on your tax return and pay a flat charge. The money can then come to the UK with no more tax.
➜ The rates: 12% for amounts designated for 2025/26 or 2026/27, and 15% for 2027/28.
➜ Who can use it: you must be UK resident in the year you designate, and the remittance basis must have applied to you for at least one earlier year.
➜ How: on the SA109 residence pages of your return. A 2026/27 designation can be made up to 31 January 2029, a year after the normal filing date.
➜ The catch: no foreign tax credit can be set against the TRF charge.
See our guide to the 📖 Temporary Repatriation Facility before you designate.
👉 HMRC manual: temporary repatriation facility (RDRM71000)
👉 The law: Finance Act 2025, Schedule 10 (Temporary Repatriation Facility)
Worked example: Remit normally or designate?
Priya claimed the remittance basis from 2018/19 to 2024/25. She has £200,000 of foreign interest and dividends from those years in a Singapore account. No foreign tax was paid on it.
In 2026/27 she is UK resident with a UK salary of £150,000, and wants the money here.
Ordinary remittance: her salary is already above £125,140, so it is all taxed at 45%. £200,000 x 45% = £90,000.
TRF designation in her 2026/27 return: £200,000 x 12% = £24,000. That is £66,000 less.
If she waits and designates for 2027/28, the charge is £200,000 x 15% = £30,000.
The example uses 2026/27 rates for England, Wales and Northern Ireland. Had Priya paid foreign tax on the income, the comparison could look very different.
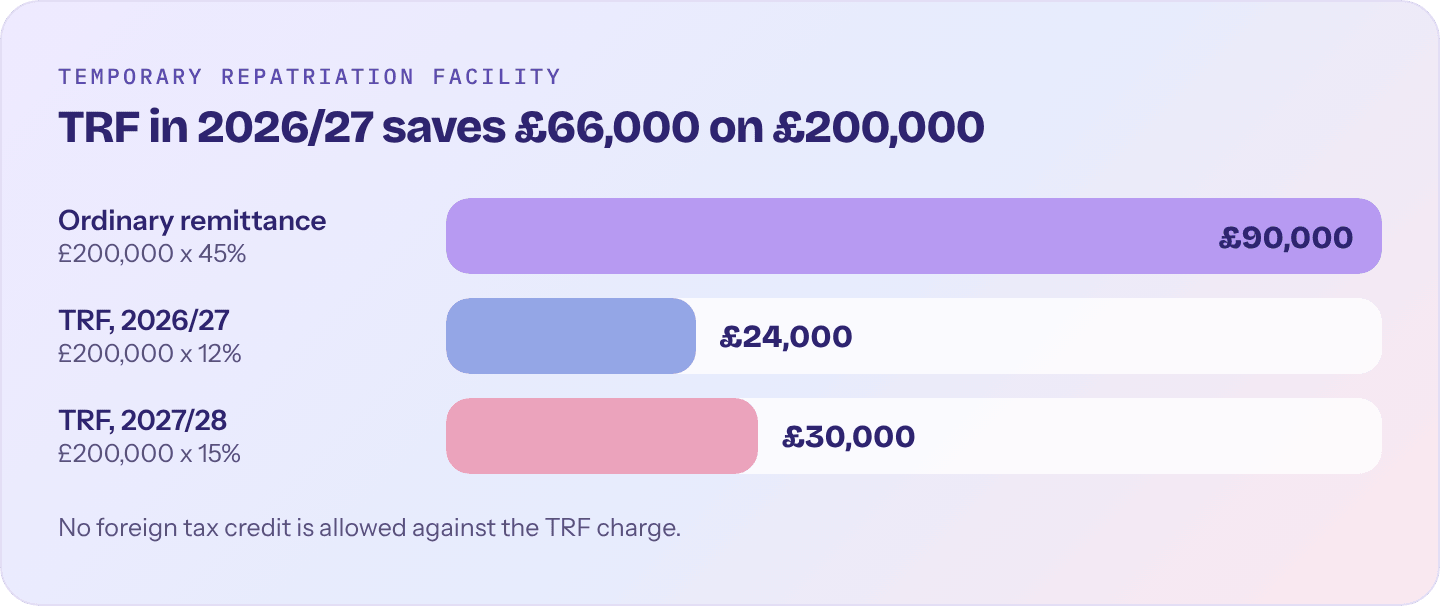
Image 2: Ordinary remittance or TRF designation on £200,000
Option | Calculation | Tax on £200,000 |
|---|---|---|
Ordinary remittance | £200,000 x 45% | £90,000. Taxed at her top income tax rate when she brings it in. |
TRF, 2026/27 | £200,000 x 12% | £24,000. Designated on her tax return. No more tax when it comes to the UK. |
TRF, 2027/28 | £200,000 x 15% | £30,000. The last year of the facility, at the higher rate. |
Saving in 2026/27 | £90,000 less £24,000 | £66,000. No foreign tax credit is allowed against the TRF charge. |
Other changes that came with abolition
Capital gains tax rebasing to 5 April 2017
Can former users reduce gains on overseas assets? Some can. If you sell a foreign asset on or after 6 April 2025, its cost for capital gains tax is reset to its market value on 5 April 2017, if all of these apply:
➜ You held it on 5 April 2017 and it was not in the UK at any time from 6 March 2024 to 5 April 2025, with limited exceptions.
➜ You claimed the remittance basis for at least one tax year from 2017/18 to 2024/25. Years when it applied automatically do not count.
➜ You were never UK domiciled or deemed domiciled in any tax year before 2025/26.
For help with the figures, see our capital gains tax advice.
👉 The law: Finance Act 2025, Schedule 11 (rebasing of assets)
Inheritance tax
Inheritance tax moved from domicile to residence too. From 6 April 2025, your overseas assets are in scope once you are a long-term UK resident, meaning UK resident for at least 10 of the previous 20 tax years. After you leave, you stay in scope for between 3 and 10 tax years.
👉 GOV.UK: Inheritance Tax if you are a long-term UK resident
👉 The law: Inheritance Tax Act 1984, section 6A (long-term UK residents)
Offshore trusts
Before April 2025, non-domiciled people who had set up an offshore trust were generally protected from UK tax on foreign income and gains kept inside it. That protection has ended. If you are UK resident and can benefit from the trust, its foreign income and gains are now, in most cases, taxed on you as they arise, unless you qualify for the FIG regime and claim it.
Income that was protected before 6 April 2025 can still be taxed later, when the trust provides a benefit to you or close family.
👉 HMRC manual: settlors of non-resident trusts from 6 April 2025 (TSEM4705)
What to do now
If you used the remittance basis in the past:
➜ List your offshore accounts and assets. Work out what is pre-April 2025 income, what is gains and what is capital.
➜ Check before you transfer. Anything you, your partner or your minor children bring in can be a remittance.
➜ Model the TRF for each pot. The 12% rate ends with 2026/27. Compare it with an ordinary remittance and a foreign tax credit.
➜ Find your 5 April 2017 values. You will need them if rebasing applies.
If you are arriving now:
➜ Count your years away. Ten consecutive tax years of non-residence is the test for the FIG regime.
➜ Plan your first four tax years. A split year counts as a full one.
➜ File a return. Relief has to be claimed each year. See 📖 do I need to file a UK tax return?
Common mistakes with the remittance basis
➜ Thinking abolition wiped the slate clean. Pre-April 2025 income and gains are still taxed when remitted, however old they are.
➜ Looking only at bank transfers. Paying a UK bill from abroad or repaying a UK-related loan can be a remittance too.
➜ Treating a mixed account as capital first. The ordering rules usually take income out before capital.
➜ Remitting and not reporting it. If that has already happened, see our guide to the 📖 Worldwide Disclosure Facility.
Frequently asked questions
What is the remittance basis?
It was a UK tax treatment for residents who were not domiciled in the UK. Their foreign income and gains were taxed only if brought to or used in the UK. It was abolished from 6 April 2025.
Has the remittance basis been abolished?
Yes. It cannot be used for 2025/26 or any later tax year, so 2024/25 was the last year. UK residents are now taxed on worldwide income and gains as they arise, unless they claim the 4-year FIG regime.
What replaced the remittance basis?
The foreign income and gains (FIG) regime. People who become UK resident after 10 consecutive tax years abroad can claim relief on foreign income and gains for their first four tax years. It is based on residence, not domicile.
Do I still pay tax if I remit income from before April 2025?
Yes, if the remittance basis applied when it arose. It is taxed at the usual rates in the year you remit it. The Temporary Repatriation Facility lets you pay 12% for 2025/26 or 2026/27, or 15% for 2027/28.
What was the remittance basis charge?
An annual charge for long-term UK residents who claimed the remittance basis. It was £30,000 after 7 of the previous 9 tax years of UK residence and £60,000 after 12 of the previous 14. It was abolished with the remittance basis from 6 April 2025.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Income Tax Act 2007, Part 14, Chapter A1 and Finance Act 2025, section 40, and the HMRC guidance cited above.
How Global Tax Consulting can help
Plan your arrival before you land
Our entry plan confirms whether you can claim the FIG regime, plans your arrival date and capital, and handles your first UK return and claims. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ FIG eligibility confirmed before you arrive
➜ Arrival date planned, including split-year treatment
➜ Capital and overseas income planned before you become UK resident
➜ Your first UK return and claims handled for you
Typical fee
£1,250 to £5,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico