
Key points
You pay nothing on the day you leave. The rule to plan around is the five-year rule.
✓ No exit tax for individuals has been enacted or officially announced as at October 2026.
✓ If you were UK resident in at least four of the seven tax years before leaving, sell assets while abroad and return within five years, the gains are taxed in the year you come back.
✓ UK property and land are taxed however long you are away.
✓ In the year you leave, you count as UK resident for the whole tax year unless split-year treatment applies.
✓ Stay away for more than five years and gains on assets sold while abroad stay outside UK tax.
There is no UK exit tax for individuals. Leaving the UK is not treated as a sale of your assets, so you do not get a capital gains tax bill on your shares, investments or overseas property just because you have moved. That is the law for the 2026/27 tax year.
What the UK has is its own equivalent: the temporary non-residence rules, often called the five-year rule. They have been in UK tax law since 1998. You pay nothing on the day you go, and tax only comes back into the picture if you sell while you are away and then return within five years.
So if you have seen headlines about a UK exit tax and you are leaving for good, the rules that apply to you already exist and are well understood. This guide explains how they work, who they catch and who they do not, and what else the UK can still tax after you leave.
If you would like this checked for your own situation, see how we help people who are leaving the UK.
Is there a UK exit tax in 2026/27?
UK residents pay capital gains tax on assets anywhere in the world. Non-residents pay it only on UK property and land, assets of a UK branch or agency, and certain shares in companies whose value comes mainly from UK land. No rule treats you as selling everything you own on the day you stop being resident.
HMRC's Capital Gains Manual says the same: no legislation creates a charge for individuals ceasing to be resident.
👉 HMRC manual: migration and exit charges (CG13400)
GOV.UK confirms that if you are abroad, you do not pay capital gains tax on shares in UK companies unless you return within five years or the company is UK property rich.
👉 GOV.UK: Capital Gains Tax: what you pay it on
Is the UK bringing in an exit tax?
Not as the law stands in October 2026. No charge on individuals leaving the UK was announced in the Budget on 26 November 2025, and there is none in Finance Act 2026. The UK deals with people who leave to sell assets tax free in a different way, and has done for more than 25 years.
The UK's equivalent of an exit tax: the temporary non-residence rules
Before 1998 it was often possible to avoid capital gains tax by becoming non-resident for a short time, selling, and coming back. Finance Act 1998 closed that route with the temporary non-residence rules.
👉 HMRC manual: temporary non-residence: introduction (CG26100)
👉 The law: Taxation of Chargeable Gains Act 1992, section 10A (temporary non-residents)
An exit tax and the UK rules aim at the same thing, but they work in opposite ways.
Exit tax compared with the UK's five-year rule
Question | A typical exit tax | The UK's five-year rule |
|---|---|---|
When is tax charged? | On the day you leave | Only in the year you come back |
On what? | Gains you have not realised yet | Gains you actually made while away |
If you never sell? | Still charged | Nothing to charge |
If you leave for good? | Still charged | No charge once you have been away more than five years |
Canada is an example of the first column. It deems emigrants to have disposed of certain property at fair market value when they leave. The United States has an expatriation tax that deems a covered expatriate's property sold the day before they give up citizenship or long-term residence.
👉 Canada Revenue Agency: Dispositions of property for emigrants of Canada
👉 Internal Revenue Service: Expatriation tax
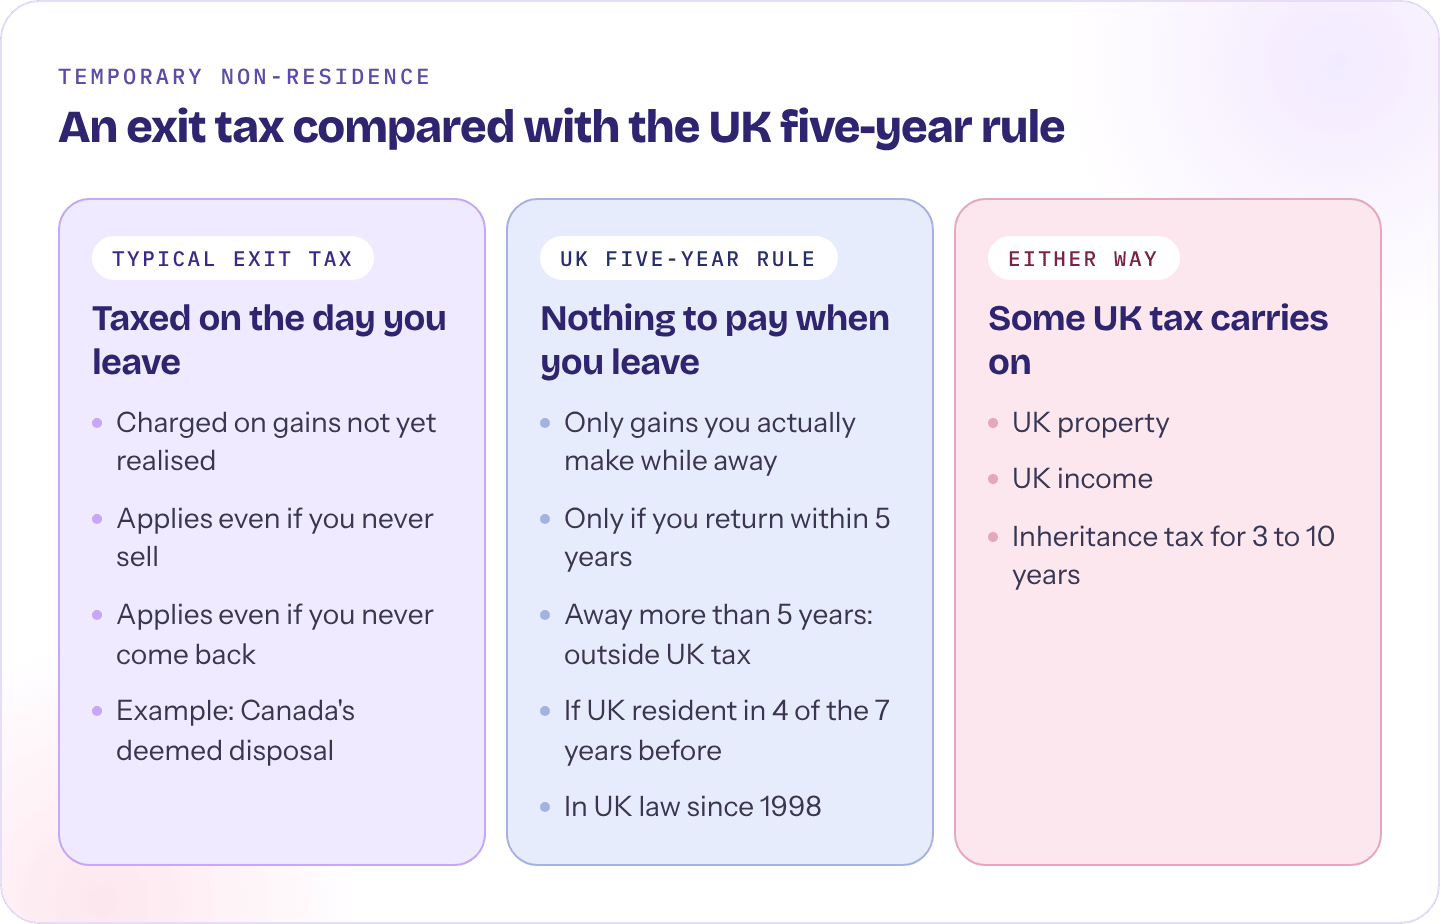
Image 1: An exit tax compared with the UK's five-year rule
Approach | How it works |
|---|---|
A typical exit tax: taxed on the day you leave | Charged on gains you have not realised. Applies even if you never sell. Applies even if you never come back. Example: Canada's deemed disposal for emigrants. |
The UK's temporary non-residence rule: nothing to pay on the day you leave | Only gains you actually make while away. Only if you return within 5 years. Away more than 5 years: outside UK tax. In UK law since 1998. Applies if you were UK resident in at least 4 of the 7 tax years before leaving. |
Either way | UK property, UK income and inheritance tax (for 3 to 10 years) carry on after you leave. |
How the five-year rule works
The rules apply if you were UK resident in at least four of the seven tax years before you left, and you are away for five years or less. Certain gains and income from your time abroad are then taxed in the year you come back.
The main target is gains on assets you already owned when you left. Sell them abroad and there is no UK tax at the time, but return too soon and the gain is treated as arising in your year of return.
👉 HMRC helpsheet: HS278 Temporary non-residents and Capital Gains Tax
👉 The law: Finance Act 2013, Schedule 45, Part 4 (temporary non-residence)
We cover how the five years are counted, and everything that is caught, in our guide to the 📖 temporary non-residence rules.
Who does not need to worry about it
➜ You are leaving for good. Stay non-resident for more than five years and gains you made while away stay outside UK tax.
➜ You do not sell while you are away. The rule only bites on gains you actually make. Holding your investments triggers nothing.
➜ You sell assets you bought after leaving. These are normally outside the rules, even if you come back early.
➜ You were not in the UK long. If you were UK resident in fewer than four of the seven tax years before you left, the rules do not apply.
The people who need to plan are those who might return within five years after selling a business, shares or other large assets.
The April 2026 change for company owners
The same rules catch dividends from a close company, broadly one controlled by a small group of shareholders, where you are a material participator. Until April 2026, dividends paid out of trading profits earned after you left were outside the charge. Finance Act 2026 removed that exception for anyone who becomes UK resident again on or after 6 April 2026. All such dividends received while you are away are now taxed on your return, with credit for foreign tax paid on them.
👉 HMRC manual: distributions from closely controlled companies (RFIG21600)
👉 The law: Income Tax (Trading and Other Income) Act 2005, section 401C (temporary non-residents)
If you run your own company, read 📖 running a UK limited company while living abroad.
Example: the five-year rule on a share sale
Hannah has listed shares she has owned for years, standing at a £150,000 gain, and is a higher rate taxpayer in each tax year below. She leaves the UK on 1 August 2026 for a full-time job overseas, and split-year treatment applies from that date.
➜ She sells in June 2026, before leaving. She is UK resident, so the gain is taxed in 2026/27: £150,000 less the £3,000 annual exempt amount is £147,000, taxed at 24%, which is £35,280.
➜ She sells in November 2026, after leaving. There is no UK capital gains tax in 2026/27, and no charge for having left.
➜ She moves back in September 2030, about four years after leaving. The gain is treated as arising in 2030/31 and taxed at that year's rates. At 2026/27 rates that is the same £35,280.
➜ She stays away until September 2031, more than five years, with split-year treatment in the year she returns. The gain stays outside UK tax.

Image 2: How the date of a share sale changes the UK tax
When Hannah sells and returns | UK tax on the £150,000 gain | Why |
|---|---|---|
Sells June 2026, before leaving | £35,280 | (£150,000 - £3,000) × 24%, due for 2026/27 |
Sells November 2026, back by September 2030 | £35,280 | Nothing in 2026/27. Taxed in 2030/31, the year of return. |
Sells November 2026, back September 2031 | £0 | Away more than five years, so no UK tax on the gain |
Hannah is a higher rate taxpayer who leaves on 1 August 2026 with split-year treatment from that date. She is UK resident from 6 April to 31 July 2026. If she comes back between 1 August 2026 and 1 August 2031, the five-year rule applies. Back from 2 August 2031, she is outside the rule.
The country she moves to may also tax the gain, so check both sides before selling.
What else can the UK tax after you leave?
Is the five-year rule the only thing to check? No. Three other rules carry on whether or not you come back.
What follows you when you leave the UK
Asset or income | UK tax after you leave? | Rule to check |
|---|---|---|
Shares, funds, crypto, overseas property | No, unless you return within five years | Temporary non-residence |
UK property and land | Yes, capital gains tax on sale | Report within 60 days |
Shares in a UK property-rich company | Yes, if you hold 25% or more | 75% of value from UK land |
UK rent, pensions, pay for UK workdays | Yes, unless a tax treaty says otherwise | UK-source income |
Your worldwide estate | Yes, for 3 to 10 years if you are a long-term resident | Inheritance tax tail |
UK property and land
Non-residents pay capital gains tax on UK property and land, residential or commercial. You must report the sale to HMRC within 60 days of completion, even if there is no tax to pay or you have made a loss. For property you already owned, the standard approach taxes only the growth since 5 April 2015 for residential property, and 5 April 2019 for commercial property.
👉 GOV.UK: Tell HMRC about Capital Gains Tax on UK property or land if you are not a UK resident
👉 The law: Taxation of Chargeable Gains Act 1992, section 1A (non-residents and UK land)
For the calculation and reliefs, see our guide to 📖 non-resident capital gains tax.
UK income
You usually pay tax on your UK income even if you are not UK resident. That includes UK rent, UK pensions and wages for work done in the UK. A double tax treaty can change who taxes what, but it has to be claimed.
👉 GOV.UK: Tax on your UK income if you live abroad
We go through each income type in 📖 UK non-resident tax rules, pensions in 📖 UK pension tax when living abroad, and share awards in 📖 RSUs and share options when leaving the UK.
Inheritance tax
Since 6 April 2025, inheritance tax on your worldwide assets depends on whether you are a long-term UK resident, meaning UK resident for at least 10 of the previous 20 tax years. If you are, you keep that status for between 3 and 10 tax years after you leave: 3 years if you were resident for 10 to 13 of the last 20, rising by a year at a time to 10 years if you were resident for all 20. After that, only your UK assets stay within inheritance tax.
👉 GOV.UK: Inheritance Tax if you are a long-term UK resident
👉 The law: Inheritance Tax Act 1984, section 6A (long-term UK resident)
The year you leave: split-year treatment and capital gains
Are you non-resident from the day you fly out? Not automatically. For capital gains tax, you count as UK resident for a whole tax year if you are resident for any part of it.
The exception is split-year treatment. If you meet the conditions, the year is divided into a UK part and an overseas part, and gains in the overseas part are only taxed if they are on UK land or the other assets non-residents are charged on.
Split-year treatment depends on why and how you leave. Check the 📖 Statutory Residence Test and the 📖 split-year treatment cases first. You tell HMRC you have gone on a 📖 P85 form or the residence pages of your tax return.
Common mistakes when leaving the UK
➜ Worrying about an exit tax that does not exist. The rule to plan around is the five-year rule, and it only matters if you sell while away and come back early.
➜ Coming back within five years. Gains you thought were tax free become taxable in the year you return.
➜ Selling in the tax year you leave without checking split-year treatment. If it does not apply, you are treated as UK resident for the whole year and the gain is taxed in full.
➜ Taking large dividends from your own company while abroad. For anyone returning on or after 6 April 2026, they are caught by the five-year rule whenever the profits were earned.
➜ Assuming no exit tax means no UK tax. UK property, UK income and inheritance tax all carry on.
Frequently asked questions
Is there an exit tax in the UK?
No. The UK has no exit tax for individuals in 2026/27, so leaving the UK does not trigger capital gains tax on your assets. The UK's equivalent is the temporary non-residence rules, which tax gains made while you are abroad only if you return within five years.
What is the UK equivalent of an exit tax?
The temporary non-residence rules, also called the five-year rule. They have been in UK law since 1998. If you were UK resident in at least four of the seven tax years before leaving, sell assets while abroad and return within five years, the gains are taxed in the year you come back.
Is the UK introducing an exit tax?
No exit tax for individuals has been enacted or officially announced as at October 2026. None was included in the November 2025 Budget or in Finance Act 2026. HMRC's Capital Gains Manual confirms no legislation charges individuals for ceasing to be UK resident.
How long do I have to live abroad to avoid UK capital gains tax?
More than five years, if you were UK resident in at least four of the seven tax years before you left. Return within five years and gains on assets you owned before leaving are taxed in the year you come back. UK property and land are taxed however long you are away.
Do I pay capital gains tax when I leave the UK?
Not just for leaving. You pay capital gains tax if you sell assets while you are still UK resident, if you sell UK property or land at any time, or if you sell other assets while abroad and return to the UK within five years.
Last reviewed on 22 October 2026 by Emma McDermott, ATT, founder of Global Tax Consulting, in line with the law in force at that date: Taxation of Chargeable Gains Act 1992, section 10A, and the HMRC guidance cited above.
How Global Tax Consulting can help
Plan your move before you go
Our exit plan establishes your residence position, times your departure and disposals, and plans for the five-year return window. Every plan is prepared and signed off by Emma McDermott, ATT.
➜ Your residence position established for the year you leave
➜ Departure and disposals timed around the residence line
➜ Split-year treatment and the five-year return window planned
➜ Treaty claims and returns handled when it is time to file
Typical fee
£1,000 to £4,000
Fixed before we start. Straightforward years sit at the lower end.
★★★★★
Rated 5.0 on Google and 4.9 on Trustpilot, from 240 reviews
★★★★★
“From day one, Emma has given me complete 360-degree support through my tax situation.”
Romeo
Nomad in the Philippines
★★★★★
“Emma was so responsive and helpful and within a few days had completed two years of tax returns for me.”
Rachel
Brit in Spain
★★★★★
“Emma provided exceptional advice on my international tax position as a UK expat.”
Lian
Nomad in Mexico